Last Updated on December 28, 2021 at 6:29 pm
The day after Budget 2018 proposed LTCG tax on equity and equity oriented mutual funds, life insurers saw an opportunity to push ULIPS as the “go to” instrument now. Abandoning mutual funds in favour of ULIPS only to avoid the LTCG tax is like undergoing chemotherapy to shave a head (Robin Williams*). In this post, I present a single most important argument to never touch a ULIP.
* Robin Williams was referring to Micheal Jacksons habit of taking power painkillers just to go to sleep!
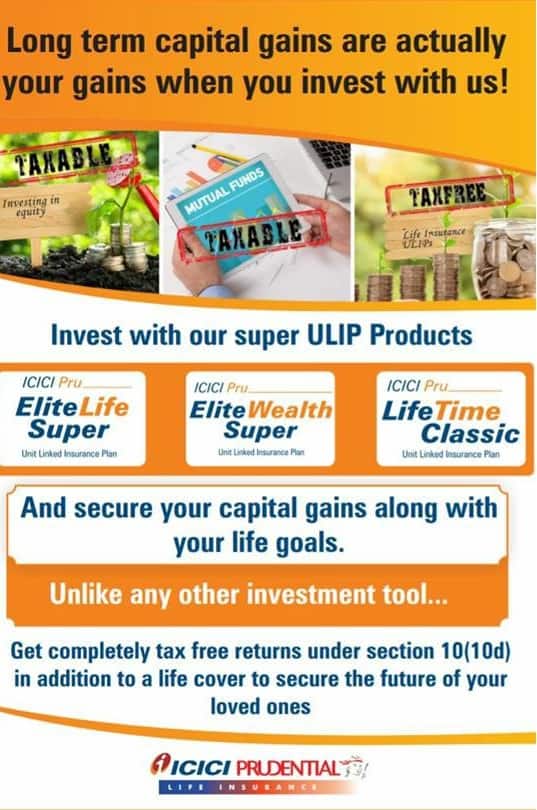
This is an ad by ICIC Pru Life Insurance.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
What is a ULIP? A ULIP is a combination of a life insurance cover and a mutual fund managed by the life insurance. Each year the cost of the life insurance cover will be deducted by removing ULIP fund units from your account. Hence unit-linked policy. As you age, the cost of life insurance increases (unlike term insurance). At the same time, as the value of your ULIP fund increases, the cost also decreases. Once the fund value exceeds the sum insured, the unit reduction will stop, but this takes several years. Read more: How ULIP Charges Reduce Returns!
In addition, there is a fund management charge taken from the fund value. Currently, this charge is well below that of regular mutual funds and a touch below or equal to direct mutual funds. There may be other charges like premium allocation and policy administration as a percentage of annual premium
Something that takes this long to explain should be avoided!!
ULIPS vs Mutual funds
Discussions on ULIPS vs mutual funds are often only about costs. I too have been guilty of this in the past. This is flawed because investors are missing the most crucial difference between ULIPs and mutual funds.
Let assume that both mutual funds and ULIPs have the same expenses (this is not true as mfs are less expensive when combined with a term plan, but please play along).
Then, ULIPs gains are tax-free and mutual fund LTCG is taxable. If we look no further then ULIPs seem “good”? Hang on.
Some questions for mutual fund investors?
Have you ever worried about the star rating of your fund? Changed funds when it lost stars? Changed funds when returns were poor?
Do you see ULIP investors talk about star ratings (it is available at Morningstar). Do you see them exit a ULIP after few years and buy a new one? Relatively speaking, the answer is a practical no.
The ULIP is meant to be a marriage in which you grow old in (literally as costs depend on that). And like marriages, it is purely a matter of luck if your ULIP does well. If it does not (many ULIP buyers don’t look!) then you are trapped. Sure, sure you can exit and buy a new ULIP at an older age, higher premium and higher (repeated) cost. Brilliant!
Ulips bring forth the true meaning of “never combine insurance with investing”.
I hate the NPS for the same reason too. You do not get married to your fund managers! If they are not performing, chuck them and find another one. while you do this, you do not jeopardize your life cover. That is taken care of by a term plan with constant premium which seems smaller and smaller due to inflation and a higher salary.
This is why mutual funds + term insurance is so much more superior to ULIPs. Forget the costs! The flexibility to move in and out as we please is essential for risk management in equity.
The fund manager risk is ULIPs is the real risk! In mutual funds, I can change fund managers at any point or shift to index fund at will.
Sure, now there is a 10% tax when I do the switch. So what? Will you take a chance of being stuck in a bad investment just to save some tax? If so, good luck with your ULIP purchase.
If you value a tighter control on your portfolio and flexibility, then this tax is of no consequence to your plans!
Time to think like a rich person and not worry about peanuts! That is the way to become rich. May we all lose and gain lakhs in the equity market each day so that unnecessary gymnastics like worrying if ULIPS are better or thinking about booking one Lakh LTCG each year to save 10,000 a year (a year!!) does not seem such a big deal to us!
Stay away from ULIPs, not because they are expensive, but because you could get stuck within a terrible marriage.
What if I invest in multiple ULIPS? Sure, a scattergun approach will get your somewhere, but who knows how far that would be from your target?
Investing is only for spending money latter, for a future goal. To achieve this, tighter control of the portfolio with risk management is essential. Ulips allow this, but only within the same establishment! It is like saying you can buy mutual funds but only from X or Y AMC. That is what a ULIP is! Oh, I forgot being unit-linked, it will remove units from your fund value (like trail commissions) to pay for your life insurance.