Investors often fixate on the returns of their investments. Some prefer higher returns and are willing to take on more risk, while others prioritize a guaranteed return with no threat to their principal investment. However, there are more aspects to consider in investing than just the returns.
While it could be argued that real returns (those exceeding inflation) are crucial for achieving long-term goals, this is just one aspect of the bigger picture. I often utilize slides in DIY investor meetings to understand better “investment return”.
The scenarios presented below, and many others, can be evaluated by investors with the freefincal Visual Goal Planner Calculator and nine other tools now available on the SEBI investor education site.
Also see: SEBI adds nine freefincal calculators to its investor education website. And, Freefincal’s Cost of Retirement Delay Tutorial is available at SEBI Investor Education Portal.
Think about a product, service, or fee that currently costs 10L. If the inflation rate is at 8%, as displayed below, the cost of this item will rise over time, represented by the blue line. The green line corresponds to the growth of the monthly investment sum at the average yearly interest rate, as previously indicated.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
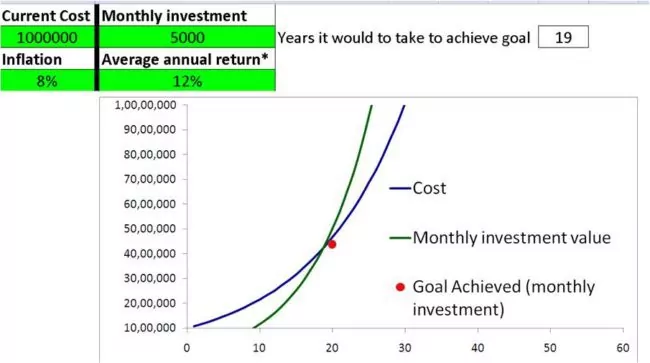
After 19 years, the value of the investment will overtake the cost. Meaning we would have to wait 19 years to make the purchase. The real return (approximately) in this scenario is 12% -8% = 4%. Now, what if the inflation was 10% instead of 8%?
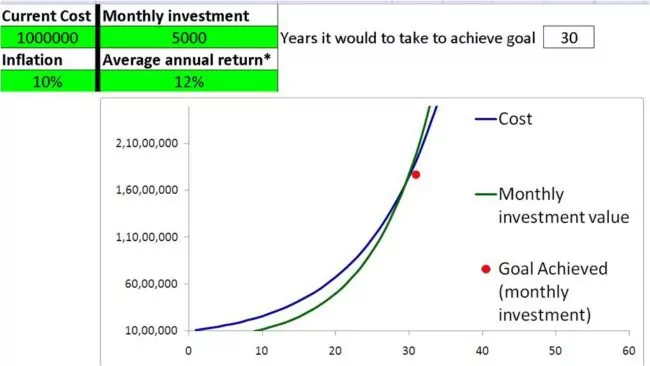
When inflation increases to 10%, purchasing the same investment will take 30 years. The return is still above inflation, but this does not help much. The purchase is significantly delayed. Why? Now consider the graph below.
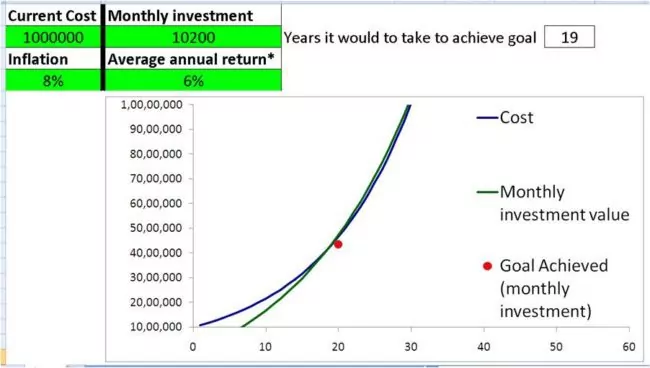
More than double the investment, with less than half the return, a real return of about -2% produces the same result as a real return of +4%: purchase after 19 years. What if we invest like we would expect a real return of -2% in an instrument that would give us a positive real return?
What if we invest 10200 monthly in an instrument that can potentially deliver double-digit returns? Unfortunately, many do the opposite. They invest less than the required amount (10,200) in instruments that offer negative real returns.
Loss of capital: Loss does not always mean a negative balance or an actual decrease in value.
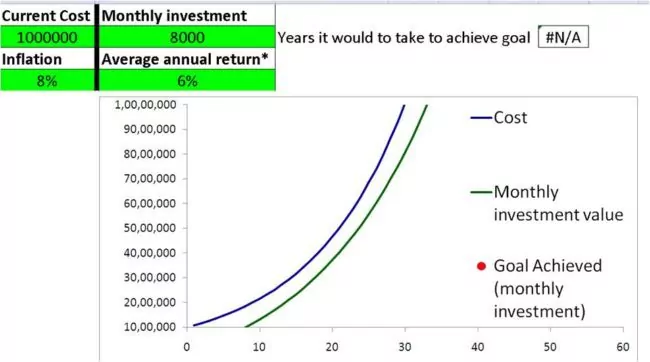
The result: permanent loss of capital (notice the gap between the curves at 19 years). I use the word permanent because these people fear notional short-term losses. They may never be able to make the purchase. Not investing enough is an ailment that can affect those who hope to earn a real return too!
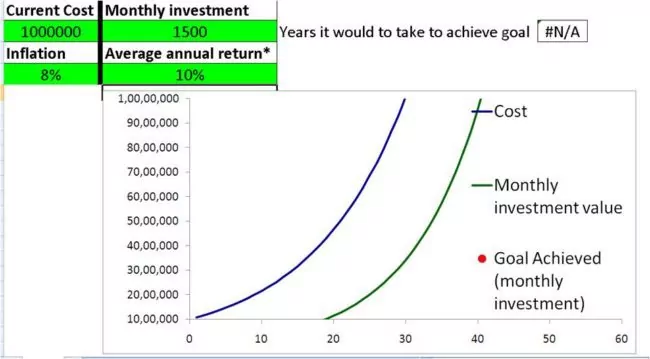
A real return of +2% means nothing if one does not invest enough. There is yet another side to this story. Those who can only invest little (say 1500 pm) cannot take excessive risk to get a higher real return. This scenario can be produced in an Excel sheet (as below) but is unlikely. At least, it is pretty uncommon.
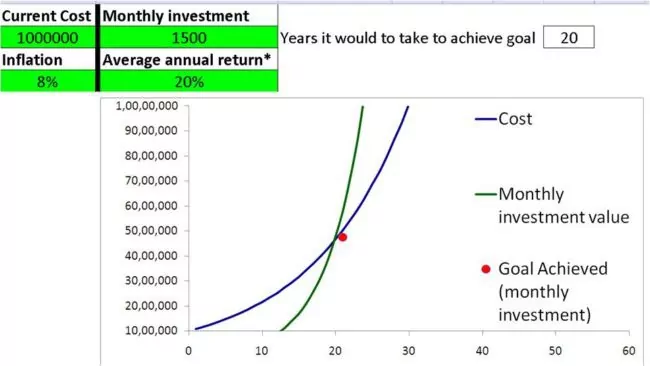
When faced with an expense (planned/unplanned), the primary concern is the available funds. At such times, the return we have earned and its relation to current inflation rates become immaterial.
The fundamental aim of the investment is to build sizeable wealth, not to outperform inflation or achieve a real return. It’s crucial to understand the relevance of inflation and devise strategies to counter it:
1) Investing in high-growth assets capable of generating returns that outpace inflation.
2) Allocating substantial capital to investments, even those that assure post-tax returns lower than inflation.
You can beat inflation by investing in FD/RD or endowment policies by simply investing enough. See here for an example: Can I Plan My Retirement With Recurring Deposits and Fixed Deposits? Or a real-life example: How I achieved financial independence without mutual funds or stocks.