Typically, retirement is the last and most important financial goal for most families. Before retirement, the kids would have started working and sometimes married too. However, this dynamic is fast-shifting because normal retirement is no longer at 60. It is now 50- 55.
Additionally, an increasing number of people are getting married and having children later in life. This means that kids may still be in school at retirement. So, how do we plan for this scenario?
Recently, a reader wrote: “Thanks a lot for this amazing tool to plan retirement. I wanted some help planning for certain expenses after retirement, such as a child’s college education, retirement home construction, marriage, annual vacations, and car purchases. As you can see, some of these expenses will be one-time (retirement-house construction, child’s marriage). In contrast, some others will recur for a certain period (such as child education, vacations, and car purchases).
I would like to see if the corpus I have already built (or would have built as of the retirement year) would cover these expenses. If my retirement corpus does not cover these expenses, I must build additional buckets or corpora from now until retirement month. If so, I would like to know how much additional investment I will need to make from the current month until retirement.
I am a non-finance / non-Excel person. So, perhaps this capability already exists, and I’m unable to figure it out. If these features do not exist currently, it would be awesome if they could be added to the FreeFinCal Robo Advisory Template.”
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
The freefincal robo advisor tool can handle goals that occur after retirement. You can either plan for this via a lump sum investment. Here is an example.
Consider a couple, both aged 40. Their monthly expenses are Rs. 1 Lakh. If they wish to retire at age 50, the corpus required is Rs. 7.92 Crore. The robo tool allows you to factor in existing investments and income sources after retirement. We shall not consider these here, as our goal is different.
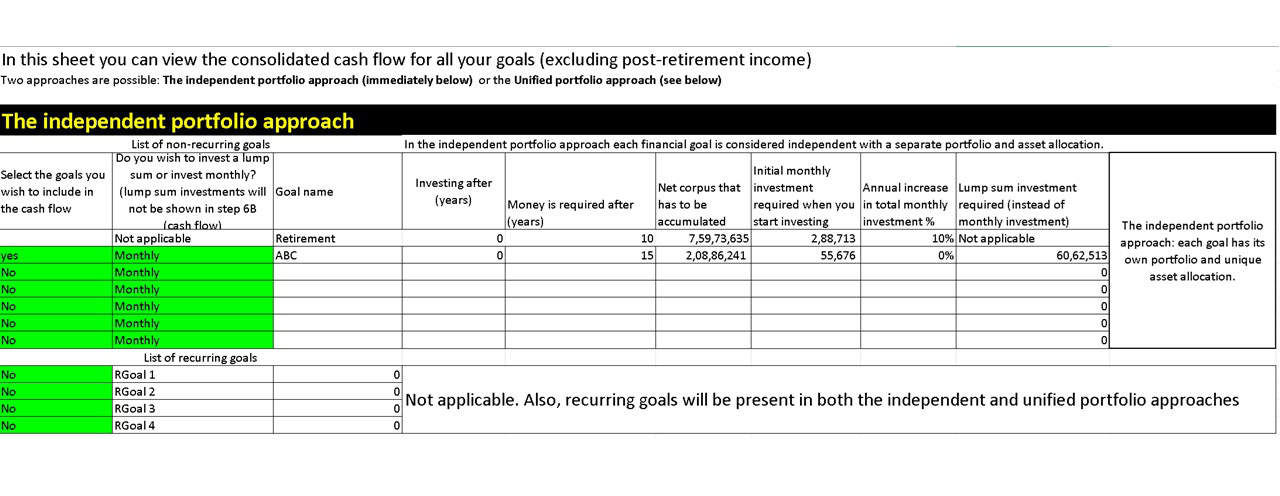
Suppose the couple has a goal or expense whose current cost is Rs. 50 Lakhs in 15 years. They will need this money five years after retirement. The future cost will be approximately two crores. There are two ways to account for this. They can invest a lump sum (Rs. 65 lakhs, depending on inputs and assumptions) or Rs. 60,000 (approximately) for the next 15 years.
If they choose the lump sum option, they have to plan to invest Rs. 65 lakhs (in this case) independently of their retirement planning. They will have to source Rs. 65 lakhs from their investments, and the remaining amount will be from their retirement corpus.
If they choose the monthly investing option, they will have to fund this investment from their retirement corpus after retirement. Therefore, the corpus will increase from Rs. 7.92 Crore to Rs. 8.27 Crore.
Freefincal Robo Tool users can change between lump sum and SIP options in Step 6A, Cash Flow. First, they will need to select “Yes” to include the goal in the cash flow chart in Step 6B and then choose the Monthly or Lump Sum option, as shown in the screenshot below.