Last Updated on December 29, 2021 at 6:00 pm
The public bond sale of Power Finance Corporation (PFC) Non-convertible debentures (NCD) starts today (Jan 15th) and will close on Jan 29th 2021. We look at who consider buying these bonds and who should not!
A non-convertible debenture is a bond that cannot be converted to equity at a later date. The interest from these bonds is taxable as per slab. There is not much worry on the credit rating front as these are AAA and the govt of Indian has more than 50% stake in the company. So it is a question of suitability which can be evaluated even without getting into the details of the issue.
Who should buy 10Y, 15Y Power Finance Corporation NCD Bonds?
The bonds would pay annual or quarterly interest which will be taxed as per slab. This means if you are young, far away from retirement and have no need for interest income, there is no need for you to consider any of these bonds.
If you are about to retire, or retired and are looking to add one more layer of regular income to your retirement portfolio in addition to your regular pensions, Senior Citizen Savings Scheme etc then you can consider the 10-year or 15-year issue.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
The effective yield of these bonds is a bit higher than GOI bonds available weekly via NSEGoBID. See: Can I get a pension using GOI bonds instead of LIC pension? These bonds do not have a sovereign guarantee. In case the fortunes of the corporation nosedive, the govt can be expected to bail out the corporation even if it means a delay in interest payments (like EPF!)
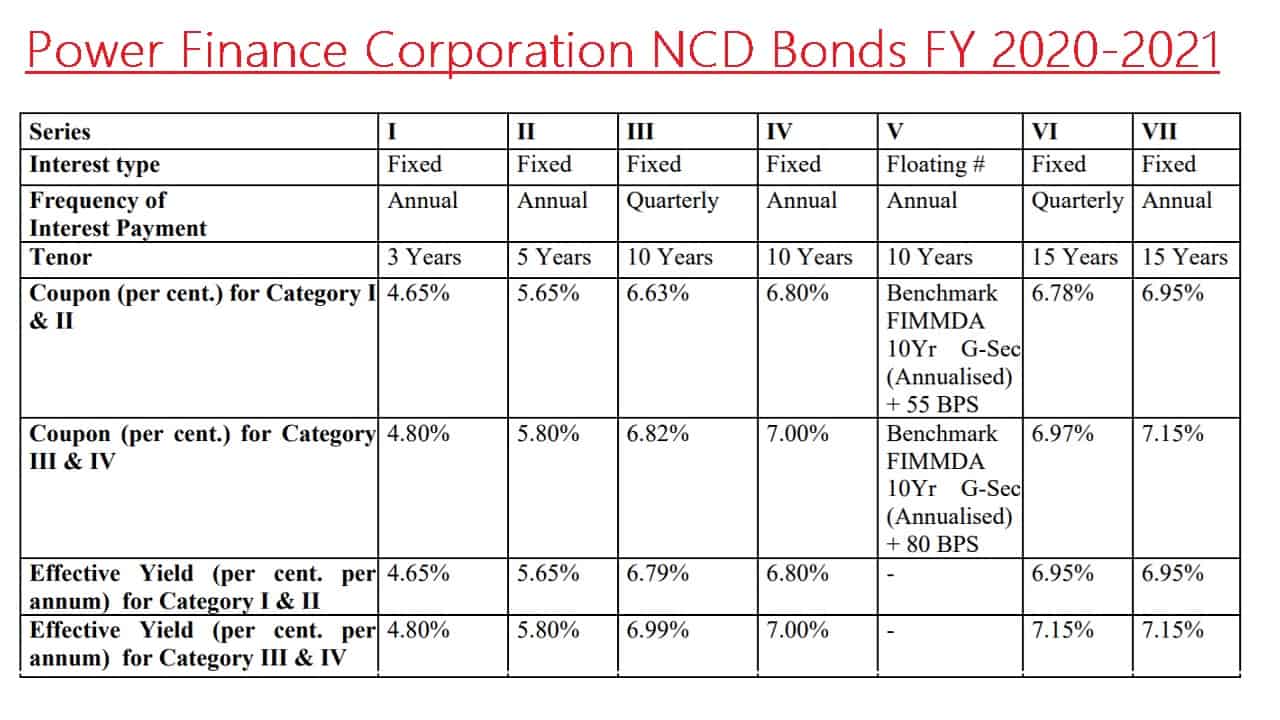
Category I and II are for non-individual investors (companies, institutions). Category III is high-net-worth investors with a subscription of greater than 10 lakh. Category IV is retail investors with less than or equal to 10 lakh investments. The minimum investment for retails investors is Rs. 10,000 and multiple of Rs. 1,000
Additional details for the floating rate NCD
Each year the interest will be fixed as 80 basis points (0.8%) + the annualised FIMMDA 10Yr G-sec benchmark rate for individuals but will not drop below 6% or increase beyond 7.5%
The 7% fixed rate for 10Y and 7.15% fixed rate for 15Y is indeed a good deal for senior citizens who need the income. Of course, with rising inflation, rates could increase this year and the possibility of a higher fixed rate deal is bright. Future tranches may carry a better rate, but if you need the income now, you need the income now!
The 3Y and 5Y rates are not of much use to retail investors. They are better off with a simple FD with cumulative option (not available for any tenure in this case) or a debt mutual fund or arbitrage fund for tax-efficient returns
If you are not a senior citizen, if you do not need regular income, then we strongly urge you to adopt a goal-based investment strategy, asset allocation and build wealth instead of buying such bonds.