Last Updated on February 12, 2022 at 6:15 pm
The notion of retirement has changed considerably over the years. Retirement for our parents meant a complete dependence on salary up to retirement and then complete dependence on pension afterwards. If we build a well-diversified retirement portfolio – a retirement basket as PV Subramanyam of subramoney.com would say – we can approach retirement with confidence and focus on spending time productively.
The picture below is a simplistic depiction of old retirement vs new retirement. The fall in the dependence on salary simply refers to the growth of retirement income sources. Regular readers may be aware of this technique to evaluate a retirement portfolio – Review Your Financial Freedom Portfolio in Seven Easy Steps.
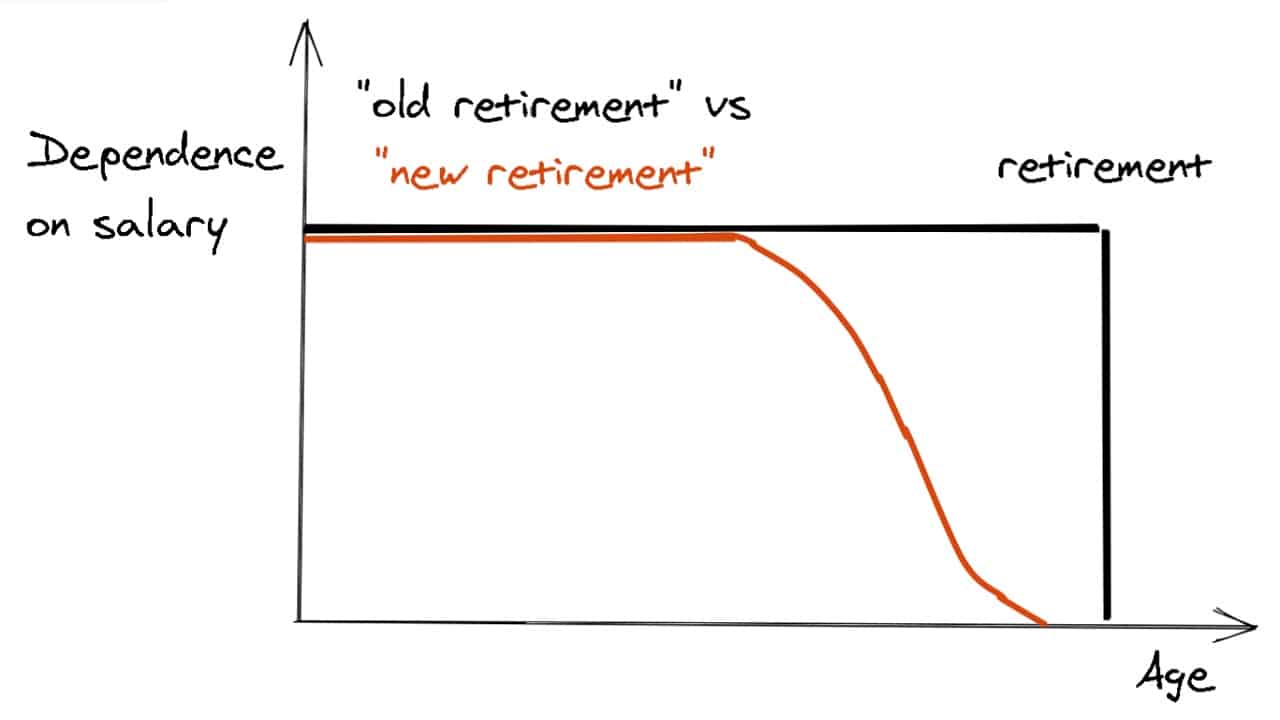
Every year we ask, “if I were to stop earning today*, how long will my investments be able to generate an income that keeps pace with inflation and also handle emergencies”. I started investing in NPS (2006) and equity MFs (2008). If I had checked the answer to this question in say 2010, it would be “0.5 years” or something of that order.
NB: * “stop earning today” is with respect to cash flow only. Retirement does not mean I sit with a coffee in one hand and phone in another speaking to “Ramamurthy Avre” We can work as long as we can, but can neither assume nor depend on that!
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
This means if I had quit working in 2010, my corpus would have lasted six months! That may not sound like much but it is a start and a start in the right direction. Cut to 2020, this number is about 43 years. So the dependence on my salary is significantly lower if not zero. This journey from under a year to something sizeable is depicted by the fall in the red line.
The primary way to beat inflation after retirement is to invest with the right asset allocation of say, equity and debt, change this equity allocation, use a bucket strategy, account for pension or rental income etc as implemented in the robo advisory template.
There is always some risk in actively managing this portfolio post-retirement or some risk that we would not be able to invest enough and/or achieve the corpus we desire. Therefore, it would be best to bolster the primary approach in additional ways.
Building the ideal retirement portfolio
Each of us has to ask what would the ideal retirement portfolio for each of us. Let go over mine as an example.
- 40% mandatory NPS annuity pension payout = expenses in the first year of retirement
- Corpus from MFs + 60% NPS corpus + PPFto go into bucket strategy (which will have a cash emergency component)
- dividends from a stock portfolio (see video below) for discretionary expenses
- stock portfolio value = emergency fund (don’t be surprised that six-month emergency fund in sb account is for those starting out. Rich people sell stocks)
- passive income. See these resources for details
- Active income from freelancing at will. More than the income it is for spending time productively and not worry if my son packed his lunch to work.
- Rental income ==> This is not applicable to me but maybe for many of you. Please do not buy real estate for rental income or as an investment if you cannot invest enough for retirement.
If we build a retirement basket with multiple income streams, we lower sequence of returns risk and the risk of emergencies – especially ones with recurring expenses. With luck, we might even leave a legacy behind.
Start thinking about alternative income streams. Those who cannot invest more have only one choice – manage their time better and find ways to turn their skills into income!
Also see: Retirement Stock Portfolio Analysis: September 2021