Mint Newspaper, led by Neil Borate, does a fabulous job reporting and educating about personal finance and investing. In March 2024, Mint featured my retirement portfolio: You only need a fund where returns remain consistent: Freefincal’s Pattabiraman.
In June 2025, they published an update on the portfolio: Why Freefincal’s Pattabiraman doesn’t believe in beating the market. Both articles are by Anil Poste. Note that these articles require a subscription. This is an infographic from the piece.
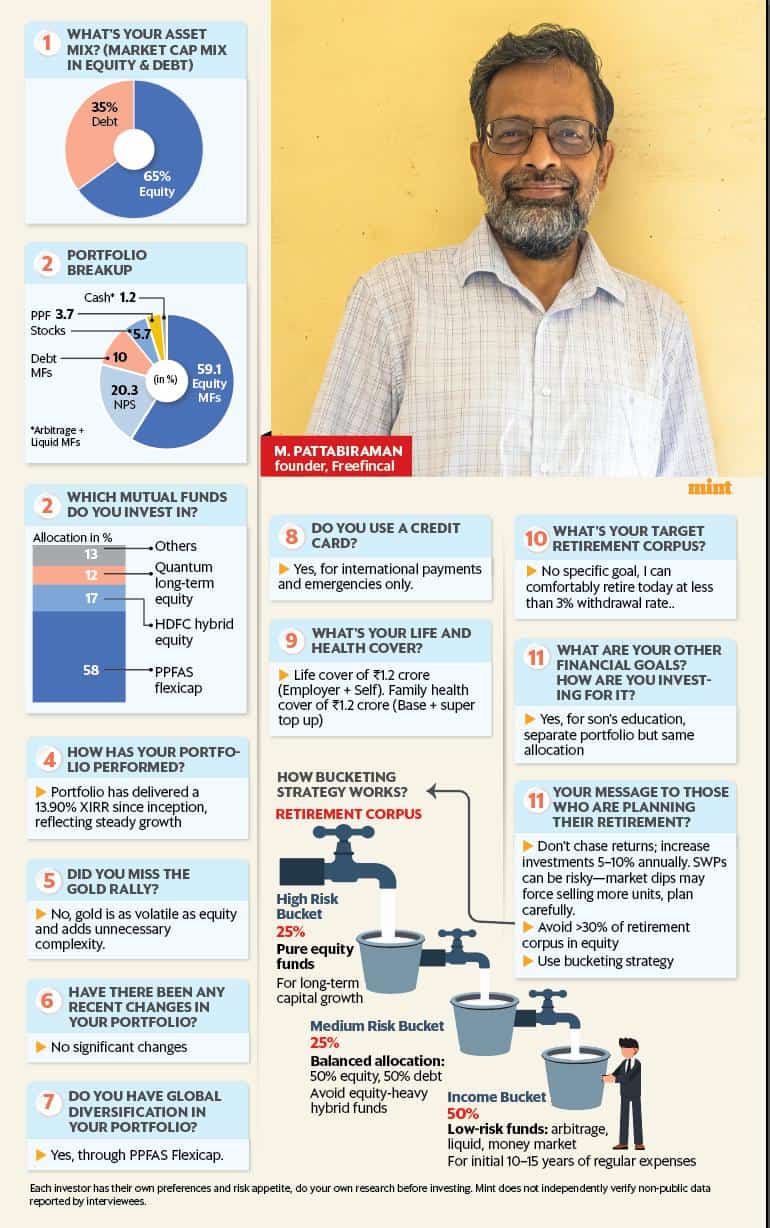
There were some questions and “observations” about my retirement portfolio, and I thought I could address them here.
Why are you not practising what you preach? Why are you investing in active funds while recommending index funds?
In this article, I explain ‘why’ in detail with pictures: Why are you recommending index funds when your portfolio has beaten the market?
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
I have not built this retirement corpus based on intelligence. I have behaved the opposite most of the time. Only around 2018 or so did I say, “I am going to stop making silly fund purchases and consolidate my portfolio.”
So the portfolio you see today is the residue of all my past mistakes. Switching from active to passive funds will only incur tax now. If I switch fresh investments to passive, it will take 13 years (calculated when I wrote the above article) for the passive fund to outweigh the active fund. Adding a passive fund is only clutter for me now.
I am only suggesting that young earners use passive funds and not repeat the mistakes I made. If you want to choose active funds, be ready for extended periods of outperformance. Whatever you use, have a proper financial plan first.
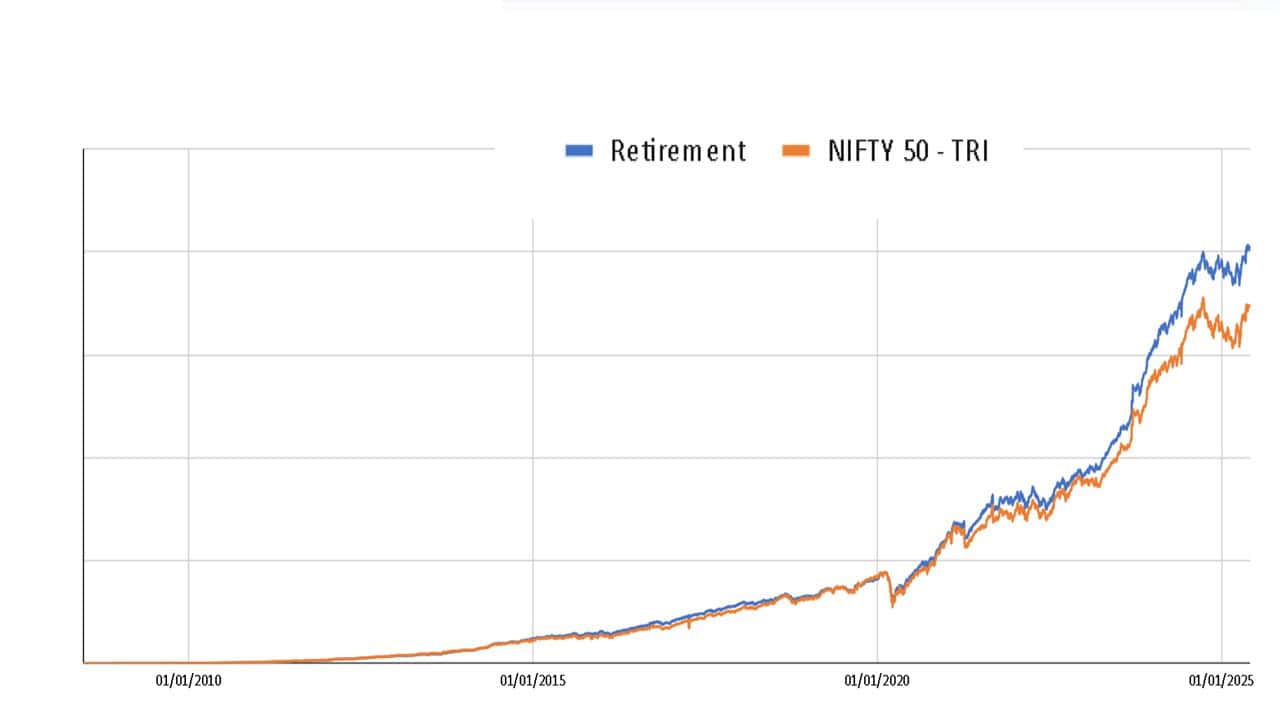
This is the evolution of the equity mutual fund part of the retirement portfolio from June 2008 to May 2025. This was created with the freefincal Google Sheets Mutual Fund and Stock Portfolio Tracker.
What is this 13.9% return? Is this return not low for a portfolio that is 17 years old?
This is my retirement portfolio (as of May 24th 2025)
| Asset | Weight | XIRR |
| Stocks | 5.72% | 7.44% |
| Equity MF | 59.08% | 16.92% |
| NPS | 20.28% | 9.42% |
| PPF | 3.72% | ~ 7.5% |
| Debt MF | 9.99% | 8.28% |
| Cash | 1.21% | ~ 5 to 6% |
Portfolio XIRR since inception, excluding PPF and cash and direct equity (that is for 89% of the total portfolio), is 13.90%
A nearly 14% return for 90% of the entire portfolio (which, for several years, was dominated by debt via NPS) after 17 years is acceptable to me any day.
Mutual Fund Holdings (as of May 24th 2025)
| Fund Name | Asset Class | XIRR | Weight |
| Parag Parikh FlexiCap (Since NFO investor. ‘lucky’ it worked) | Equity | 20.75% | 58.22% |
| HDFC Hybrid Equity (Since Sept 2011) | Equity | 14.56% | 16.91% |
| Quantum Long Term Equity (Since Feb 2013) | Equity | 13.90% | 11.56% |
| UTI Low Volatility (Since NFO investor) | Equity | 14.90% | 13.31% |
| ICICI Gilt Fund | Debt | 7.67% | 14.56% |
| Parag Parikh CHF (Feb 2021 Rebalance proceeds) | Debt | 12.99% | 3.93% |
| Parag Parikh DAF (Switched from CHF to DAF for tax efficiency; Since NFO investor) | “Debt” | 8.57% | 9.88% |
Do you regret not investing in gold?
No. I have explained why I do not invest in gold here – What you need to know about gold before investing in it.
Also, Siddhanta Pinto, host of the Get Rich with Pattu podcast, mentioned a quote by Rakesh Jhunjhunwala (in response to why he did not invest in crypto) – “You don’t need to go to every party”.
I am content with where things stand. Of course, readers may think it is sub-optimal or unremarkable, which is fine. At the end of the day, discipline with unwavering focus is the key.