A reader says, “I want your insights regarding my investments”.
- Age:32
- Profession: Consultant
- Emergency fund – building
- Term insurance – yes
- Health insurance – yes
“Equity investments as of July 2024 – 12 lakhs (I’m not going to touch it anytime ). From next month, I can invest at least 75k, which is 50% of my income (trimmed down emi and all expenses after watching your videos). I’m planning to increase it by 10% every year”.
“My doubt is
1. Should I invest all 75k in equity?
2. Or should I patiently invest 75k in bonds for the next five years and build a corpus of (60*75=45lakhs) in bonds,
From then on, I would get 45k as interest payout, combine it with 75k, and invest in equity.
3. Or should I allocate 50-50 in debt & equity?
My expectation is not more than 12% for the next 15 years. I aim to achieve 10CR in the next 15 years(max 20 years)”.
You have not mentioned any specific goal other than ten Crores. So, let us treat it as a general goal (and not retirement, where the math will be different). You also did not mention whether you have any fixed-income instruments. So, we shall assume it is zero.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Option 1: Putting everything in equity is too risky. So avoid.
Option 2: Investing in bonds and then investing the payout in equity wastes time and money (tax).
Option 2: A balanced mixture of equity and debt is the right way. But you also need a de-risking plan, as shown below.
The freefincal robo advisor tool suggests the following asset allocation schedule for 12% equity and 6% fixed income return expectations after tax.
| Year of investment | Suggested Equity allocation | Suggested Fixed Income Allocation |
| 1 | 60% | 40% |
| 2 | 60% | 40% |
| 3 | 60% | 40% |
| 4 | 60% | 40% |
| 5 | 60% | 40% |
| 6 | 60% | 40% |
| 7 | 60% | 40% |
| 8 | 60% | 40% |
| 9 | 55% | 45% |
| 10 | 50% | 50% |
| 11 | 45% | 55% |
| 12 | 40% | 60% |
| 13 | 35% | 65% |
| 14 | 30% | 70% |
| 15 | 25% | 75% |
| 16 | 20% | 80% |
| 17 | 15% | 85% |
| 18 | 10% | 90% |
| 19 | 5% | 95% |
| 20 | 0% | 100% |
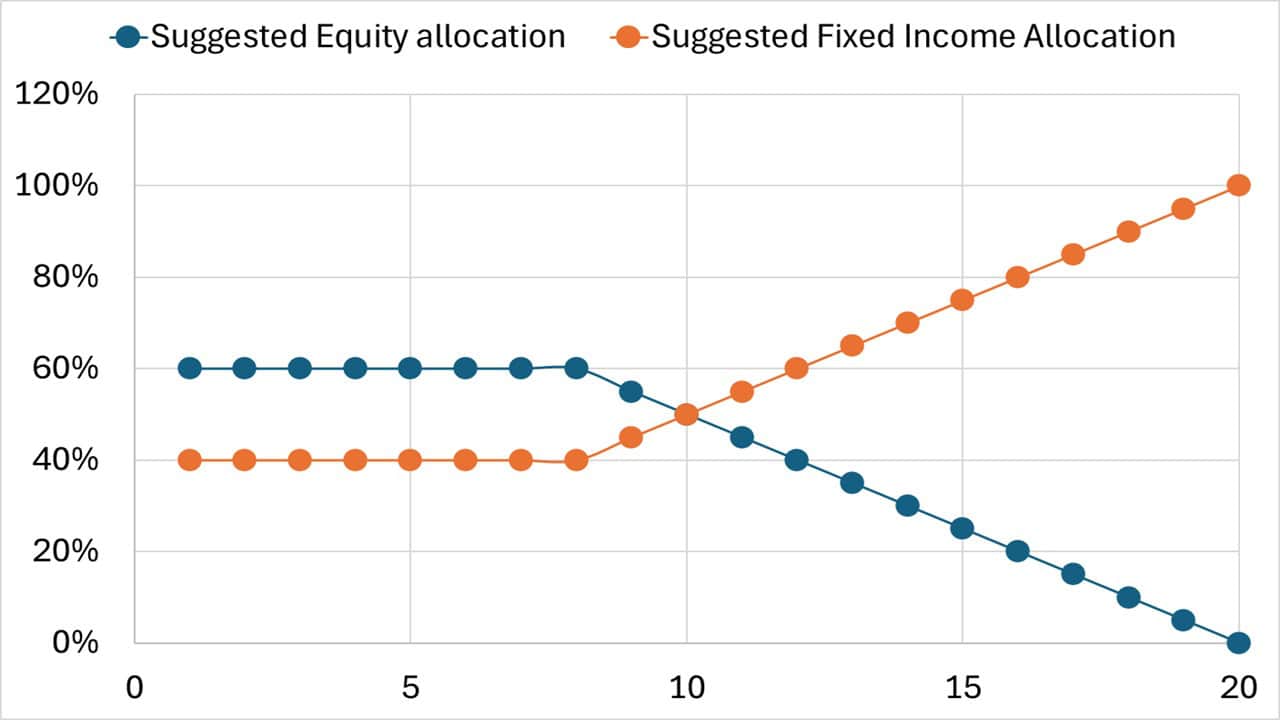
Try to increase your income so that your investment can also increase. This will increase the probability of getting close to the 10 Crore mark. If everything goes to plan, there is a good chance of achieving this in 15-20 years (closer to the 20Y mark).