A reader wants to know how real estate taxation works for resident individuals after the amendment to the Finance Bill 2024. Here are the details.
- I bought land at a price of 5L in 1995.
- The valuation report by the government registered and reputed valuer with all my value additions (fencing, water well, small house for caretaker etc) is valued at 20 L as of 1.4.2001.
- However, circle rate for 2001 is not known, it could be that it is less than 20 L. I have to check with the registrar’s office if they had a circle rate for this remote area those days for the years 2000-01″.
- Selling it now for four Crores.
Let us now compute the tax with and without indexation.
Without indexation
- Actual capital gain = Rs. 3.8 Crores.
- 12.5% tax on this plus 4% cess = Rs. 49.4 Lakhs.
With indexation
- The cost inflation index (CII) in 2001 was 100.
- CII for the current FY (2024-245) is 363
- So the indexed purchase price is: 20 Lakhs X 363/100 = 72.6 Lakhs
- Indexed capital gain = Rs 4 Crores minus Rs. 72.6 Lakhs = Rs. 3.274 Crores,
- 20% tax on this gain plus 4% cess = Rs. 68.099 Lakhs
We can now choose the lower of the two methods and pay Rs. 49.4 Lakhs as tax. Options to lower this tax include buying section 54EC bonds or building/buying another house.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Why did the indexation option result in a higher tax in this example?
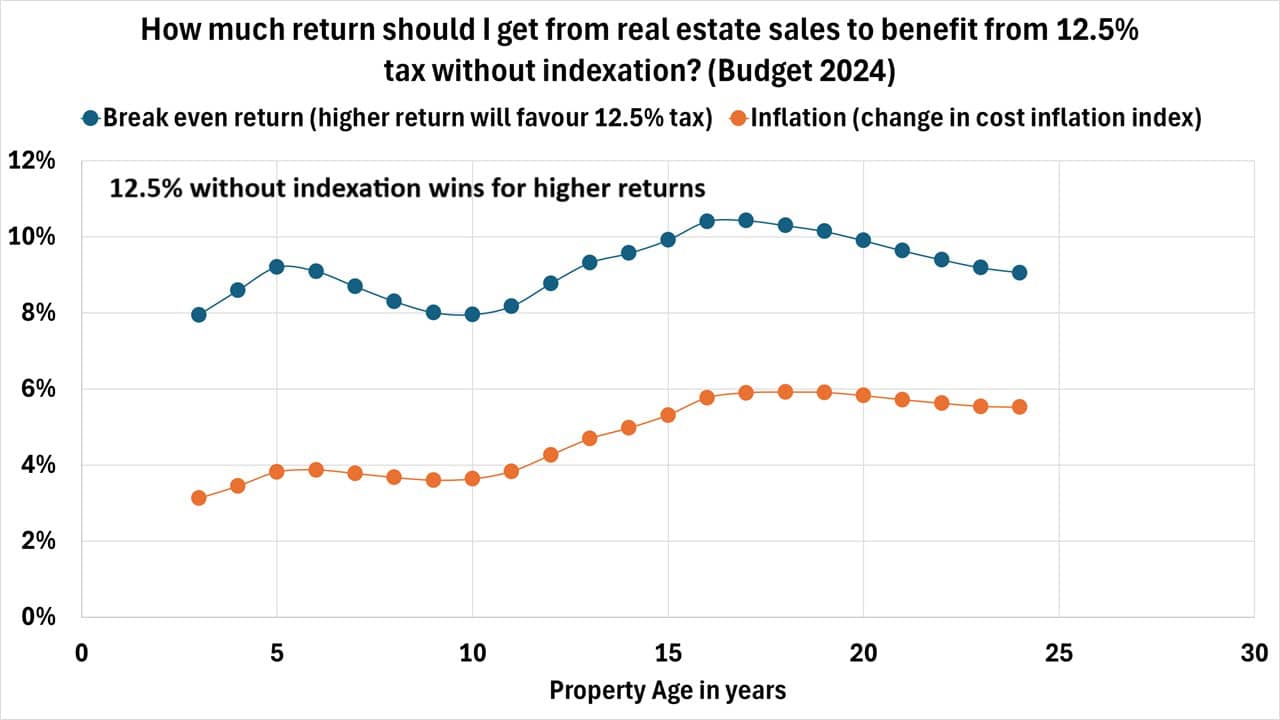
We had shown earlier that absolute returns have to be nearly three times higher than inflation for the 12.5% tax rule to be beneficial!
Let X = % capital gain (sale price – purchase price)/purchase price.
Y = % change in the cost inflation index
(CII in the year sold minus CII in the year purchased)/CII in the year purchased
If X> 2.667*Y, the 12.5% tax is favourable
If X < 2.667*Y, we will pay more tax with 12.5% than with 20% with indexation.
This is summarised in this graph.
In this example,
X = 19000%
Y = 263%
X/Y = 72.74 times! So, the 12.5% tax rule is favourable.
Other FAQ
- Will there be indexation from 1995 to 2000? => No. You will have to find the valuation on 1st April 2001 using a professional real estate valuer and use that as the purchase price (for properties purchased before April 2001).
- Or do I need to find out if there was a circle rate in 2000? => No.
- Will the govt accept the valuer report of fair market value as of 1.4.2001? => Yes. There is no need to show this unless asked for by the income tax department if there is a query on the IT return.