Last Updated on August 22, 2022 at 11:15 pm
With the Sovereign Gold Bonds, 2021-22 (Series IV) open for purchase from July 12-16, 2021, a reader asks, “how much return can I get from these bonds”? The only honest answer one can offer is, we do not know. Gold is too risky an asset class to make a prediction.
Here is why we have no idea what return Sovereign Gold Bonds would offer in addition to the guaranteed 2.5% incentive to buy these instead of physical gold. The situation is the same for mutual funds: Do not expect returns from mutual fund SIPs! Do this instead!
These are more than 9000 eight-year return data points of Gold INR and Gold USD from 31-12-1986 to 9-7-2021. Eight years is the tenure of these bonds. The returns have swung from about -7% to 23%. Anyone who offers a definitive return number from a gold investment is either speaking through his hat or is trying to sell you something.
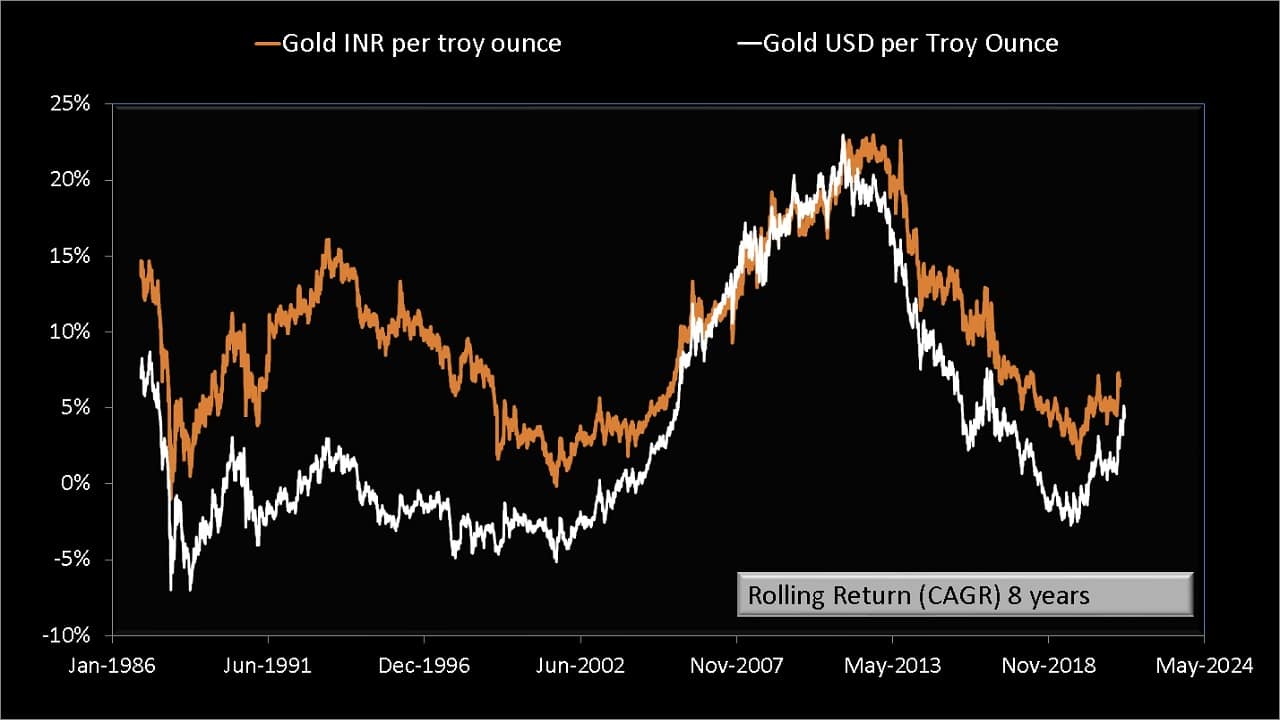
If you want to invest in Sovereign Gold Bonds for returns, you essentially count on luck. I think our money deserves better respect than that. You can wait for any amount of time, but this uncertainty will never go away.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Who should buy Sovereign Gold Bonds? Who should not?
Does this mean all investors should avoid Sovereign Gold Bonds? No. They should first define their need.
- For immediate use: the answer is obvious. Buy physical gold or jewellery.
- For future use (e.g. accumulating gold for a marriage).
- If the need is more than 10Y away, a normal mix of equity and fixed income should suffice.
- If the need is 8-10Y away, you can buy Sovereign Gold Bonds.
Why? Sovereign gold bonds offer a tax-free, risk-free way to accumulate gold as long as your future gold purchase is more than eight years away*. You also get 2.5% interest (taxable as per slab) on the initial gold value as a “thank you for reducing gold imports(temporarily)” gift from the govt.
This is risk-free because the bond tracks the price of 24-carat gold, and at any given time and after eight years, one could buy 22-carat jewellery. * These bonds cannot be sold in the middle of the tenure unless you are willing to take a loss. So if you want to buy jewels after 10 years, buy the bonds for the first eight years and then hold cash or buy the gold asap.
- If you wish to include gold for diversification, then the gold instrument has to be liquid. You will need to buy and sell freely without loss. Sovereign Gold Bonds are not suitable for this. Those familiar with ETFs can choose a liquid ETF like Nippon India ETF Gold BeES or use a Gold fund (a fund of fund that invests in a gold ETF).
- One could argue that gold is not necessary for a long-term portfolio and effective management is possible with stocks and bonds. Also, see: How much gold in my portfolio will protect against a market crash?
- Sovereign Gold Bonds are also unsuitable for tactical exit and entry in gold. This will again need ETF and gold and a strategy. See for example: Is this a good time to buy gold? A tactical buying strategy for gold
Therefore we recommend that investors eyeing Sovereign Gold Bonds first define their requirements clearly. If they want to “get some returns” from gold or use it as part of a diversified portfolio, then these bonds are not suitable. We recommend using them only if you have a future need (about 8-10Y away) to buy gold jewellery.