Last Updated on February 6, 2025 at 10:36 am
Previously, taxpayers could file belated returns up to two years from the end of the relevant assessment year without incurring any penalties other than interest, except that these returns did not allow carry forward of losses. The period for filing belated returns was reduced to one year and then further restricted to the end of the AY.
About the author: Manmohan Sethumadhavan is a freelancer, investor, and personal finance enthusiast “in search of the absolute truth.” You can follow Manu on Twitter @ManuTsr. Also, read his articles:
- Is 87A rebate applicable for capital gains after budget 2025?
- Freefincal Capital Gains Taxation Rules Ready Reckoner
- The underestimated risk of encumbrance in real estate investing (which equity doesn’t have)
- What is a “Specified Mutual Fund” according to Finance Bill 2024?
- How to calculate LTCG with Grandfathering for equity shares that split – How to fill Schedule 112A.
- Have capital gains and dividends? Correct this autofill while filing ITR!
Later, with the introduction of fees u/s 234F, late filing became costlier. The deadline for belated returns was further reduced to 31st December of the AY. Updated returns u/s 139(8A) were introduced to encourage voluntary compliance and generate additional revenue. These could be filed within 24 months from the end of the AY, with an additional tax liability under Section 140B, and other conditions, with rates varying based on the timing of filing.
Amendment in Budget 2025:
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
In the Budget 2025, the filing window for updated returns under Section 139(8A) was extended from 24 months to 48 months from the end of the relevant AY. The amendment also revised the rates of additional tax payable under Section 140B. The new rates are as follows:
- Within 12 months from end of AY: Additional tax at 25% of the aggregate of tax and interest payable.
- After 12 months but before 24 months: Additional tax at 50%.
- After 24 months but before 36 months: Additional tax at 60%.
- After 36 months but before 48 months: Additional tax at 70%.
Here is a matrix of due dates of filing returns for different years:
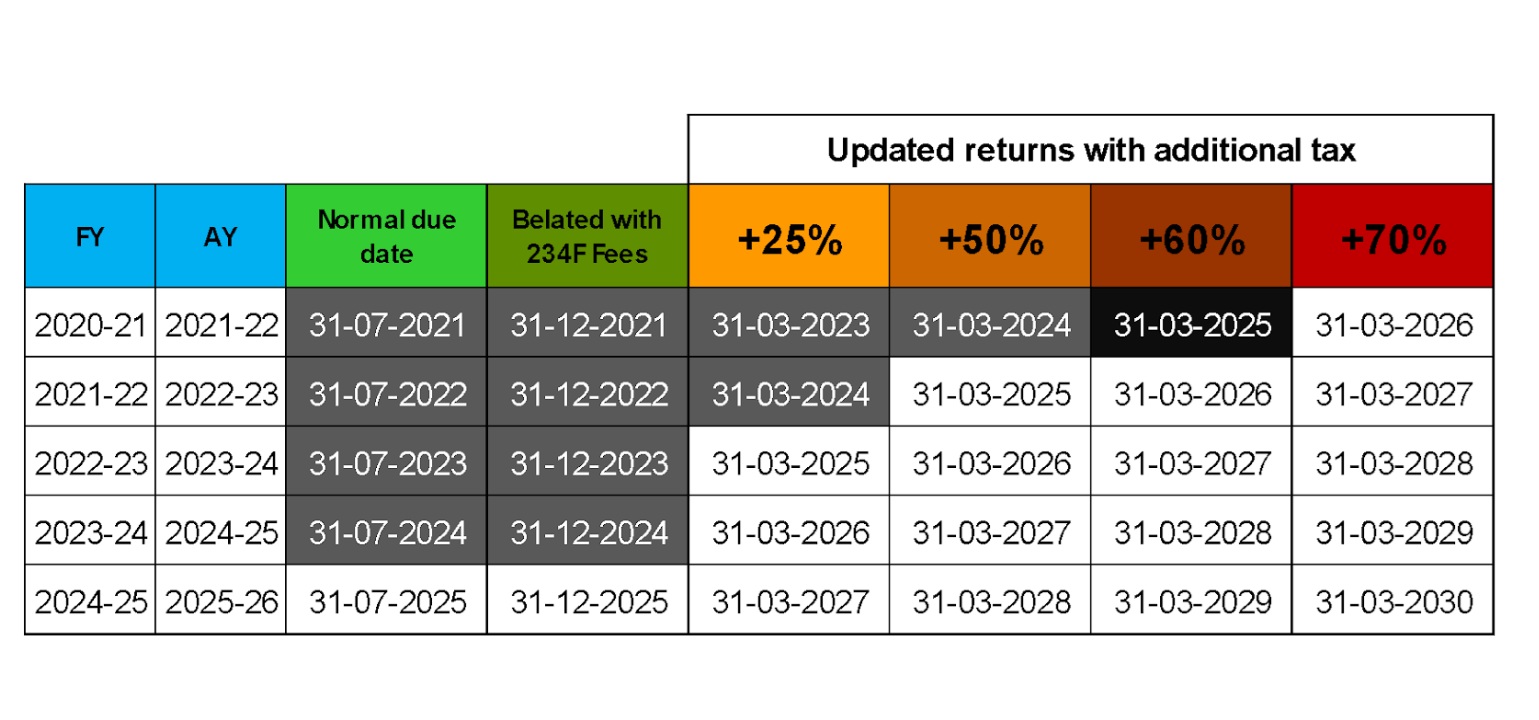
The greyed-out columns are time-barred. For FY 2020-21, updated returns with 60% additional tax, i.e., after 24 months but before 36 months, cannot be filed due to an interesting condition. The period for filing updated returns before the amendment (24 months) ended on 31-03-2024. With the new amendment, the returns can be filed with 60% additional tax till 31st March 2025. But the new amendments will take effect only from 1st April 2025. So, for that AY alone, one has to wait till 1st April 2025 and file with additional 70% tax. Note that all other conditions for filing updated returns remain the same.