Last Updated on February 3, 2025 at 2:55 pm
Background of the case: For the financial year 2023-24, a rebate of Rs. 12,500 was available under Sec.87A for the old regime and Rs. 25,000 for the new regime. However, from July 5 onwards, this rebate was not made applicable to special rate incomes in the new tax regime, following a software update.
Budget 2025 coverage
- Budget 2025: New Tax Regime (new slabs) vs Old Tax Regime Calculator: Check which is better
- Budget 2025: FAQ about revised new tax regime slabs
- Budget 2025: Income Tax Benefits in NPS Vatsalya Scheme
Note that the rebate under old regime was still being allowed for all types of incomes. The 87A rebate, irrespective of regimes, is not available for long-term capital gains from equity shares or equity oriented mutual funds u/s 112A, as it is disallowed specifically in section 112A itself, and thus, there is no confusion at any time for this part.
About the author: Manmohan Sethumadhavan is a freelancer, investor, and personal finance enthusiast “in search of the absolute truth.” You can follow Manu on Twitter @ManuTsr. Also, read his articles:
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
- Freefincal Capital Gains Taxation Rules Ready Reckoner
- The underestimated risk of encumbrance in real estate investing (which equity doesn’t have)
- What is a “Specified Mutual Fund” according to Finance Bill 2024?
- How to calculate LTCG with Grandfathering for equity shares that split – How to fill Schedule 112A.
- Have capital gains and dividends? Correct this autofill while filing ITR!
The sudden change in the department’s software from July 5, 2024, was criticized for overriding legal provisions of Section 87A, leading to confusion. Later, the Honourable High Court of Bombay ruled in favour of the tax payers, and ordered that the intent was not to disallow the rebate under Section 87A for all special rate incomes but specifically for those explicitly mentioned, and that without specific legal changes in the Income Tax Act disallowing the rebate for all special rate incomes, the rebate should still be applicable for incomes taxed at slab rates. The department accepted the directive and made necessary changes in the utility at the end of December 2024.
However, in 2025 budget, an amendment was made to Section 87A, inserting a second proviso, apart from increasing the threshold limits for the rebate.
“Provided further that the deduction under the first proviso, shall not exceed the amount of tax payable as per the rates provided in section 115BAC(1A).”
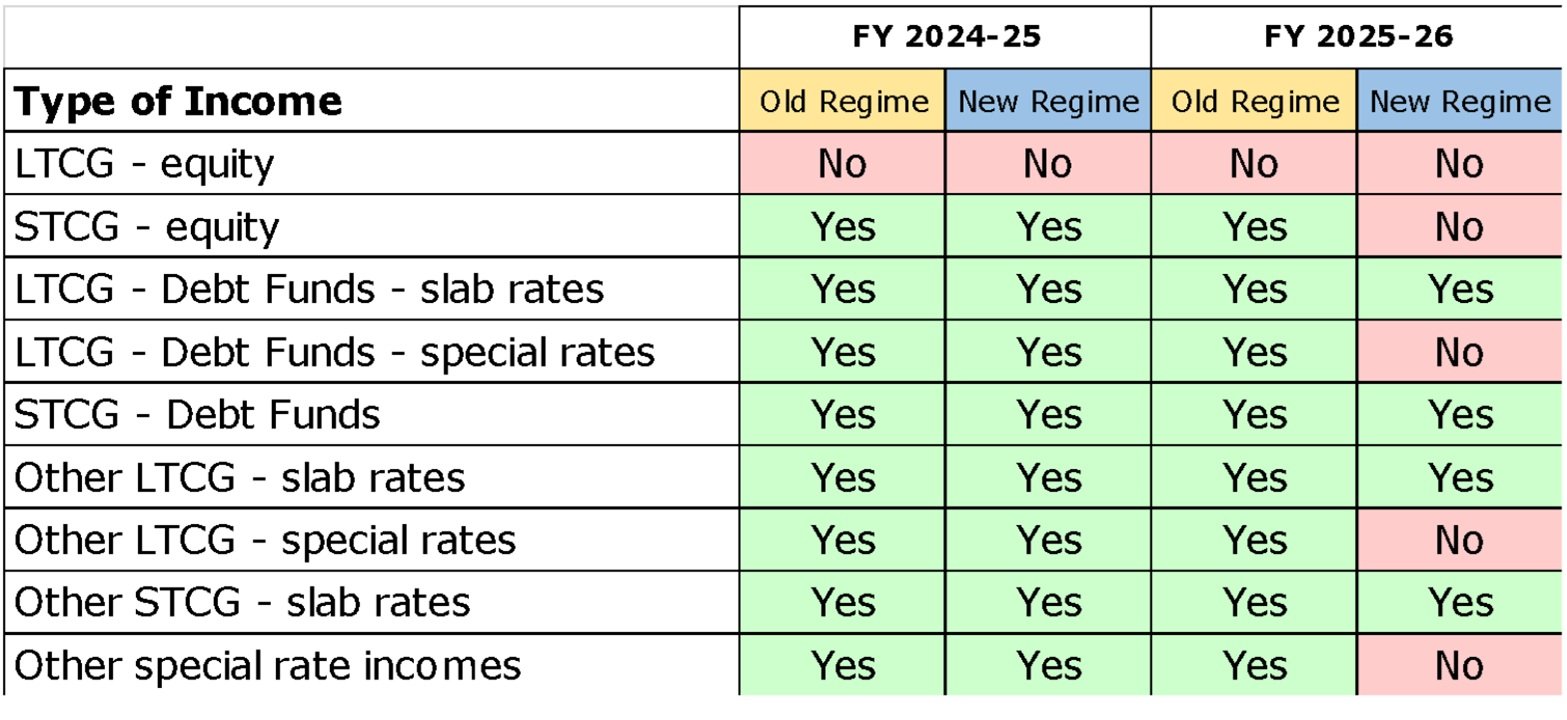
So, it has been made clear that the rebate in case of new regime is applicable only to the tax computed as per slab rates under section 115BAC(1A). This amendment is applicable only from FY 2025-26 (AY 2026-27).
Conclusion:
- There is no change in the scope of rebate for those who file under the old regime. The rebate is applicable for all types of incomes, except LTCG from equity, for all years.
- There is no change in the scope of rebate for those who file under the new regime in FY 2024-25 (AY 2025-26). The rebate is applicable for all types of incomes except LTCG from equity.
- For new regime from FY 2025-26 (AY 2026-27) onwards, the rebate is applicable only for tax computed as per slabs and not for any special rate taxes. But, to calculate the applicability threshold of the rebate, the total income including all special rate incomes will be considered.
- Please use the Freefincal Capital Gains Taxation Rules Ready Reckoner to find the capital gains tax rates for different assets, as for FY 2024-25, there are different rates for assets depending upon the date of acquisition and date of sale.
- For tax payers who do not have any other income other than capital gains calculated under special rates, or a mix of slab rate incomes and special rate incomes, can still opt for old regime in FY 2025-26, if they fall under the limits and if beneficial for them, as they can avail the rebate u/s 87A under old regime as before.
- All these interpretations are as on this date. This may change when further amendments are made, either when the Finance bill is passed in the Parliament, or when the new Finance bill is introduced, which is expected next week.