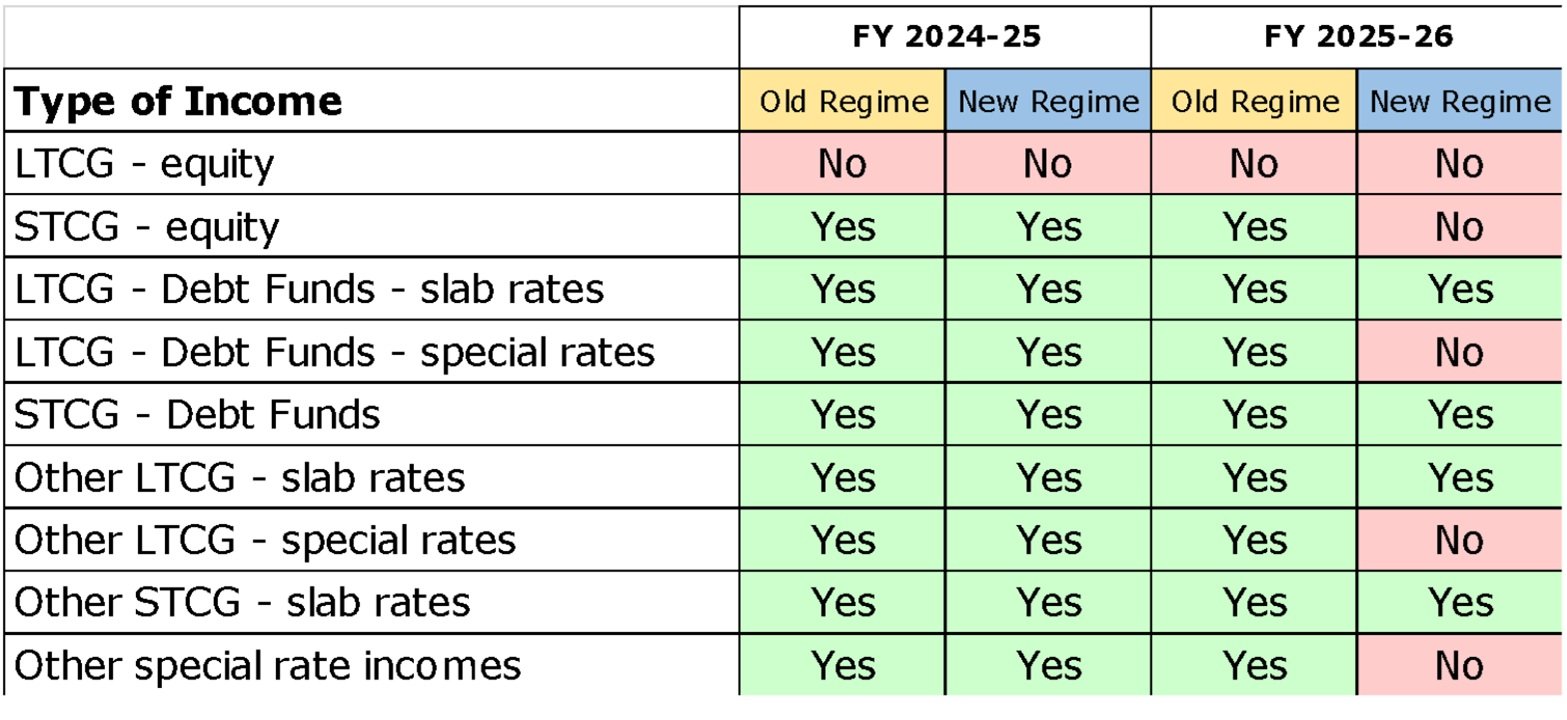
A reader says, ” This is concerning the article titled: Is 87A rebate applicable for capital gains after budget 2025. It mentions that the rebate is available for LTCG – Debt funds – special rates for FY 2024-25. However, the calculator on the income tax department website does not provide the rebate. This is for the sale of debt mutual funds bought before 2023 and sold in Feb 2025. Kindly clarify.
About the author: Manmohan Sethumadhavan is a freelancer, investor, and personal finance enthusiast “in search of the absolute truth.” You can follow Manu on Twitter @ManuTsr. He is the author of the above-mentioned article. Some of his other articles are:
- Freefincal Capital Gains Taxation Rules Ready Reckoner
- The underestimated risk of encumbrance in real estate investing (which equity doesn’t have)
- What is a “Specified Mutual Fund” according to Finance Bill 2024?
- How to calculate LTCG with Grandfathering for equity shares that split – How to fill Schedule 112A.
- Have capital gains and dividends? Correct this autofill while filing ITR!
87A – Clarification
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
The background – FY 2023-24:
Section 87A provides for a rebate in case the total income is not above 5 Lakhs – This is for the old regime. 1st Proviso to 87A provides for a rebate in case the total income is not above 7 Lakhs – “where the total income of the assessee is chargeable to tax under sub-section (1A) of section 115BAC” – i.e., for tax payers who file under the new regime. Rebate u/s 87A is not eligible for income computed u/s 112A, i.e., Long Term Capital Gains from equity – both for old and new regimes.
The issue
The rebate u/s 87A was made available to all types of incomes for all the past years including STCG from equity which was calculated at 15%, and other special rate incomes, except LTCG from equity which was specifically excluded – for the old regime. It was similar to the new regime also. But on July 5th, 2024, the department released a new version of software, which denied claiming the rebate under new regime for income taxed under special rates. They were interpreting the section like:
“where the total income of the assessee that which is chargeable to tax under sub-section (1A) of section 115BAC”
As a result, the taxpayers who had earlier filed the returns claiming the rebate also received a notice denying the claim.
Intervention of the Court
The issue was challenged, and the Honourable High Court of Bombay gave an interim relief on 20th December, 2024 in favour of the taxpayers, directing the CBDT to extend the due date for filing the returns, and to allow the taxpayers to claim the rebate. The court also commented that rights granted through legislation cannot be modified through procedural changes or even through executive orders. Accordingly, the due date was extended to 15th January 2025, and also a software update was released that permitted claiming the rebate.
On 24th January 2025, the court pronounced a final order in PIL No.32465/2024, which made the interim order absolute. But the court did not go forward to interpret the section, and the issue of adjudication of eligibility of a claim under Section 87A is left to the authorities.
Amendment of section 87A
in 2025 budget, an amendment was made to Section 87A, inserting a second proviso, apart from increasing the threshold limits for the rebate.
“Provided further that the deduction under the first proviso, shall not exceed the amount of tax payable as per the rates provided in section 115BAC(1A).”
So, it has been made clear that the rebate in case of new regime is applicable only to the tax computed as per slab rates under section 115BAC(1A). This amendment is applicable only from FY 2025-26 (AY 2026-27).
Note: All the issues related to this section can be reduced to a single question – Whether it is applicable also for special-rate incomes or only for slab-rate incomes in case of FY 2024-25.
Present status for FY 2024-25
Since there has been no further amendment for this financial year, the situation for the FY 2023-24 prevails. Since there is a direction from the court, claim for the rebate for special-rate incomes shall definitely be allowed in the utility while filing returns. But the eligibility of the claim, and whether it will be finally allowed, depends on the actions by the department, decisions by the appellate authorities and courts. The present judgement may also be challenged in the apex court. Since there are comments by the court that it cannot be said that the section can be interpreted in the department’s view alone, and there is lack of clarity, we expect that it will be allowed. To conclude:
- Rebate shall not be allowed on LTCG u/s 112A.
- Shall be allowed to be claimed on all special-rate incomes. Final decision in uncertain.
- Shall be allowed on all slab-rate incomes.
Present status for FY 2025-26
Since the act has been amended for this financial year, there is no confusion.
- Rebate shall not be allowed on LTCG u/s 112A.
- Shall not be allowed on all special-rate incomes.
- Shall be allowed on all slab-rate incomes.
Notes:
- The calculation utilities may not be updated on the portal.
- LTCG for debt funds acquired on or after 01-04-2023 and sold in FY 2024-25, the tax is as per slabs. This will always be allowed. See row 3.
- LTCG for debt funds acquired before 01-04-2023 and sold in FY 2024-25, the tax rate is 12.5%. This is special-rate and is expected to be allowed in FY 2024-25. See row 4.