It is the dream and responsibility of every parent to guarantee that our children have the freedom and ability to pursue their desired path in life. Additionally, it would be ideal for our children to begin their professional journey without the burden of an educational loan.
So it is vital that we strategically plan and invest in our child’s future. A straightforward calculation is presented here to assist you in this endeavour. Make it a priority to discuss this with your partner this weekend and accomplish this task!
One may ask which is more important—planning for a secure retirement or our children’s future. Emotionally this is an easy question to answer: Our children come first! See: Why our children’s education is more important than our retirement planning.
Especially if we become young parents and can work for at least a decade after they start school; however, both goals become equally important since couples are becoming parents in their early and mid-30s with tough corporate jobs. We will never take them seriously unless we sit and calculate how much investment will be made. That is why it is crucial to do this exercise as a couple.
What is presented is only a simple illustration. A more sophisticated, accurate and automated calculation is available in our robo-advisory tool for other goals, such as retirement.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Step 1: Project current and current class (in school) into the future
Set up the following columns in any spreadsheet software of your choice. It will tell you when exactly you need the money for college. Or how many years you have to invest. Here it is for nine years
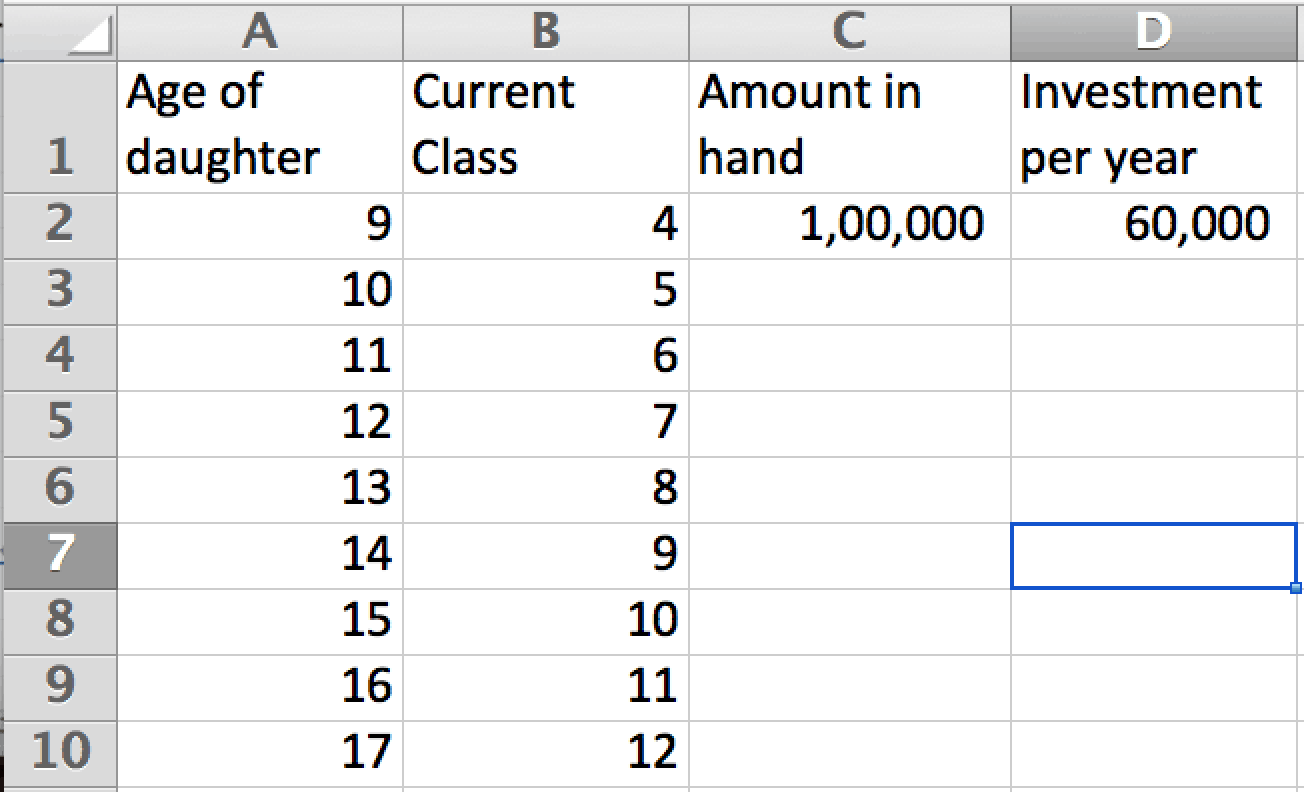
We also add the money available at hand, say Rs. one lakh in previous investments. We also assume you can invest Rs. 5000 a month or Rs. 60,000 a year. Here are assuming the girl will enter class four this coming academic year.
Step 2: Growth of the amount in hand
We assume that the Rs. One lakh in hand grows at about 7% post-tax a year, resulting in about 1.8 lacks after nine years.

Step 3: Growth of future investment amount
This step is crucial. Please increase the investment amount by at least 10% a year!

Step 4: Computing the value of monthly investments
To do this, we first need to know how much to invest in equity and how to invest in fixed income. We need an asset allocation. Alternatively, we can enter a yearly portfolio return, as shown below.
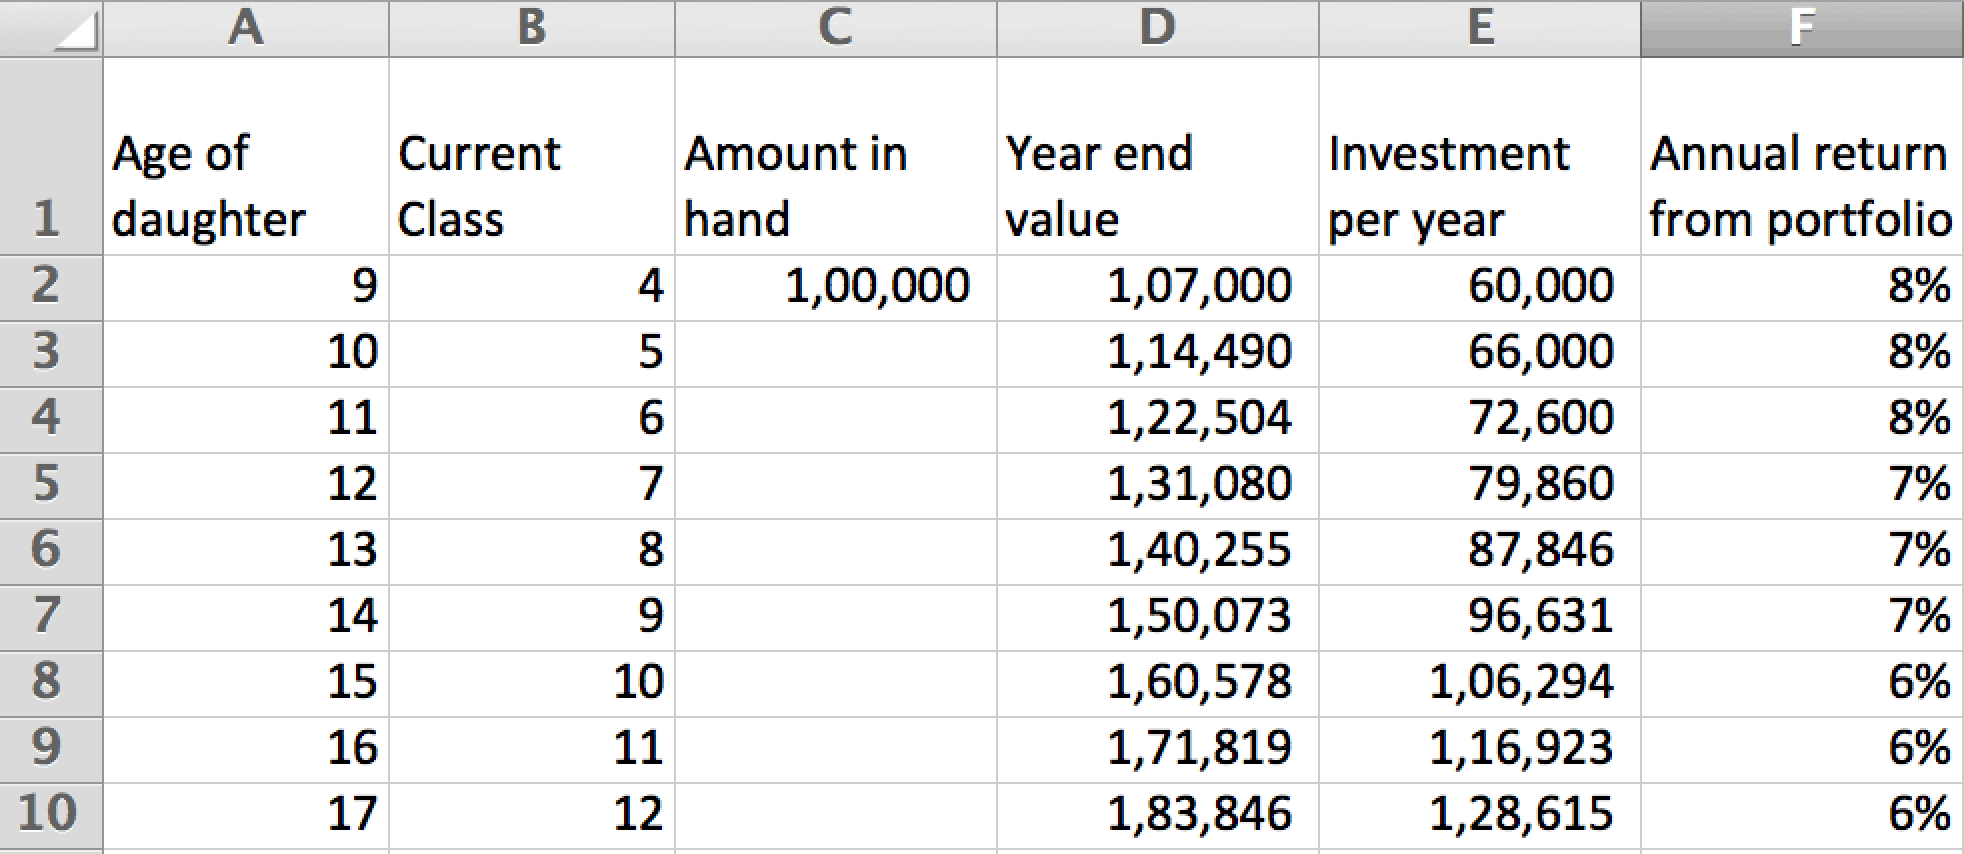
This corresponds to about 40% equity initially and 60% fixed income for the first three years, reduced to 20% in the middle three years and 0% in the last three years. This process (among others) is automated in our robo-advisory tool.
Where to invest this? I have made product suggestions in the video version linked below.
Step 5: Finding the final investment amount
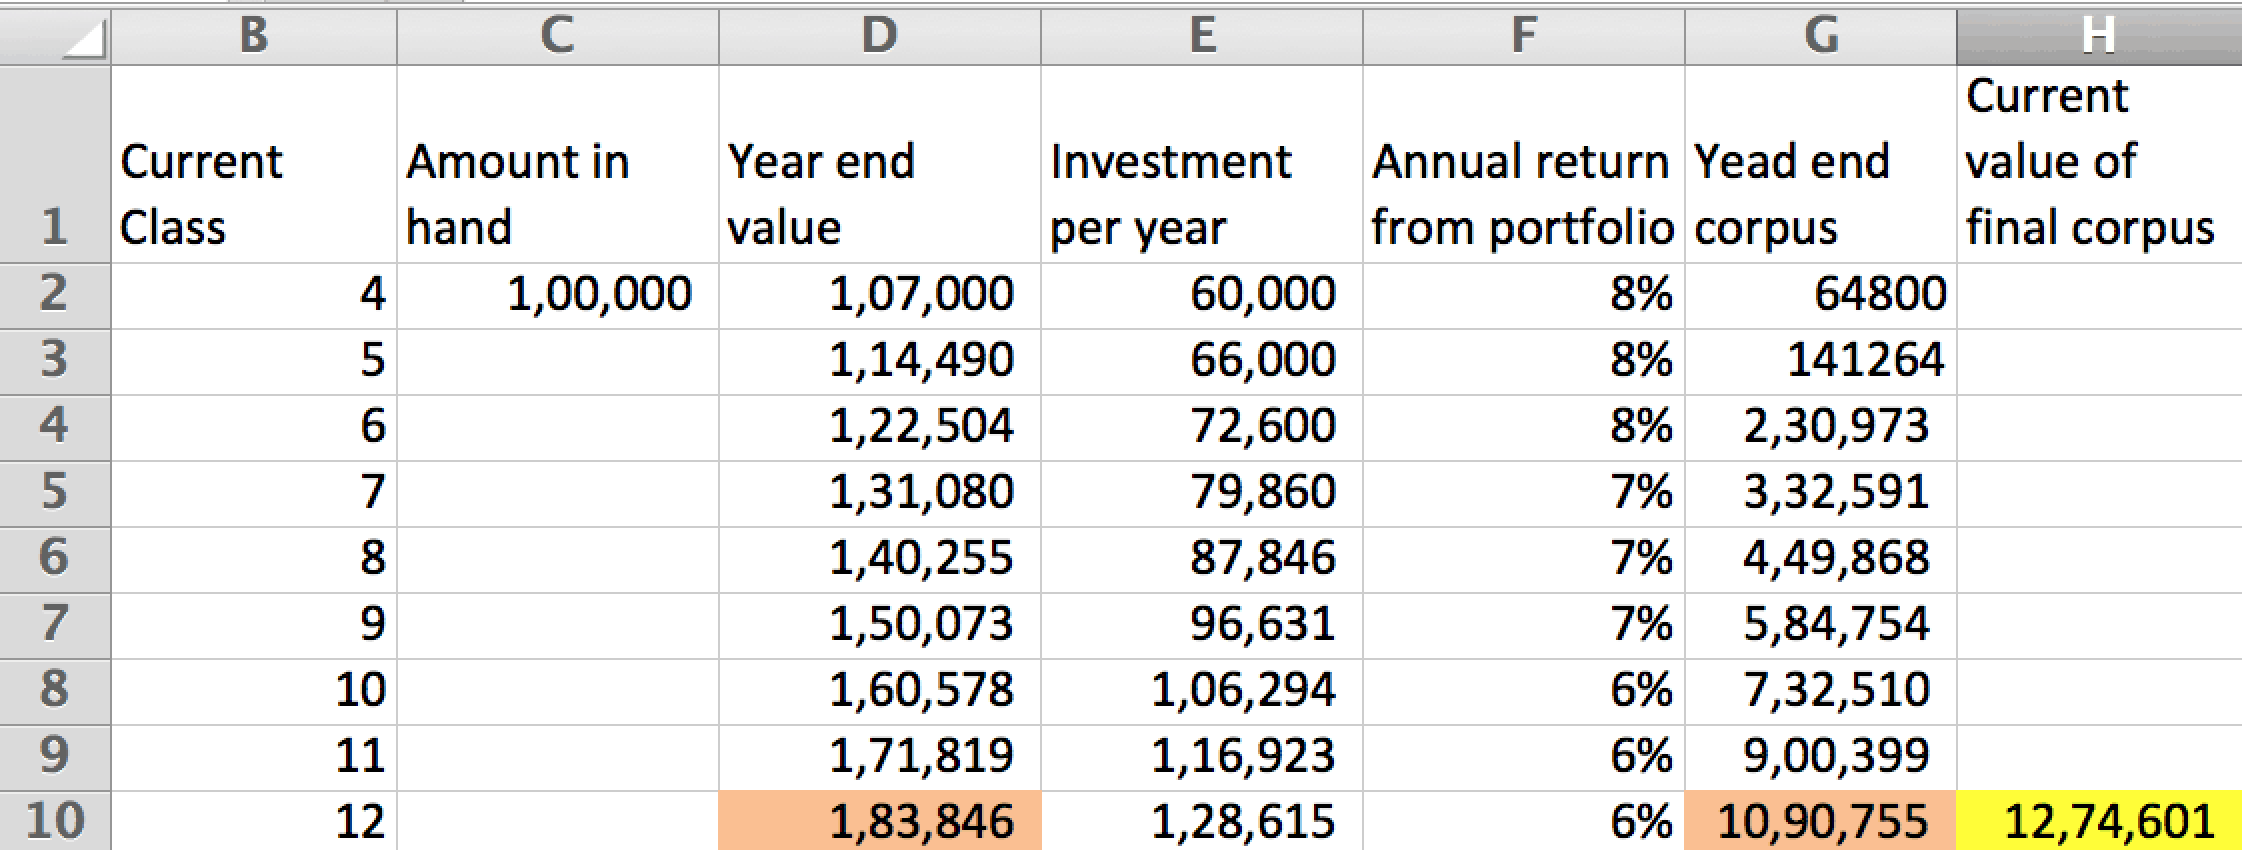
In column G, we compute how the investments made each year grows with the corresponding annual return in column F. In column H, the total final value is shown. The yellow cell is the sum of two orange cells. See the video version if you want some help in computing column G.
Step 6: Finding what the projected corpus is worth today
Now we take the value in the yellow cell and devalue it by 10% (assuming inflation in education expenses) year after year to find the current value of the projected corpus. To ensure I do it for nine years, the cell in blue is devalued twice to get the current value.
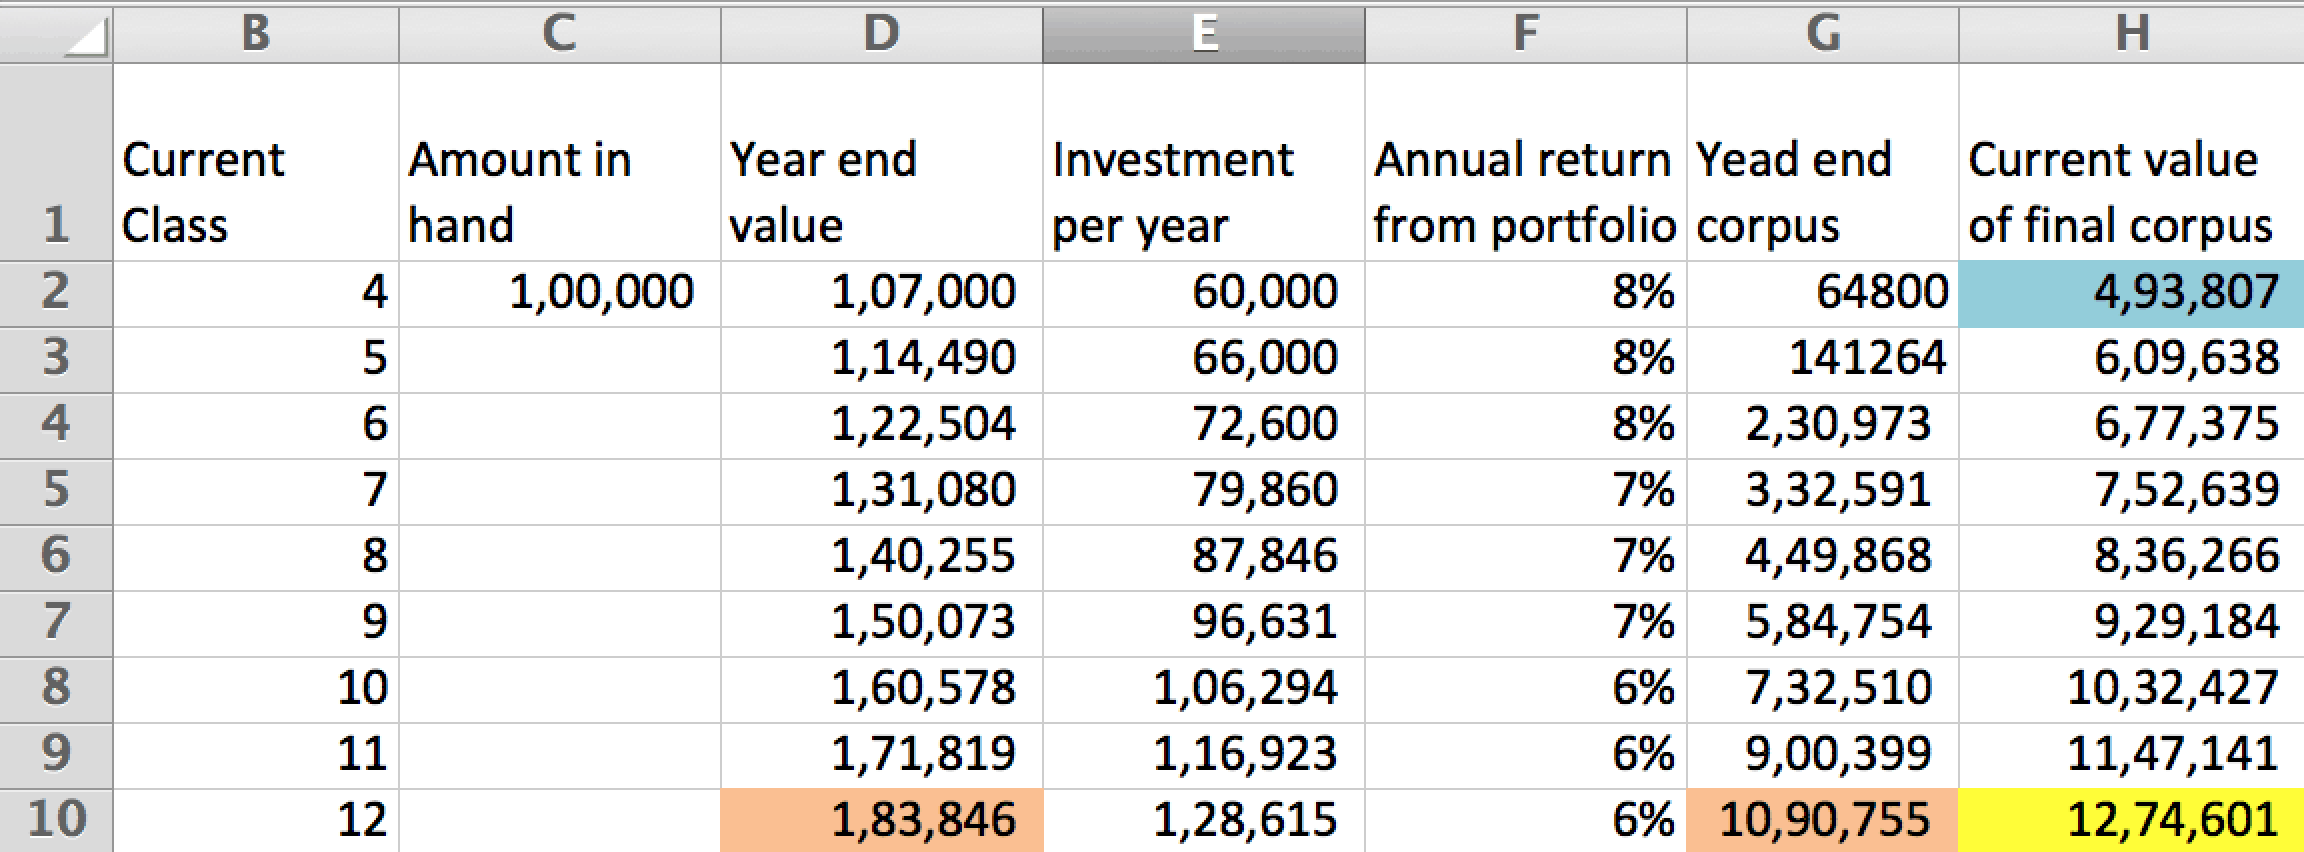
So this means our future investments are worth about five lakhs today. If this amount is at least 70-80% of a college education today, the child will probably not need an educational loan.
The advantage of the above calculation is flexibility and a better understanding of what is going on and what has to be done.
Step 7: Choosing the investment products (watch the video version)
Step 8: Projections for a newborn (< 1-year-old) conservative
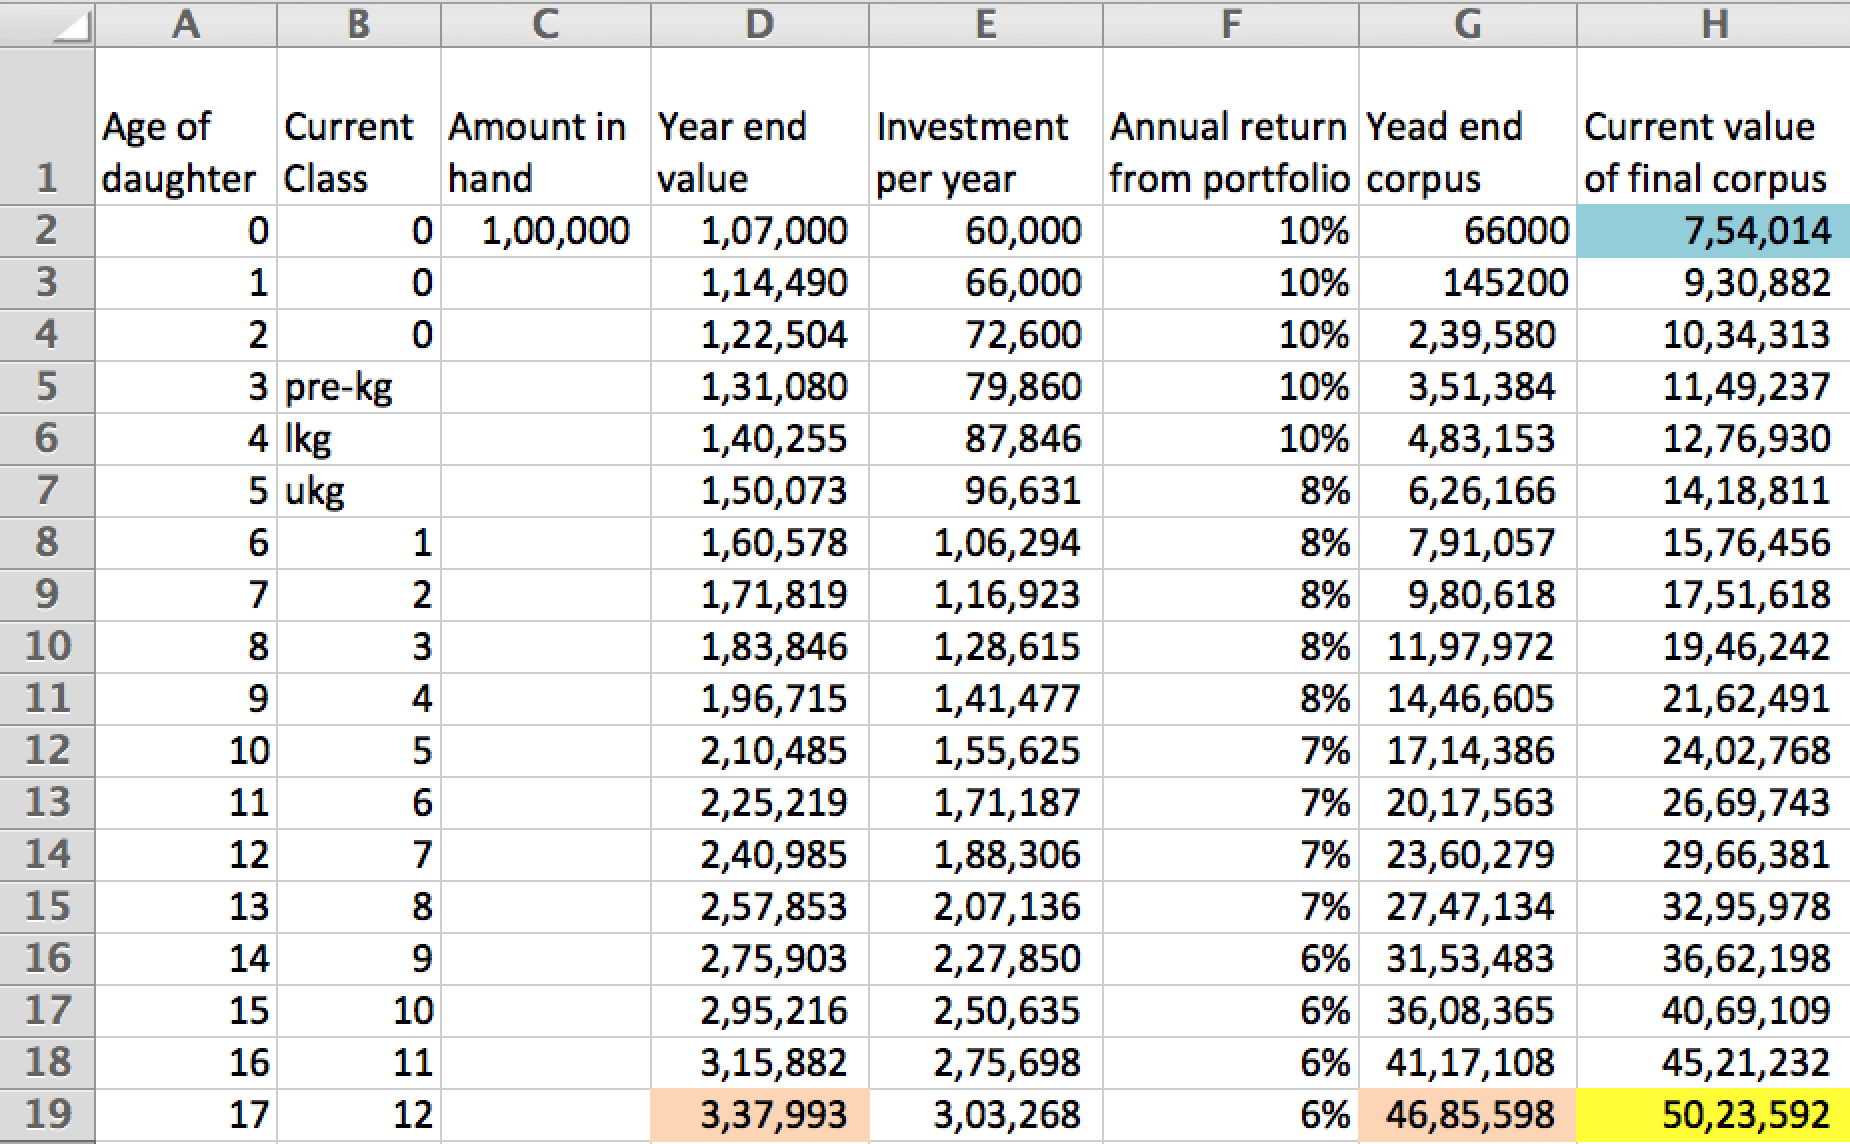
I have made two projections for a newborn with a full 17-18 years of time for investment. Even with a conservative return projection, the corpus is decent.
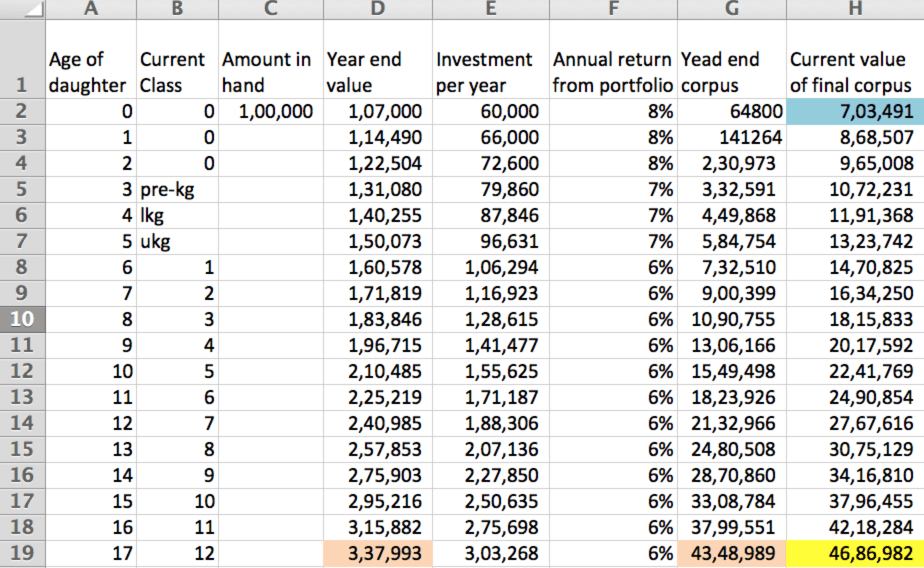
Step 9: Projections for a newborn (<1-year-old) aggressive
This is the same as above with a more aggressive return expectation (higher equity)
Weekend exercise
- Please do these steps with your spouse and let me know if it was useful
- What kind of asset allocation would you use for steps 8 and 9? Hint: How to reduce risk in an investment portfolio