FIRE, an acronym for ‘Financial Independence Retire Early,’ refers to achieving early retirement. In India, the conventional retirement age is typically 60. However, if you aspire to retire significantly earlier than this standard age, around 40 or 45, it is referred to as FIRE.
About the author: Ajay Pruthi is a fee-only SEBI registered investment advisor. He can be contacted via his website plnr.in.
Attaining FIRE may present challenges, but understanding the key principles can help in its achievement:
- Start investing from a young age.
- Invest aggressively, allocate at least 50% of your income to investments.
- Continuously increase your investment every year.
- Regularly monitor your progress towards the goal.
Despite adopting these principles, there’s no guarantee of achieving FIRE due to the following factors:
- Limited time for investment and an extended period for managing expenses.
- Dependency on investment performance to meet the desired outcomes.
- The necessity for substantial career growth to sustain higher investments each year.
While pursuing FIRE, it is essential to remember that dedicating everything to tomorrow may require sacrificing the enjoyment of life in the present. It is important to balance investing for the future and living for the present.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Is there any other alternative to FIRE? Certainly, there is an alternative to FIRE, known as Semi-Retirement.
What is Semi-Retirement? Semi-Retirement is a transitional phase between full-time employment and complete retirement. It involves reducing work hours or responsibilities, allowing individuals to balance work and leisure while still earning an income.
Now, let’s understand the fundamental differences between FIRE and Semi-Retirement:
- FIRE: In the case of FIRE, individuals choose to stop working entirely and rely on their retirement corpus to sustain themselves for the rest of their lives.
- Semi-Retirement: Individuals stop investing at semi-retirement age but can still manage their monthly household expenses until they reach their desired retirement age. During this phase, their retirement corpus continues to grow while they maintain their standard of living.
The first point regarding FIRE is straightforward and requires no further explanation.
Regarding the second point, Semi-Retirement may occur 10-15 years before actual retirement. Several scenarios may lead to Semi-Retirement without full retirement:
- Passive Income Source: Individuals might have a passive source of income, such as pursuing a passion project that generates earnings, or they may have a more relaxed job that covers their monthly expenses.
- Working Spouse: If the individual’s spouse is also employed and plans to continue working for the next 10-15 years, the household’s monthly expenses can be managed from the spouse`s salary.
Let me provide an example to illustrate the difference in the required investment amount between choosing FIRE and Semi-Retirement.
Option 1 – FIRE
Let’s consider the scenario of Ajay, a 30-year-old individual aiming to retire by the age of 45. He is married and the sole earner in his family. Ajay’s current monthly expenses amount to 30,000, and he wishes to maintain the same standard of living throughout his retired life. With a life expectancy of 85 years and his wife being three years younger, the retirement duration would be 43 years (85 – 45 – 3).
Assuming an inflation rate of 6%, the value of 30,000 after 15 years (at Ajay’s retirement) would be 72,000 per month. This inflation-adjusted amount of 72,000 per month is required for the subsequent 43 years.
To generate this monthly income of 72,000, Ajay would need a corpus of approximately 3 Crores.
Now, let’s calculate the investment required to achieve this corpus within 15 years, assuming a 9% return on investments. Since there is limited time available, Ajay may not be able to invest the entire amount in equities.
Therefore, Ajay would need to invest around 82,000 per month to attain this corpus in 15 years, assuming returns of 9% from a mix of equity and debt investments
By investing 82,000 monthly, Ajay can work towards achieving his desired corpus and ultimately attain financial independence for his retirement.
Option 2 – Semi-Retirement and Actual Retirement
Let’s consider the scenario where Ajay’s wife is also working. Ajay plans to semi-retire by age 45 but his wife is planning to work for another 15 years. If she can manage the household expenses from age 45 to 60 (assuming 60 is Ajay`s actual retirement age), the following are the calculations for the required corpus and investment:
Considering 6% inflation, the value of 30,000 after 30 years (at Ajay’s retirement) would be 1.7 Lakhs per month. This inflation-adjusted amount of 1.7 Lakhs would be needed for the subsequent 28 years.
Thus, the retirement corpus required to generate this monthly income of 1.7 Lakhs would be approximately 5 Crores.
Now, let’s calculate the investment required to achieve this corpus within 15 years Ajay can only invest until age 45, which gives him 15 years.
- Corpus required at age 60 – 5 Crores
- Amount required to achieve a corpus of 5 Crores at age 45 (assuming a Compound Annual Growth Rate – CAGR of 9%) – 1.40 Crores, i.e., 1.90 Crores will grow to 5 Crores in 15 years, assuming 9% returns.
Hence, Ajay will require a corpus of 1.40 Crores at age 45.
To achieve this corpus in 15 years, Ajay will need to invest around 38,000 per month, assuming returns of 9% from a mix of equity and debt investments
Opting for Semi-Retirement would make a difference of 44,000 in the required monthly investment.
These calculations do not consider other financial goals, and individuals may need to make additional investments for those. Moreover, the investment and corpus required will vary from person to person based on their unique circumstances.
Conclusion
You can choose between planning for FIRE or Semi-Retirement according to your preferences. However, a complete retirement at 45 may prove challenging without any meaningful activities. You may enjoy it for a few months but then may realize that it wasn’t worth the effort without any work. So, start developing a passion, a business, a source of income that will keep you busy and happy and will help your money to grow till the time you are fully retired.
Till Then, Happy Investing!
We are on Google News
Use this button to add freefincal.com as a preferred personal finance source on Google News. 
Add freefincal as a preferred news source
You can also follow freefincal on Google News. 
Explore 1,000+ videos on YouTube!
Subscribe to get posts via email!
Join 32,000+ readers and get free money management solutions delivered to your inbox! (Link takes you to our email sign-up form)Join our WhatsApp Channel
Explore our products
🔥Join our community of 9000+ users! 🔥 Use our Robo-advisory Tool to create a complete financial plan! More than 3,500 investors and advisors use this! Use the discount code robo25 for 20% off. Plan your retirement (early, normal, before, and after), plus non-recurring financial goals (such as child education) and recurring financial goals (such as holidays and appliance purchases). The tool helps anyone aged 18 to 80 plan for retirement, plus six non-recurring and four recurring financial goals, with a detailed cash flow summary. Our Flagship Course! Learn to manage your portfolio like a pro to achieve your goals regardless of market conditions! More than 3,500 investors and advisors are part of our exclusive community! Get clarity on how to plan for your goals and achieve the necessary corpus no matter the market conditions! Watch the first lecture for free! One-time payment! No recurring fees! Lifelong access to videos! Reduce fear, uncertainty and doubt while investing! Learn how to plan for your goals before and after retirement with confidence. Join the freefincal investor circle! An exclusive space for investors, advisors, fintech employees and students to access financial planning and insurance tools, mutual fund and stock analysis tools, coding strategies and Excel macros for data extraction. 750+ members are now part of our investor circle. Increase your income by getting people to pay for your skills! More than 900 salaried employees, entrepreneurs and financial advisors are part of our exclusive community! Learn how to get people to pay for your skills! Whether you are a professional or small business owner seeking more clients through online visibility, or a salaried individual looking for side or passive income, we will show you how to do it by showcasing your skills and building a community that trusts and pays you. (Watch the 1st lecture for free). One-time payment! No recurring fees! Lifelong access to videos! Track your mutual funds and stock investments with our Google Sheet! We also publish monthly screeners for- Equity mutual funds
- Debt and hybrid mutual funds
- Index funds
- ETFs
- Momentum and low-volatility stock screeners
Our Podcast: Let's Get Rich With Pattu
On Spotify: Let's Get RICH With PATTU! Every single Indian CAN grow their wealth!
Audible Link: Listen to the Let's Get Rich with Pattu Podcast
You can also watch podcast episodes on the OfSpin Media Friends YouTube Channel
Listen to the Let's Get Rich With Pattu podcast on YouTube.
Now watch Let's Get Rich With Pattu தமிழில் (in Tamil)!About The Author
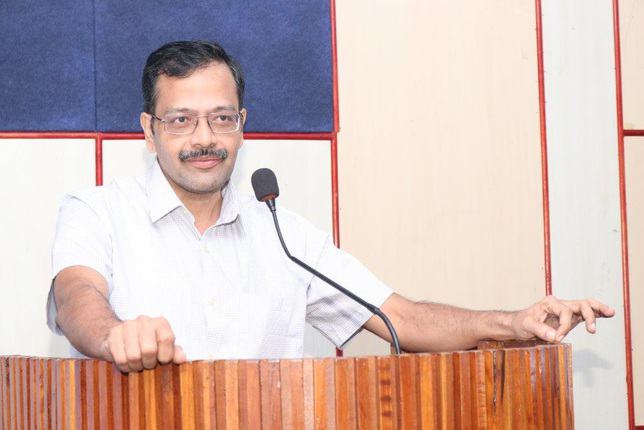
Dr M Pattabiraman giving a lecture
Dr M. Pattabiraman (PhD) is the founder, managing editor and primary author of freefincal. He is an associate professor at the Indian Institute of Technology, Madras. He has over 14 years of experience publishing news analysis, research and financial product development. He is a patron and co-founder of “Fee-only India,” an organisation promoting unbiased, commission-free, AUM-independent investment advice. Connect with him via Twitter(X) LinkedIn YouTube Pattabiraman has co-authored three print books: (1) You can be rich too with goal-based investing (Published by CNBC TV18) for DIY investors. 
This book helps you ask the right questions and find the right answers. It also includes nine online calculators to create custom solutions.
(2) Gamechanger: Forget Startups, Join Corporate & Still Live the Rich Life You Want. 
Both the boy and girl versions of "Chinchu Gets a Superpower".
Most investor problems stem from a lack of poor decision-making. We made bad decisions and money mistakes when we started earning, and we spent years undoing them. Why should our children go through the same pain? What is this book about? As parents, what if we had to groom one ability in our children that matters not only for money management and investing but for every aspect of life? My answer: Sound decision-making. So, in this book, we meet Chinchu, who is about to turn 10. The story follows what he wants for his birthday and how his parents plan it, while also teaching him key ideas about decision-making and money management. What readers say! 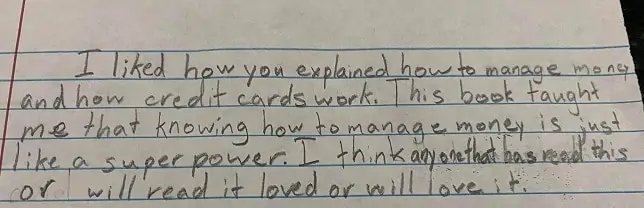
Feedback from a young reader after reading Chinchu Gets a Superpower!
Must-read book even for adults! This is something that every parent should teach their kids right from a young age. The importance of money management and decision-making based on their wants and needs. Very nicely written in simple terms. - Arun.
About freefincal & its content policy
Freefincal is a News Media organisation dedicated to providing original analysis, reports, reviews and insights on mutual funds, stocks, investing, retirement and personal finance developments. We do so without conflict of interest and bias. Follow us on Google News. Freefincal serves more than three million readers a year (5 million page views) with articles based only on factual information and detailed analysis by its authors. All statements made will be verified with credible and knowledgeable sources before publication. Freefincal does not publish paid articles, promotions, PR, satire or opinions without data. All opinions will be inferences backed by verifiable, reproducible evidence/data. Contact Information: To get in touch, please use our contact form. (Sponsored posts or paid collaborations will not be entertained.)Our publications
Your Ultimate Guide to Travel