Over the past few months, I’ve found myself asking AI more and more financial questions. Sometimes I already knew the answer. Other times I simply wanted to see how it reasoned.
Can it calculate a retirement corpus? Compare the old and new tax regimes? Explain sequence of returns risk? Build an asset allocation? Review an insurance portfolio?
The answer surprised me. It can do all of these well.
Which naturally leads to a bigger question. If AI can already perform many of the technical tasks involved in financial planning, do we still need human financial planners?
I don’t think the answer is a straightforward yes or no. The real question is much deeper.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
About the author: Sneha Rege writes about money, behaviour, and the friction between the two. A corporate professional herself, based in Bengaluru, she focuses on the urban Indian salaried professional: someone who does most things right and still wonders if it will be enough. She is currently also working towards her SEBI RIA credentials. You can find her work at sneharege.com.
Is financial planning primarily a knowledge problem, or is it a decision-making problem?
Let’s test AI with one Indian family.
Rather than argue in theory, let’s give AI a real client.
Manoj is thirty-nine. His wife Priya is thirty-six. They both work in Bengaluru and earn about ₹45 lakh a year together. They have one child, a home loan, ageing parents, EPF, NPS, company ESOPs, six mutual funds accumulated over the years and a retirement goal somewhere around age fifty-five. But lately, they’ve started wondering if forty-five is possible.
Like most middle-class families, they aren’t looking for extraordinary returns. They simply want confidence that they are making sensible decisions.
They upload every financial detail into AI and ask one question.
“Can we retire early at forty-five?”
Within seconds, AI produces a surprisingly comprehensive plan. It estimates their retirement corpus, recommends an emergency fund, identifies overlapping mutual funds, reviews insurance needs, compares tax options and even highlights gaps in estate planning.
Objectively, it is a good plan.
In fact, it may already be better than what some people receive after sitting through two meetings with someone trying to sell them financial products.
That should make every financial planner slightly uncomfortable.
Because the knowledge advantage has almost disappeared.
AI is already exceptionally good at certain parts of financial planning.
Let’s acknowledge some facts first.
AI doesn’t forget tax rules. It doesn’t become tired after five client meetings asking the same question again and again. It can read lengthy regulations in minutes, compare hundreds of financial products almost instantly and generate multiple retirement scenarios before most of us have finished opening Excel.
It is also infinitely patient. You can ask the same question five different ways without worrying that you’re wasting anyone’s time.
For a motivated DIY investor, this changes everything. Information that once required expensive software, specialist books or multiple consultations is now available to almost anyone with an internet connection.
That is a shift, and I think we should celebrate it rather than pretend it isn’t happening.
The harder part is the conversation
Now imagine someone asks Manoj why he wants to retire at forty-five.
He replies, “I’m exhausted.”
A retirement calculator interprets that as a financial goal.
A thoughtful planner hears something else entirely.
Maybe Manoj doesn’t actually want to retire. Maybe he wants to leave a toxic workplace. Maybe he wants to work fewer hours, move closer to family or change careers altogether.
Those possibilities require completely different financial plans.
The mathematics hasn’t changed.
The conversation has.
Good financial planning has never been only about calculating the right answer. Often, it begins by discovering that the client is trying to solve the wrong problem.
Families don’t behave like spreadsheets.
Money decisions are rarely made by one person in isolation, especially in Indian households.
Manoj wants to retire early. Priya wants financial security before making that decision. His parents hope he won’t move away from their hometown. Their daughter dreams of studying medicine.
None of these priorities is irrational. They simply compete with each other.
AI can optimise numbers beautifully once the objective is clear. It struggles when the objective itself is still being negotiated.
Many financial decisions are primarily difficult conversations between people, not calculations inside a spreadsheet.
Most people don’t misunderstand money. They misunderstand themselves.
One thing I’ve realised after spending years reading about behavioural finance is that people rarely make poor financial decisions because they lack information.
More often, they misunderstand themselves.
Someone says they have a high risk appetite until the market falls twenty-five percent.
Someone insists they don’t care about social status before stretching their finances to buy a larger home because everyone around them upgraded.
Someone claims they can manage investments themselves but hasn’t reviewed their portfolio in three years.
None of these people are dishonest. They are not making excuses. That is just how people work.
The difficult part of financial planning isn’t knowing the right answer. It’s recognising when your own emotions are quietly changing the question.
So what exactly does a human planner contribute?
Not superior calculations.
AI may already outperform most planners on that front.
The value lies somewhere else.
A good planner notices hesitation when a couple discusses retirement. They recognise contradictions between what clients say and what they actually do. They ask uncomfortable questions that never appear inside a questionnaire. Sometimes they simply tell a client to wait a week before making an irreversible decision.
In short a good advisor can guide and help to manage the behavioral aspect, the part that cannot be charted in 10,000 Monte Carlo simulations.
Those interventions rarely show up in performance reports. Yet they may be the moments that matter most.
The trade-off you’re really making.
People often frame this debate as AI versus human advice.
I don’t think that’s the right comparison.
The real choice is deciding which risks you are willing to accept.
If you rely primarily on AI, you gain speed, affordability, unlimited access and good technical knowledge. The trade-off is that nobody truly knows your family, your behaviour or your blind spots. Recognising those remains entirely your responsibility.
If you work with a human planner/advisor, you gain judgement, accountability and another person whose job is to challenge your thinking. The trade-off is cost, variable quality and the reality that not every planner deserves your trust.
Neither choice is risk-free. They simply expose you to different risks.
What I actually use AI for
If I wanted to understand taxation, compare investment products, estimate retirement corpus, stress-test assumptions, build an Investment Policy Statement or simply learn, AI would probably be my first stop.
For disciplined DIY investors with relatively straightforward finances, AI is already a decent planning companion.
Used well, it can improve the quality of your financial decisions.
Where I’d still want a human in the room
If I were deciding whether to retire five years early, handling a large inheritance, selling a business, navigating a divorce or planning for parents with declining health, I would still want another thoughtful human involved.
Not because AI is incapable.
Because decisions like these are rarely about information alone.
They involve values, uncertainty, family dynamics and trade-offs that no prompt can fully capture.
Sometimes the most valuable question isn’t, “What should I do?”
It’s, “Have I thought about this correctly?”
That is often easier to explore in conversation than through a screen.
Where this is likely heading
It’s AI and human.
I can imagine a future where AI prepares the first draft of every financial plan. It performs the calculations, identifies gaps, checks regulations, summarises tax implications and monitors portfolios continuously.
The planner’s role then changes.
Less time gathering information. More time understanding people.
Less time calculating. More time challenging assumptions.
Less time explaining products. More time helping families make difficult decisions.
Perhaps that’s where the profession is heading.
The biggest value of tomorrow’s financial planner may not be knowing more than AI.
It may simply be knowing you, your behaviour and your complicated life, the parts that cannot be summarised in a well-written prompt.
Back to Manoj.
AI gave him a solid retirement plan. Corpus calculated. Insurance gaps identified. Tax regime compared. But nobody had asked him why forty-five.
When someone finally asked, Manoj went quiet. Then said he was tired. Not financially tired. Just tired.
That changed everything. The real problem was not his retirement date. He had not taken a break in years, his workplace was draining him, and he had confused a work problem with a life decision.
AI gave him the right answer to the wrong question. And without that conversation, he would have acted on it.
A good advisor does not start with numbers. They start with questions that don’t have clean answers.
Why this goal, and why now? What happens to your plan if your income stops for a year? Have you and your spouse actually agreed on what retirement looks like day to day? Who depends on you that you haven’t mentioned yet? What would you regret more, retiring too early or too late?
No prompt captures the silence after that last question.
We are on Google News
Use this button to add freefincal.com as a preferred personal finance source on Google News. 
Add freefincal as a preferred news source
You can also follow freefincal on Google News. 
Explore 1,000+ videos on YouTube!
Subscribe to get posts via email!
Join 32,000+ readers and get free money management solutions delivered to your inbox! (Link takes you to our email sign-up form)Join our WhatsApp Channel
Explore our products
🔥Join our community of 9000+ users! 🔥 Use our Robo-advisory Tool to create a complete financial plan! More than 3,500 investors and advisors use this! Use the discount code robo25 for 20% off. Plan your retirement (early, normal, before, and after), plus non-recurring financial goals (such as child education) and recurring financial goals (such as holidays and appliance purchases). The tool helps anyone aged 18 to 80 plan for retirement, plus six non-recurring and four recurring financial goals, with a detailed cash flow summary. Our Flagship Course! Learn to manage your portfolio like a pro to achieve your goals regardless of market conditions! More than 3,500 investors and advisors are part of our exclusive community! Get clarity on how to plan for your goals and achieve the necessary corpus no matter the market conditions! Watch the first lecture for free! One-time payment! No recurring fees! Lifelong access to videos! Reduce fear, uncertainty and doubt while investing! Learn how to plan for your goals before and after retirement with confidence. Join the freefincal investor circle! An exclusive space for investors, advisors, fintech employees and students to access financial planning and insurance tools, mutual fund and stock analysis tools, coding strategies and Excel macros for data extraction. 750+ members are now part of our investor circle. Increase your income by getting people to pay for your skills! More than 900 salaried employees, entrepreneurs and financial advisors are part of our exclusive community! Learn how to get people to pay for your skills! Whether you are a professional or small business owner seeking more clients through online visibility, or a salaried individual looking for side or passive income, we will show you how to do it by showcasing your skills and building a community that trusts and pays you. (Watch the 1st lecture for free). One-time payment! No recurring fees! Lifelong access to videos! Track your mutual funds and stock investments with our Google Sheet! We also publish monthly screeners for- Equity mutual funds
- Debt and hybrid mutual funds
- Index funds
- ETFs
- Momentum and low-volatility stock screeners
Our Podcast: Let's Get Rich With Pattu
On Spotify: Let's Get RICH With PATTU! Every single Indian CAN grow their wealth!
Audible Link: Listen to the Let's Get Rich with Pattu Podcast
You can also watch podcast episodes on the OfSpin Media Friends YouTube Channel
Listen to the Let's Get Rich With Pattu podcast on YouTube.
Now watch Let's Get Rich With Pattu தமிழில் (in Tamil)!About The Author
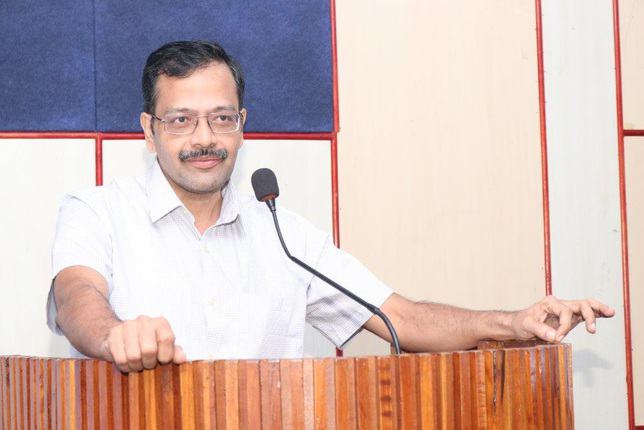
Dr M Pattabiraman giving a lecture
Dr M. Pattabiraman (PhD) is the founder, managing editor and primary author of freefincal. He is an associate professor at the Indian Institute of Technology, Madras. He has over 14 years of experience publishing news analysis, research and financial product development. He is a patron and co-founder of “Fee-only India,” an organisation promoting unbiased, commission-free, AUM-independent investment advice. Connect with him via Twitter(X) LinkedIn YouTube Pattabiraman has co-authored three print books: (1) You can be rich too with goal-based investing (Published by CNBC TV18) for DIY investors. 
This book helps you ask the right questions and find the right answers. It also includes nine online calculators to create custom solutions.
(2) Gamechanger: Forget Startups, Join Corporate & Still Live the Rich Life You Want. 
Both the boy and girl versions of "Chinchu Gets a Superpower".
Most investor problems stem from a lack of poor decision-making. We made bad decisions and money mistakes when we started earning, and we spent years undoing them. Why should our children go through the same pain? What is this book about? As parents, what if we had to groom one ability in our children that matters not only for money management and investing but for every aspect of life? My answer: Sound decision-making. So, in this book, we meet Chinchu, who is about to turn 10. The story follows what he wants for his birthday and how his parents plan it, while also teaching him key ideas about decision-making and money management. What readers say! 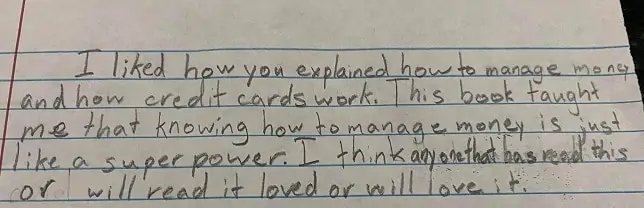
Feedback from a young reader after reading Chinchu Gets a Superpower!
Must-read book even for adults! This is something that every parent should teach their kids right from a young age. The importance of money management and decision-making based on their wants and needs. Very nicely written in simple terms. - Arun.
About freefincal & its content policy
Freefincal is a News Media organisation dedicated to providing original analysis, reports, reviews and insights on mutual funds, stocks, investing, retirement and personal finance developments. We do so without conflict of interest and bias. Follow us on Google News. Freefincal serves more than three million readers a year (5 million page views) with articles based only on factual information and detailed analysis by its authors. All statements made will be verified with credible and knowledgeable sources before publication. Freefincal does not publish paid articles, promotions, PR, satire or opinions without data. All opinions will be inferences backed by verifiable, reproducible evidence/data. Contact Information: To get in touch, please use our contact form. (Sponsored posts or paid collaborations will not be entertained.)Our publications
Your Ultimate Guide to Travel