Note: This retirement planning illustration depends on several inputs and assumptions. Not all of them are shown here. The individual must change these inputs and assumptions according to their circumstances. Please do not use these illustrations as a framework or copy these numbers for personal use without a proper calculation.
- Assumed life expectancy of younger spouse 90 (I have assumed both are 47 for this illustration)
- Inflation during retirement (%) 6
- Years to retirement 0
- Monthly expenses in the first year of retirement: Rs 2,00,000
- Years in retirement (until younger spouse reaches age 90) 43
- Corpus available: Rs. 5.7 Crores
Results:
- Corpus necessary to provide inflation-protected income for the first 15Y in retirement: Rs. 4,21,52,673 This amount includes an emergency corpus for about 36.5 Lakhs
- Corpus necessary to provide inflation-protected income after the first 15Y in retirement to the remainder of your lifetime Rs. 3,45,12,765
- The total corpus required, therefore, is Rs. 7.66 Crores
- The shortfall is 1.96 Crores.
Verdict: You are not ready to retire even if you account for your emi and daughter’s education with separate funds.
Why do you need Rs. 7.66 crores?! The freefincal robo advisor ensures the retiree’s corpus does not get eroded too soon because of a poor sequence of returns. This is why it ensures that the first 15 years of retirement are guaranteed with a near-zero risk investment from which an inflation-indexed income can be drawn.
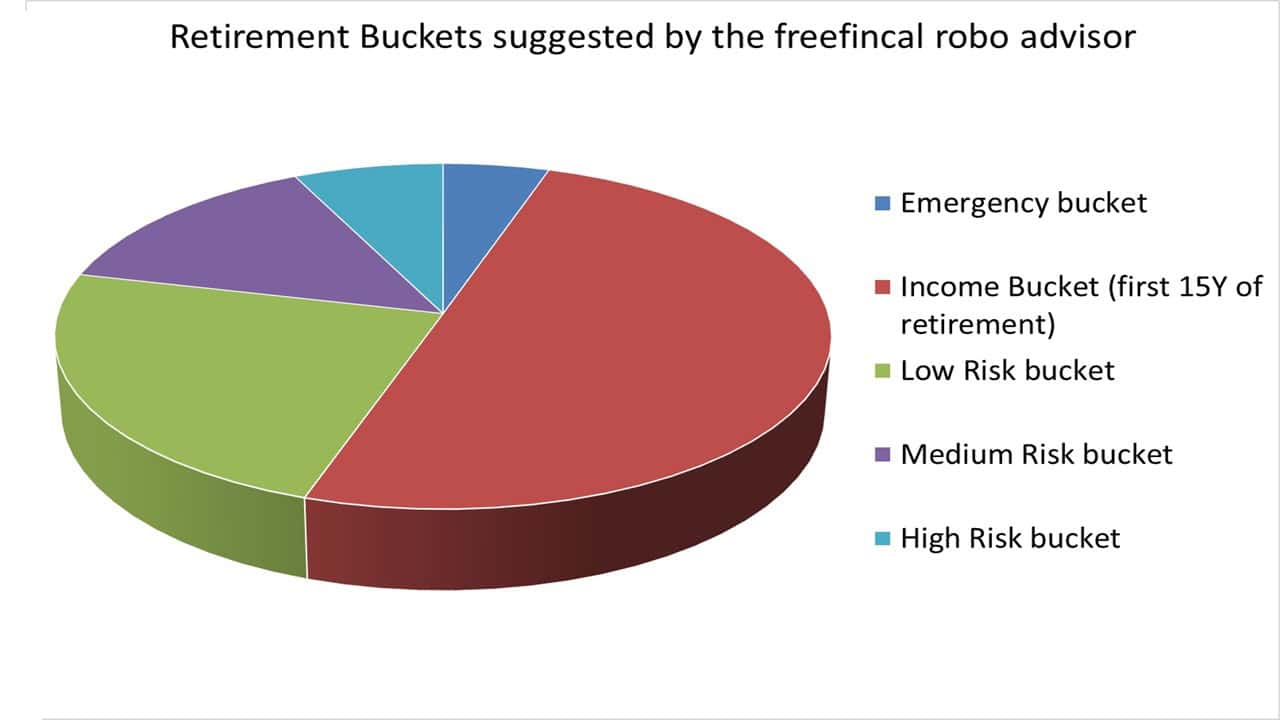
- This income bucket requires Rs. 4,21,52,673. This amount includes an emergency corpus of about 36.5 Lakhs.
- The overall equity allocation for the rest of the corpus is only 30%. We do not go overboard on equity just because the retiree is young. The remaining corpus is invested in the following manner.
- A low-risk bucket with 25% of the remaining corpus for income from year 16 to year 26 in retirement. The low-risk bucket will have an asset allocation of 50% equity and 50% debt during the investment period (years 1 to 15 of retirement).
- Corpus from a medium risk bucket with 15% of the remaining corpus will provide income from years 27 to 35 in retirement. This bucket shall have an asset allocation of 70% equity and 30% debt during the investment period (year 1 to year 26)
- Corpus from a high-risk bucket with 7% of the remaining corpus will provide income from years 36 to 43 in retirement. This bucket shall have an asset allocation of 100% equity during the investment period (year 1 to year 35)
- The buckets will be actively managed to reduce risk during this investment period via rebalancing and profit booking from one bucket to another. To understand how this works, try The Retirement Bucket Strategy Simulator.
- After 15 years, the low-risk bucket will be turned into 100% debt and provide income for about 10 years. After that, the other buckets will also be progressively used.
We realise that this is not the answer the reader wants to hear, but the ground reality is that it is too risky to retire early when expenses are high. We suggest postponing retirement until the home loan is paid off and the daughter is settled. Even then, having a secondary source of income from consulting and freelancing, etc., will be crucial.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈