Last Updated on July 9, 2025 at 7:40 pm
This is an updated capital gains taxation rules ready reckoner by tax expert Manmohan Sethumadhavan after taking into account the amendments to the Finance Bill 2025.
Update July 2025: The file was updated after an error was pointed out by a reader. Please download the updated file from below.
Only two changes were to capital gains taxation rules in Budget 2025 and these were covered by Manmohan earlier.
- Budget 2025: Changes in taxation of Alternative Investment Funds (AIFs)
- Budget 2025: Changes in taxation of Unit Linked Insurance Policies (ULIP)
In contrast budget 2024 had a slew of changes. This is a summary
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
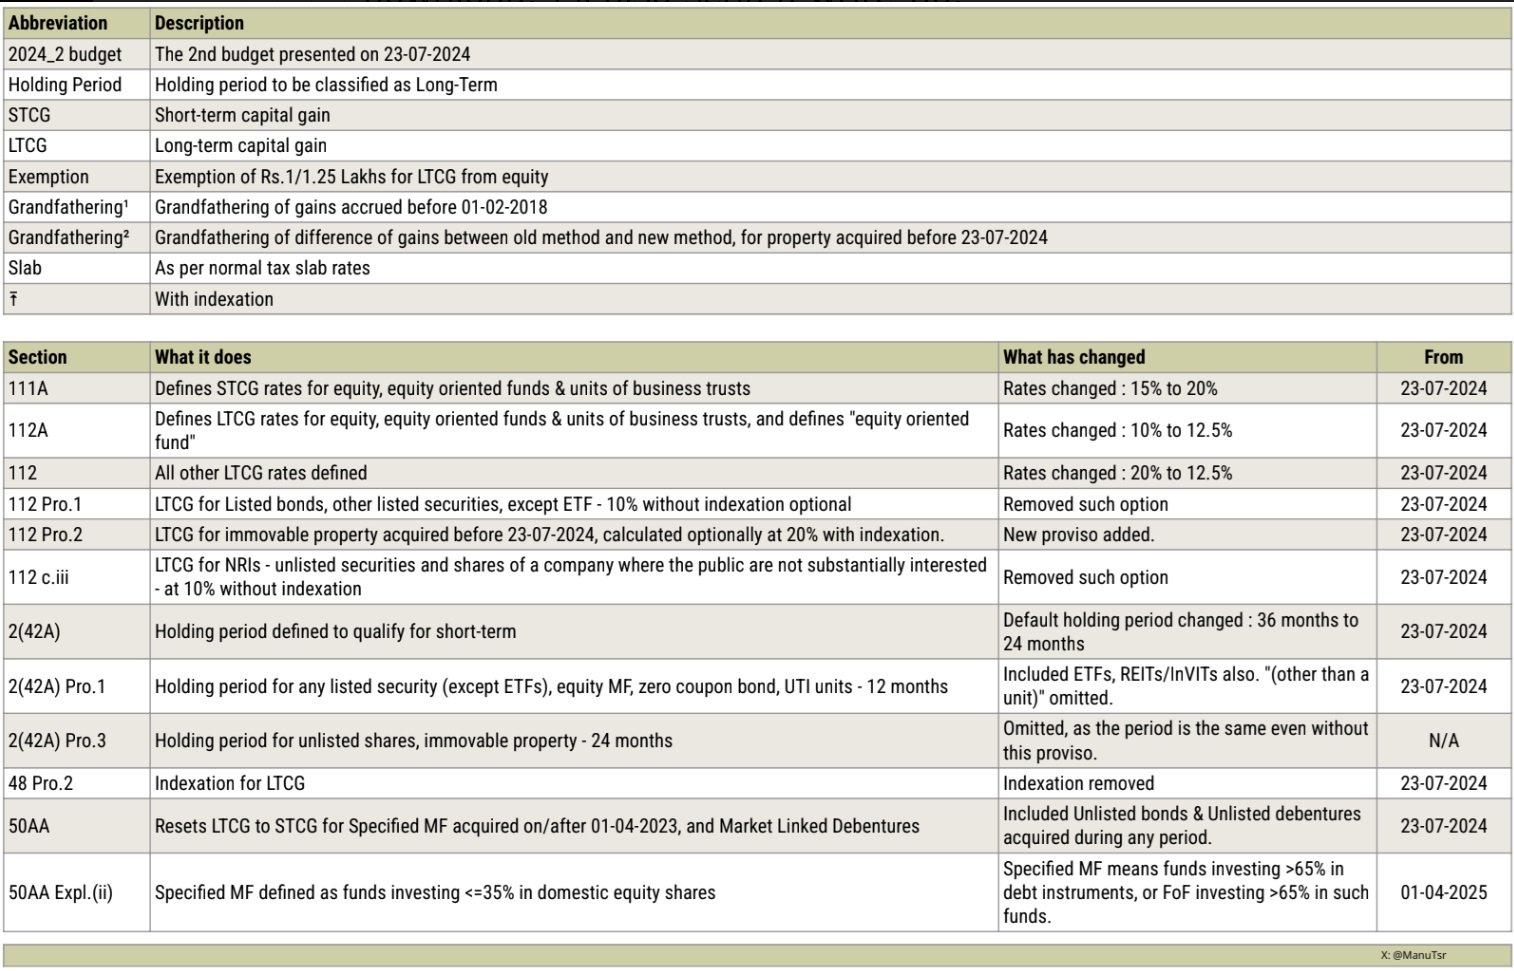
- The rate for equity instruments under section 111A (short-term) was changed
from 15% to 20%. - The rate for equity instruments under section 112A (long-term) was changed
10% to 12.5%. - The rate for all other long-term assets under section 112 was changed from 20%
to 12.5%. - LTCG for listed bonds and other listed securities except ETF under section 112
first proviso was optionally 10% without indexation; this was removed. - A new proviso was added to section 112 which allows to ignore the excess of
gains for LTCG from immovable property acquired before 23-07-2024, if
calculated at 20% with indexation as per the old rates. - LTCG for NRIs arising from sale of unlisted securities and private shares were
optionally at 10% without indexation; this was removed. - The default holding period under section 2(42A) for an asset to qualify as
long-term was changed from 3 years to 2 years. - The holding period for any listed security (except ETFs) and equity MFsto
qualify as long-term was 1 year. ETFs and REITs/InVITs also was included in it. - Indexation under section 48 was removed.
- Section 50AA resets any long-term gains to short-term for Specified MF
acquired on/after 01-04-2023, and Market Linked Debentures. Unlisted bonds &
Unlisted debentures acquired during any period, were added to this clause.
All these changes above are with effect from 23-07-2024, the budget day. - Under 50AA, Specified MF was defined as funds investing less than or equal to
35% in domestic equity shares. This was completely changed and the definition
for Specified MF is now fixed as funds investing more than 65% in debt
instruments or funds investing more than 65% in such funds.
This amendment above will take effect from 1st April, 2026 and will, accordingly,
apply in relation to the assessment year 2026-2027 (financial year 2025-26) and
subsequent years.
The ready reckoned is presented below as images. Click on them to zoom in. PDF download link is given below. Please note, these images are from version 1 of the file. The file was updated in July 2025. So please download the ready reckoner from below.
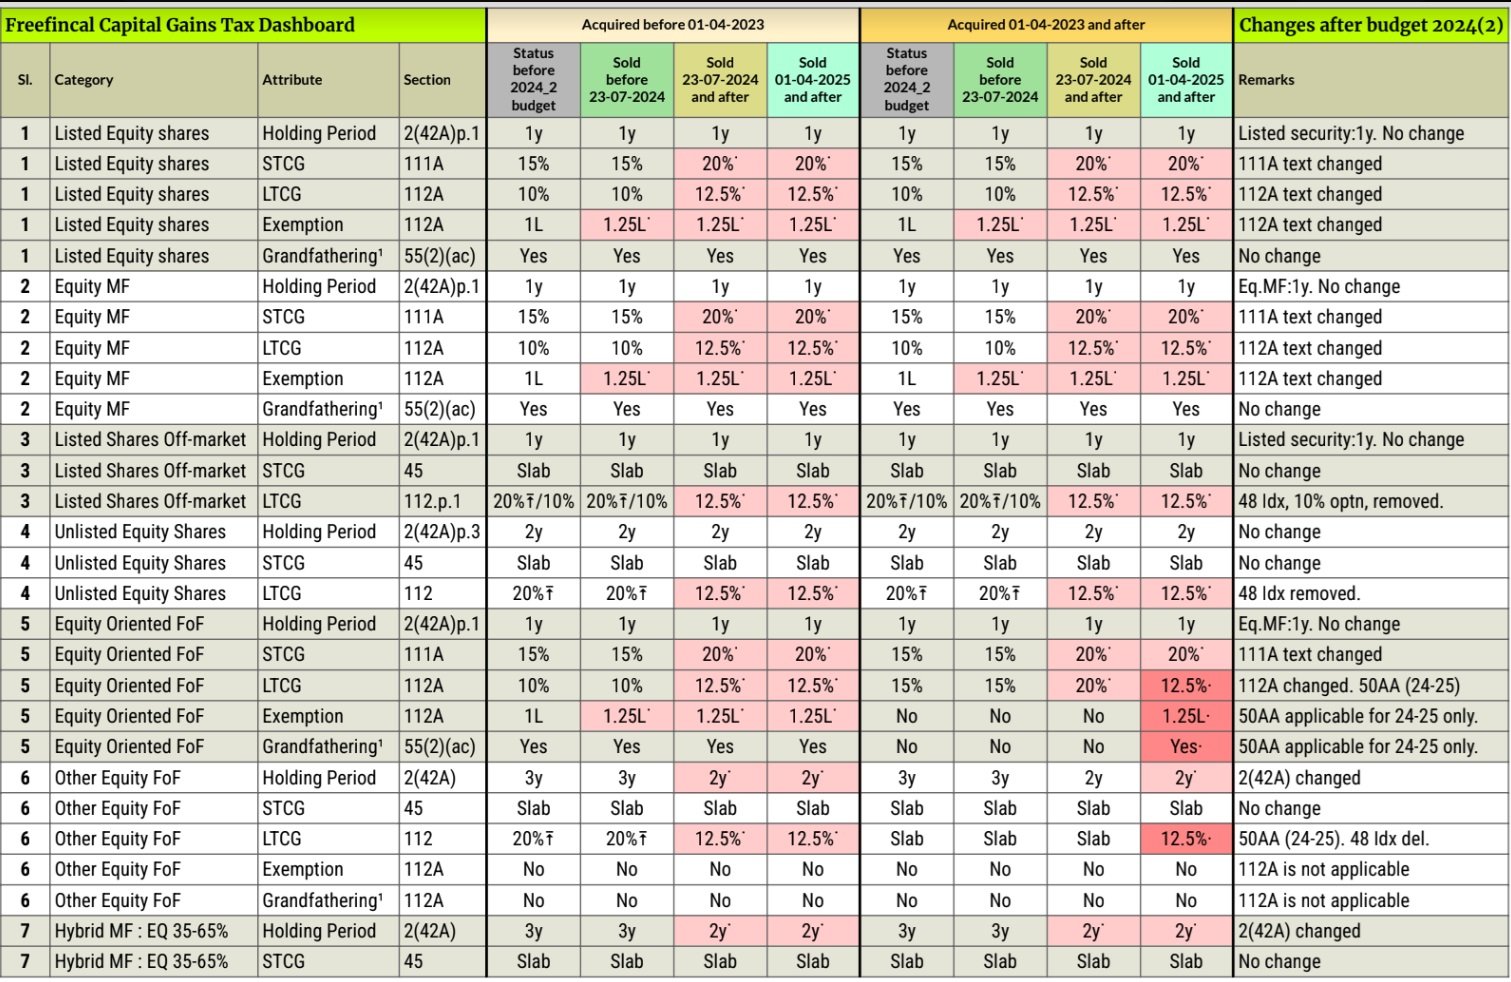
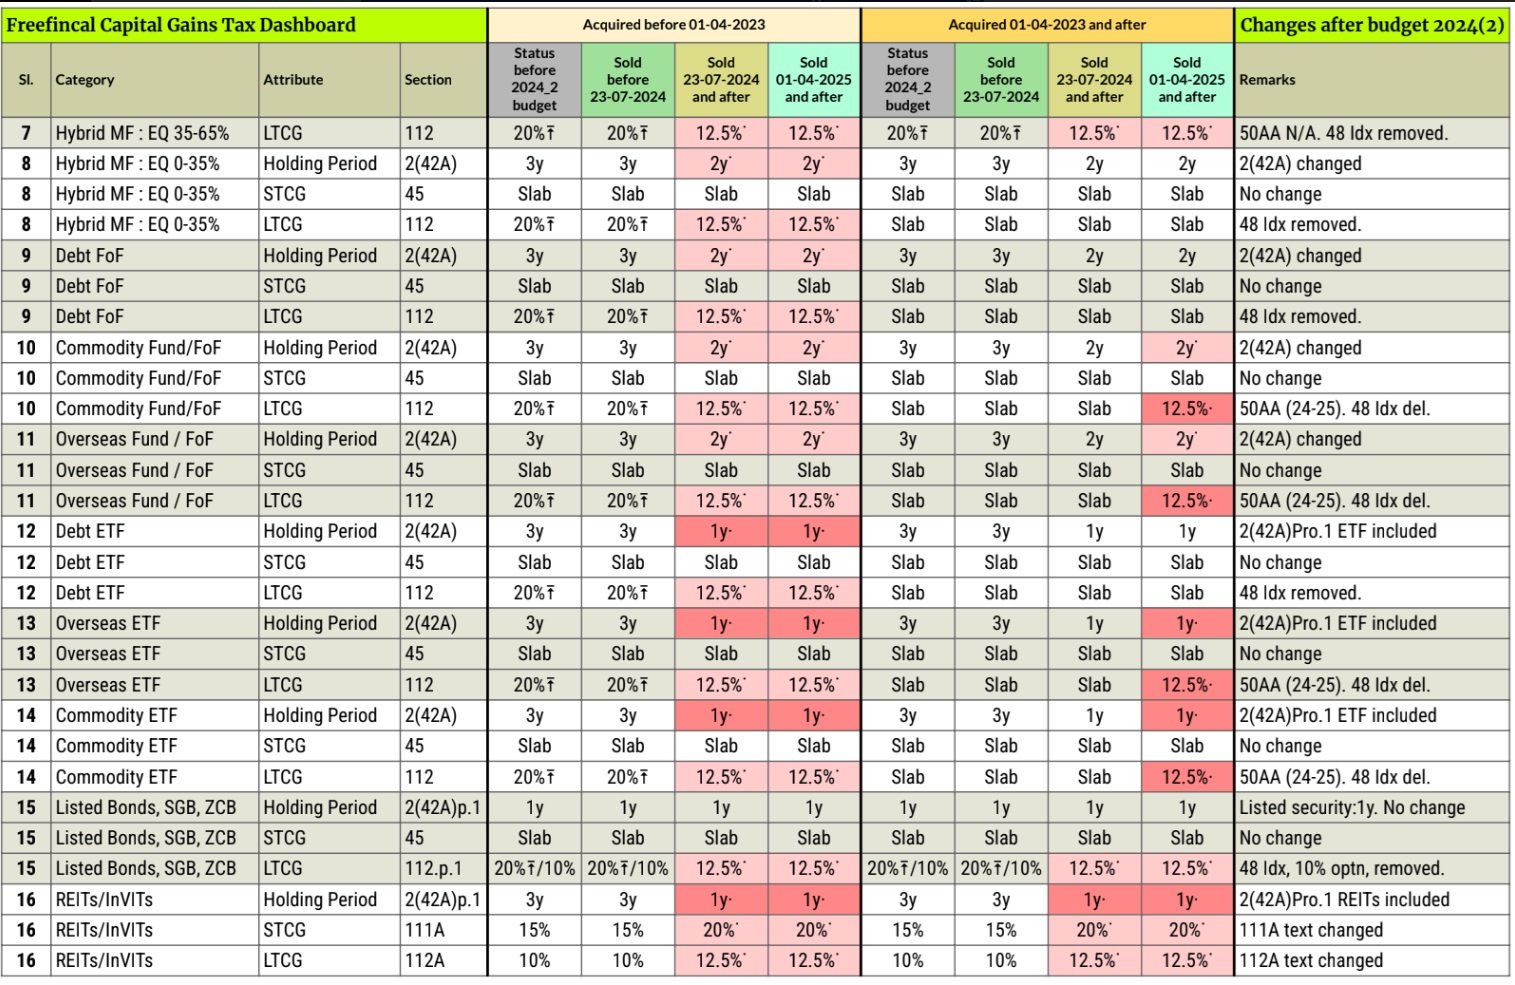
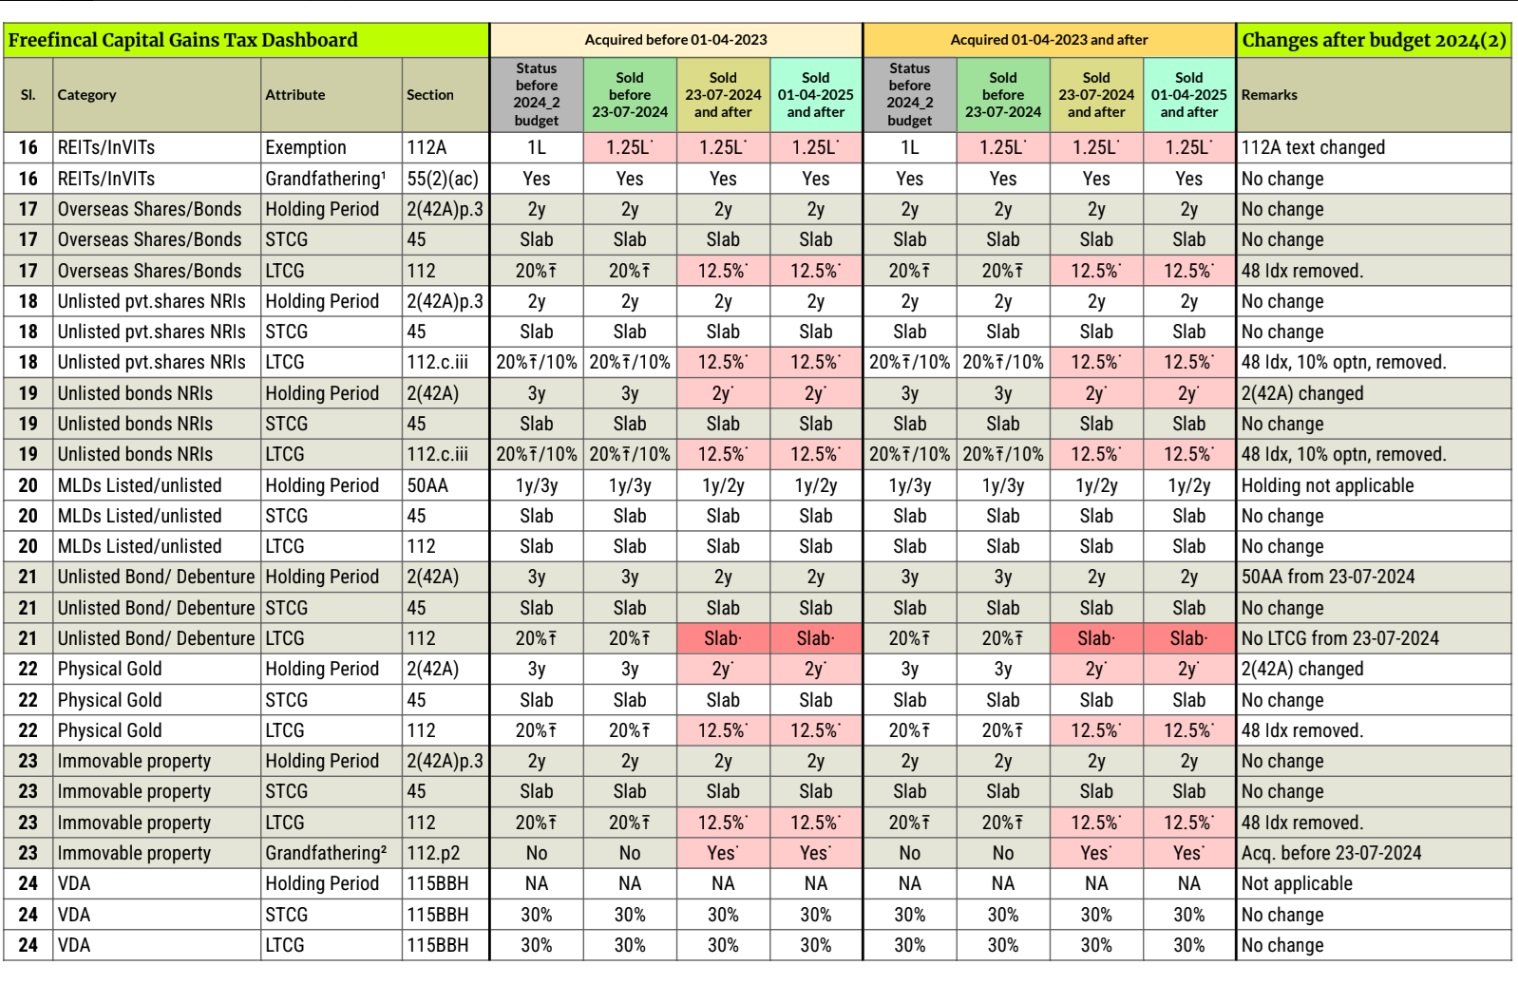
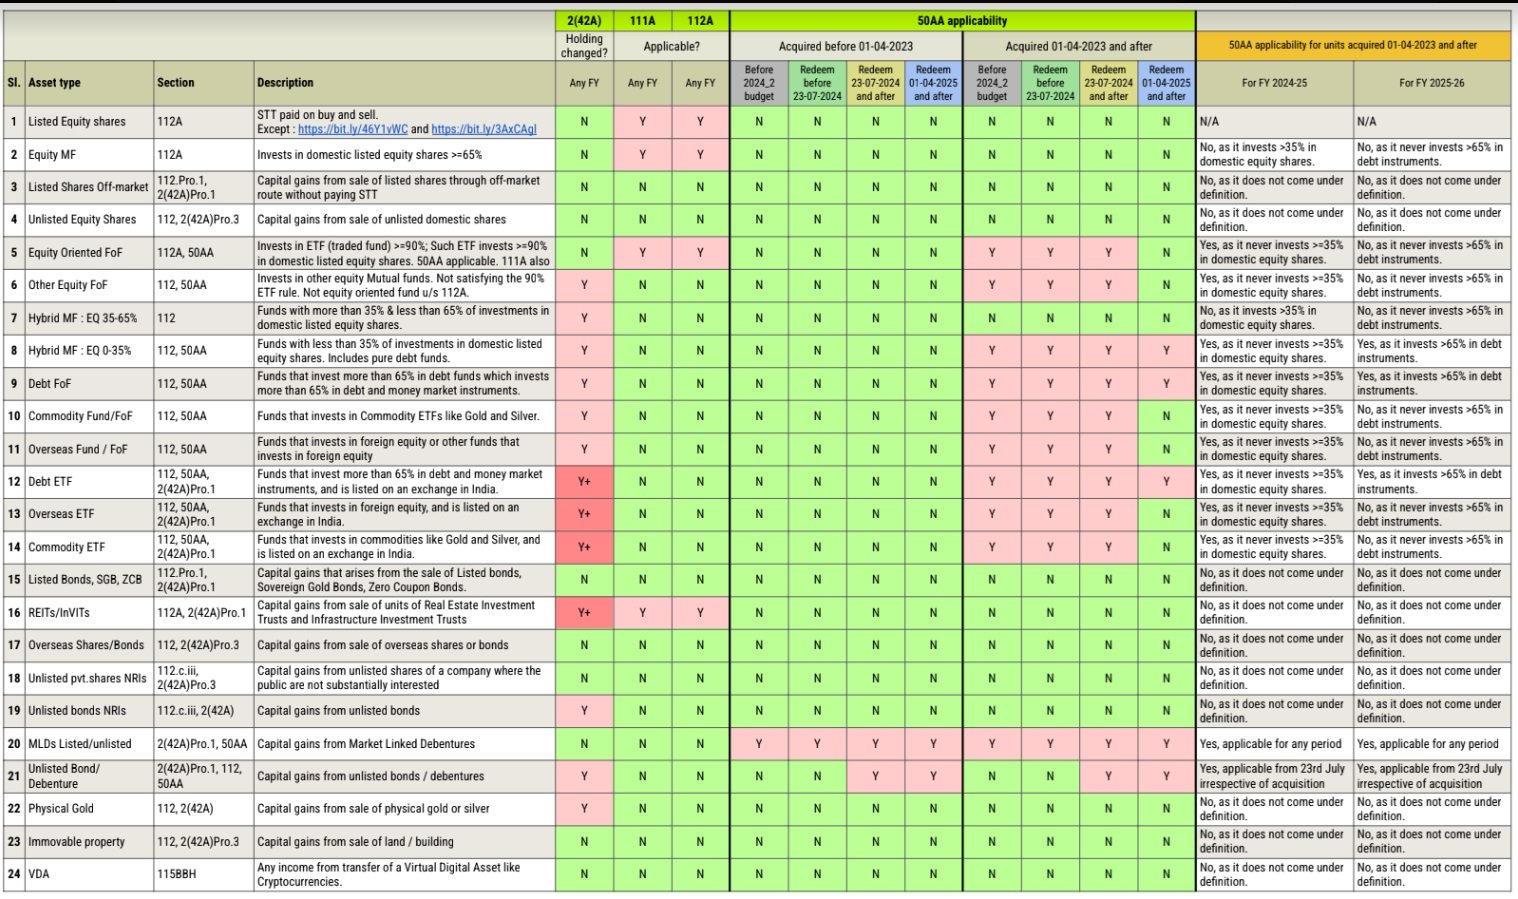
Considering the various rates and holding periods for different assets, both existing
and amended, this creates a complex matrix of permutations and combinations,
which I have compiled to the best of my ability.
Download the Capital Gains Taxation Rules Ready Reckoner for FY 2025-2026
If you are going to share this document, please attribute it to the author Manmohan Sethumadhavan (see X handle below) and the source, freefincal.
Please join me in thanking Manmohan Sethumadhavan for this wonderful effort. He can reached on Twitter (X): @ManuTsr