We plan for inflation, longevity, and market crashes. We rarely plan for our own decline.
For the last five years, I have spent a significant amount of time thinking about retirement planning. Not just the numbers, but the assumptions underneath them.
Like most DIY investors, I started with the obvious questions. How much corpus would we need? What withdrawal rate is safe? How do I stress-test the plan against inflation, sequence risk, and taxation? I built spreadsheets, ran scenarios, and used conservative assumptions, well, because markets owe nobody a guaranteed return.
About the author: Sneha Rege writes about money, behaviour, and the friction between them. Based in Bengaluru, she focuses on the urban Indian salaried professional: the person who is doing most things right and still wonders if it will be enough. She is currently working towards her SEBI RIA credentials. Her work can be found at sneharege.com.
Most of the real struggle, I discovered, had little to do with finding the right fund or the perfect asset allocation. It was behavioural. Learning not to react to every market movement. Resisting the urge to constantly optimise every fall, every high. Accepting that good decisions often feel uncomfortable in the short term.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
But somewhere in this process, a thought occurred to me that no spreadsheet could answer.
I had forgotten to account for myself.
Not the current version of me, but a future version that may not think, analyse, or make decisions the way I do today. Every retirement calculation I had built quietly assumed continuity. The person constructing the plan at forty would remain essentially the same person managing it at seventy-five. I had planned for markets to change, inflation to surprise, and tax rules to shift. I had not planned for the possibility that the decision-maker himself might change in ways no Excel model can capture.
That thought stayed with me far longer than any debate about safe withdrawal rates ever did.
What the research actually says
Growing older always felt like a distant problem. Something to think about later. Then I came across research on ageing and financial decision-making, and it unsettled me in a way that market crashes never have.
I came across a study named ‘Old Age and the Decline in Financial Literacy‘ that highlighted financial literacy declines steadily after the age of sixty, by roughly one percentage point every year. What struck me more than the decline itself was what does not decline alongside it. Confidence. People become measurably worse at financial decision-making while continuing to feel just as capable as before.
That gap between competence and confidence is where the real risk lives.
Researchers have also found that missed bill payments and unusual financial transactions can appear several years before any real signs appear or a formal diagnosis of cognitive impairment. In some cases, the financial system notices the early signs before medicine does. And when I started reading about elder financial abuse in the Indian context, the picture became even less comfortable. The culprits are frequently not strangers running phone scams. They are often people already known to the family – relatives, caregivers, or individuals who have slowly built trust over years.
The most unsettling part is not the decline itself. It is that declining ability often arrives quietly while confidence stays intact. We may not realise anything has changed. And that, perhaps, is precisely what makes it dangerous.
The retirement state nobody talks about
Most retirement planning assumes two states.
You are either alive and capable, managing your wealth with the same judgement you always had. Or you are gone, and wills, nominations, and succession plans take over.
There is a third state that receives almost no attention in any retirement planning conversation I have encountered. Being alive, holding substantial assets, and no longer fully capable of managing them.
This state is harder than death in one specific way. Death is legally clear. Nominations matter. Wills matter. Assets transfer according to documented wishes. But when the person is still alive, ownership and legal authority remain with them, even as the ability to exercise that authority quietly erodes.
The risks here are not dramatic. They are mundane, and that is exactly why they are so easy to ignore. A health insurance premium forgotten. A large withdrawal that nobody questions because the account holder authorised it. A persuasive family member recommending a complicated product. A panic-driven decision during a market correction that undoes decades of discipline. A portfolio gradually becoming unmanageable because it was designed for the cognitive capacity of a fifty-year-old, not a seventy-eight-year-old.
None of this requires severe impairment. It requires only a modest, gradual decline in judgement combined with high confidence and substantial financial resources.
Why the obvious solutions only solve part of the problem
The instinctive answers sound reassuring. Keep nominees updated. Write a will. Simplify the portfolio. Trust your children.
But each of these solves only a portion of the actual problem.
A will, and to a certain extent, a nomination address death, not diminished judgement. Simplifying a portfolio reduces complexity but does not eliminate decisions. Someone still has to decide when to withdraw, when to rebalance, and how to respond to circumstances that change. And trusting family members completely carries its own risks, not because children are necessarily selfish, but because dependence changes relationships in ways nobody plans for.
We all remember Baghban because it touched something real. Not because every family looks like that, but because the film named a vulnerability most Indian families feel but rarely discuss openly. Financial dependence and emotional dependence are two different things, and conflating them in retirement planning can leave a person exposed in ways they did not anticipate.
Perhaps the most difficult part of this problem is what researchers call the handover challenge. The person experiencing cognitive decline is often the last to recognise it. Self-assessment becomes unreliable at exactly the stage when accurate self-assessment matters most. You cannot expect someone to voluntarily step back from financial decision-making when they genuinely believe they are functioning as well as they ever did.
I have seen glimpses of this in older relatives. Nothing dramatic, not dementia, not any headline event. Just growing stubbornness in financial matters, increasing confidence in opinions that seemed to have weakened foundations, small mistakes that everyone around them noticed before they did. The difficulty is that there is no precise moment when responsibility should transfer. No annual check-up that flags it. No dashboard warning. And by the time everyone agrees that something has shifted, time has already passed.
The blind spot
For decades, retirement planning has focused on protecting our future selves from external risks. Inflation, market crashes, longevity, healthcare costs, taxation, sequence risk. These all have frameworks, calculators, and rules of thumb attached to them.
But there is a question that sits outside all of those frameworks.
What if the greatest long-term risk to a retirement corpus is not a market event, but the gradual transformation of the person responsible for managing it?
That question has no clean answer, which is probably why it rarely appears in retirement planning conversations. But ignoring it does not make it less real. It only means the plan has a blind spot where one of its most important assumptions lives unchallenged.
The person who spent thirty years building the corpus may still be around. But the person who knew how to protect it may no longer be.
True financial independence may not just be about building enough money. It may also be about building the systems, structures, and relationships that can protect us from a version of ourselves we have not yet met.
In Part 2, I will explore what some of those structures might actually look like in practice, for an Indian family managing its own finances without professional oversight.
We are on Google News
Use this button to add freefincal.com as a preferred personal finance source on Google News.
Explore 1,400+ videos on YouTube!
Subscribe to get posts via email!
Join 32,000+ readers and get free money management solutions delivered to your inbox! (Link takes you to our email sign-up form)Join our WhatsApp Channel
Explore our products
🔥Join our community of 9000+ users! 🔥- Use our Robo-advisory Tool to create a complete financial plan! More than 3,500 investors and advisors use this! Use the discount code robo25 for 20% off. Plan your retirement (early, normal, before, and after), plus non-recurring financial goals (such as child education) and recurring financial goals (such as holidays and appliance purchases). The tool helps anyone aged 18 to 80 plan for retirement, plus six non-recurring and four recurring financial goals, with a detailed cash flow summary.
- Our Flagship Course! Learn to manage your portfolio like a pro to achieve your goals regardless of market conditions! More than 3,500 investors and advisors are part of our exclusive community! Get clarity on how to plan for your goals and achieve the necessary corpus no matter the market conditions! Watch the first lecture for free! One-time payment! No recurring fees! Lifelong access to videos! Reduce fear, uncertainty and doubt while investing! Learn how to plan for your goals before and after retirement with confidence.
- Join the freefincal investor circle! An exclusive space for investors, advisors, fintech employees and students to access financial planning and insurance tools, mutual fund and stock analysis tools, coding strategies and Excel macros for data extraction. 750+ members are now part of our investor circle.
- Increase your income by getting people to pay for your skills! More than 900 salaried employees, entrepreneurs and financial advisors are part of our exclusive community! Learn how to get people to pay for your skills! Whether you are a professional or small business owner seeking more clients through online visibility, or a salaried individual looking for side or passive income, we will show you how to do it by showcasing your skills and building a community that trusts and pays you. (Watch the 1st lecture for free). One-time payment! No recurring fees! Lifelong access to videos!
- Portfolio Tracker! Track your mutual funds and stock investments with our Google Sheet!
- We also publish monthly screeners for
Our Podcast: Let's Get Rich With Pattu
On Spotify: Let's Get RICH With PATTU! Every single Indian CAN grow their wealth! On Audible: Listen to the Let's Get Rich with Pattu Podcast
Listen to the Let's Get Rich With Pattu podcast on YouTube.
Now watch Let's Get Rich With Pattu தமிழில் (in Tamil)!About The Author
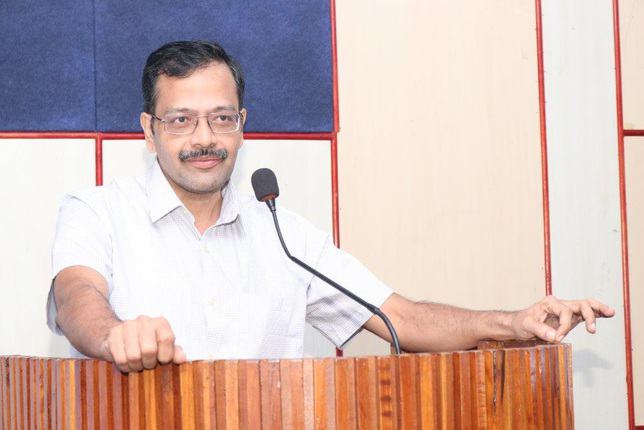
Dr M Pattabiraman giving a lecture
- Dr M. Pattabiraman (PhD) is the founder, managing editor and primary author of freefincal. He is an associate professor at the Indian Institute of Technology, Madras.
- He has over 14 years of experience publishing news analysis, research and financial product development. He has over 28 years of teaching and research experience. He is also a public speaker and keynote presenter.
- He is a patron and co-founder of “Fee-only India,” an organisation promoting unbiased, commission-free, AUM-independent investment advice.
- Connect with him via @pattufreefincal on X LinkedIn YouTube
- Pattabiraman has co-authored three print books.
This book helps you ask the right questions and find the right answers. It also includes nine online calculators to create custom solutions.
(2) Gamechanger: Forget Startups, Join Corporate & Still Live the Rich Life You Want. 
Both the boy and girl versions of "Chinchu Gets a Superpower".
Most investor problems stem from a lack of poor decision-making. We made bad decisions and money mistakes when we started earning, and we spent years undoing them. Why should our children go through the same pain? What is this book about? As parents, what if we had to groom one ability in our children that matters not only for money management and investing but for every aspect of life? My answer: Sound decision-making. So, in this book, we meet Chinchu, who is about to turn 10. The story follows what he wants for his birthday and how his parents plan it, while also teaching him key ideas about decision-making and money management. What readers say! 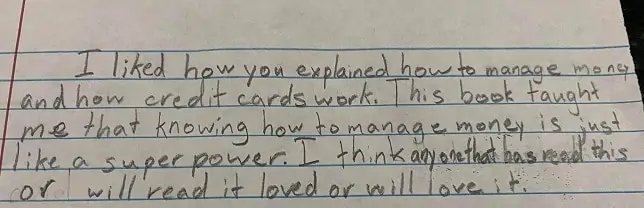
Feedback from a young reader after reading Chinchu Gets a Superpower!
Must-read book even for adults! This is something that every parent should teach their kids right from a young age. The importance of money management and decision-making based on their wants and needs. Very nicely written in simple terms. - Arun.
About freefincal & its content policy
Freefincal is a News Media organisation dedicated to providing original analysis, reports, reviews and insights on mutual funds, stocks, investing, retirement and personal finance developments. We do so without conflict of interest and bias. Follow us on Google News. Freefincal serves more than three million readers a year (5 million page views) with articles based only on factual information and detailed analysis by its authors. All statements made will be verified with credible and knowledgeable sources before publication. Freefincal does not publish paid articles, promotions, PR, satire or opinions without data. All opinions will be inferences backed by verifiable, reproducible evidence/data. Contact Information: To get in touch, please use our contact form. (Sponsored posts or paid collaborations will not be entertained.)Our publications
- Your Ultimate Guide to Travel. This is an in-depth exploration of vacation planning, including how to find affordable flights, budget accommodations, and practical travel tips. It also examines the benefits of travelling slowly, both financially and psychologically, with links to relevant web pages and guidance at every step. Get the PDF for Rs 300 (instant download)
- How to profit from content writing: Our ebook is for those interested in getting a side income via content writing. It is available at a 50% discount for Rs. 500 only!