Last Updated on December 29, 2021 at 5:12 pm
You may have seen advertisements on social media that claim, “8 % Guaranteed Return from LIC, Schemes closing soon!” What is the actual product here? Do you really get 8% returns from such products? In this article, SEBI Registered Investment Advisor, Chandan Singh Padiyar explains the truth about these products and why one should not invest.
Chandan is a familiar name and face on FB group, Asan Ideas for Wealth (AIFW). You can learn more about his journey here: Fee-only Advisor Journey: Chandan Singh Padiyar finds Inner Peace. Chandan is part of the freefincal list of fee-only advisors and also Fee-only India an association of fee-only advisors. If you wish to work with Chandan for your financial plan, you can get in touch via his website: padiyars.
As there is a popular idiom ‘The Devil is in the detail’ let us investigate the truth behind ads such as these, What is the reality of 8 % guaranteed? The following is the illustration from LIC Jeevan Umang Plan No. 845 which provides 8 % guaranteed benefit.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Jeevan Umang is a non-linked, with-profit, whole life assurance plan. As an example, a premium of Rs. 40 per year (excluding service tax) for age 20 to age 45 (25-year term) will result in a basic sum assured of Rs. 1000.
This is known as a guaranteed maturity benefit. Bonuses which are not guaranteed will be added from time to time but these are based on the sum assured. Past bonuses will not be considered.

Since we are trying to investigate about the 8 % mystery let us not get into other details, so here is the IRR (internal rate of return) summary to find the actual returns.
Guaranteed Part | ||
| Sr. No. | Premium | Returns |
| 001 | (38,722) | – |
| 002 | (38,722) | – |
| 003 | (38,722) | – |
| 004 | (38,722) | – |
| 005 | (38,722) | – |
| 006 | (38,722) | – |
| 007 | (38,722) | – |
| 008 | (38,722) | – |
| 009 | (38,722) | – |
| 010 | (38,722) | – |
| 011 | (38,722) | – |
| 012 | (38,722) | – |
| 013 | (38,722) | – |
| 014 | (38,722) | – |
| 015 | (38,722) | – |
| 016 | 40,000 | 40,000 |
| 017 | 40,000 | 40,000 |
| 018 | 40,000 | 40,000 |
| 019 | 40,000 | 40,000 |
| 020 | 40,000 | 40,000 |
| 021 | 40,000 | 40,000 |
| 022 | 40,000 | 40,000 |
| 023 | 40,000 | 40,000 |
| 024 | 40,000 | 40,000 |
| 025 | 40,000 | 40,000 |
| 026 | 40,000 | 40,000 |
| 027 | 40,000 | 40,000 |
| 028 | 40,000 | 40,000 |
| 029 | 40,000 | 40,000 |
| 030 | 40,000 | 40,000 |
| 031 | 40,000 | 40,000 |
| 032 | 40,000 | 40,000 |
| 033 | 40,000 | 40,000 |
| 034 | 40,000 | 40,000 |
| 035 | 40,000 | 40,000 |
| 036 | 40,000 | 40,000 |
| 037 | 40,000 | 40,000 |
| 038 | 40,000 | 40,000 |
| 039 | 40,000 | 40,000 |
| 040 | 40,000 | 40,000 |
| 041 | 40,000 | 40,000 |
| 042 | 40,000 | 40,000 |
| 043 | 40,000 | 40,000 |
| 044 | 40,000 | 40,000 |
| 045 | 40,000 | 40,000 |
| 046 | 40,000 | 40,000 |
| 047 | 40,000 | 40,000 |
| 048 | 40,000 | 40,000 |
| 049 | 40,000 | 40,000 |
| 050 | 40,000 | 40,000 |
| 051 | 40,000 | 40,000 |
| 052 | 40,000 | 40,000 |
| 053 | 40,000 | 40,000 |
| 054 | 40,000 | 40,000 |
| 055 | 500,000 | 500,000 |
| IRR | 4.55% | 2,060,000 |
Now the same working with assumed profit sharing (not guaranteed).
| With Assumed Profit Sharing | ||
| Sr. No. | Premium | Returns |
| 001 | (38,722) | – |
| 002 | (38,722) | – |
| 003 | (38,722) | – |
| 004 | (38,722) | – |
| 005 | (38,722) | – |
| 006 | (38,722) | – |
| 007 | (38,722) | – |
| 008 | (38,722) | – |
| 009 | (38,722) | – |
| 010 | (38,722) | – |
| 011 | (38,722) | – |
| 012 | (38,722) | – |
| 013 | (38,722) | – |
| 014 | (38,722) | – |
| 015 | (38,722) | – |
| 016 | 40,000 | 40,000 |
| 017 | 40,000 | 40,000 |
| 018 | 40,000 | 40,000 |
| 019 | 40,000 | 40,000 |
| 020 | 40,000 | 40,000 |
| 021 | 40,000 | 40,000 |
| 022 | 40,000 | 40,000 |
| 023 | 40,000 | 40,000 |
| 024 | 40,000 | 40,000 |
| 025 | 40,000 | 40,000 |
| 026 | 40,000 | 40,000 |
| 027 | 40,000 | 40,000 |
| 028 | 40,000 | 40,000 |
| 029 | 40,000 | 40,000 |
| 030 | 40,000 | 40,000 |
| 031 | 40,000 | 40,000 |
| 032 | 40,000 | 40,000 |
| 033 | 40,000 | 40,000 |
| 034 | 40,000 | 40,000 |
| 035 | 40,000 | 40,000 |
| 036 | 40,000 | 40,000 |
| 037 | 40,000 | 40,000 |
| 038 | 40,000 | 40,000 |
| 039 | 40,000 | 40,000 |
| 040 | 40,000 | 40,000 |
| 041 | 40,000 | 40,000 |
| 042 | 40,000 | 40,000 |
| 043 | 40,000 | 40,000 |
| 044 | 40,000 | 40,000 |
| 045 | 40,000 | 40,000 |
| 046 | 40,000 | 40,000 |
| 047 | 40,000 | 40,000 |
| 048 | 40,000 | 40,000 |
| 049 | 40,000 | 40,000 |
| 050 | 40,000 | 40,000 |
| 051 | 40,000 | 40,000 |
| 052 | 40,000 | 40,000 |
| 053 | 40,000 | 40,000 |
| 054 | 40,000 | 40,000 |
| 055 | 3,530,000 | 3,530,000 |
| IRR | 6.15% | 5,090,000 |
If we see the above working the actual Guaranteed Return results in an annualized return of only 4.55 % and with assumed Profit sharing, which is not guaranteed works out to 6.15 %.
What actually is this 8 % all about?
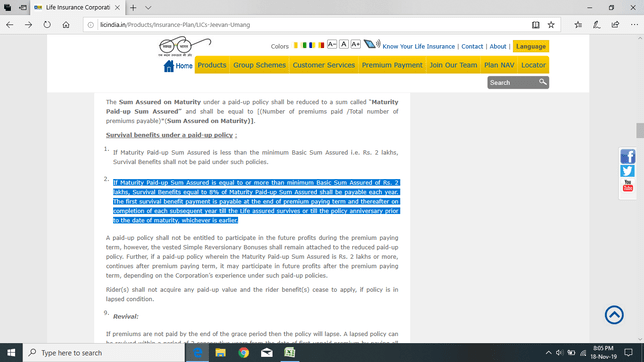
As per LIC, the 8 % Survival benefit is paid on the Sum assured value after 15 years of regular premium payment, hence in the above illustration Rs. 40,000 is 8 % of the Sum Assured Rs. 5,00,000.
However, this is not same as earning 8 % PA on your investment as claimed in the advertisements. Investors must calculate the annualized return as done in the tables above and not be carried away by the advertisements and illustrations provided by agents.