Last Updated on February 12, 2022 at 6:23 pm
A reader who prefers anonymity asks, “Am I on track to achieve Financial Independence (FI) in the next 13 years? I intend to continue working in a corporate setup for as long as my mind, body and employer (current or future) allow. The FI target is more to ensure that money is no longer an important reason to keep doing so”.
Please find my details below.
- Current Age: 34
- FI Target Age: 47
- Family: Working couple with no kids as of now; planning to expand the family with a single child + Parents who are retired senior citizens and I support their day-to-day living expenses
- Current Income: Including monthly salary and annual bonuses, both of us combined bring approx. INR 2.25 lakhs per month after taxes (PF and NPS contributions extra)
- Current mandatory expenses: INR 50,000 per month
Current discretionary expenses (vacations, gadget purchases, eating out etc.): INR 15,000 per month (this has been drastically reduced in the last two years due to COVID but will likely come back at this level) - EMI: INR 75,000 per month (EMI as per loan schedule is INR 65,000 + I add a monthly prepayment of INR 10,000)
- Current liabilities: Home loan with a little over INR 90 lakhs outstanding at 6.85% for 25 years. I don’t intend to aggressively prepay as of now (apart from the additional amount I pay each month), given the low-interest rates. If rates increase significantly, I may focus on additional staggered prepayment.
- Insurance: Term insurance of INR 3.5 crores for self and INR 50 lakhs for the wife.
- Health insurance of INR 7 lakhs (family floater covering four members) and a super top-up of INR 10 lakhs for parents.
- Critical illness covers INR 40 lakhs for self and INR 20 lakhs for the wife.
- Emergency funds: INR 6 lakhs (at most times, I try and maintain this at about one year’s mandatory expenses; invested in FDs of mid-sized private banks)
- Current corpus (including amount invested, interest earned and capital gains): INR 50 lakhs. The equity: debt ratio is 40:60; I plan to take this to 55-60% equity and 45-40% debt, followed by a gradual shifting to debt. Almost the entire current equity investment is into multicap, hybrid aggressive and balanced advantage funds.
- Current monthly investment (including EPF and NPS contributions): approx. INR 1 lakh (most of the additional investment goes into multicap, hybrid aggressive and balanced advantage funds)
- Additional info: Financially, my parents have lived a lifestyle similar to mine (focused on decent savings and investments without depriving themselves of what they needed for comfort, interests, hobbies etc.). Their investments are mostly in debt, LIC policies (premiums paid off), and gold, with smaller equity and real estate amounts. While I continue to support their day-to-day living expenses, I would later inherit these assets as the only child. I am not banking on this whatsoever and don’t know the number (I have not included this element in any of the above). However, I believe the number will be decent and certainly non-trivial.
Overall you are in a pretty good place, and from the way you have structured your question, anyone can tell that you appreciate the importance of holistic financial planning.
We have one suggestion about health insurance: Check if you can split the floater plan into two: One for you and your wife (and child later) and another for your parents. This way, you can increase the cover for your family if not for your parents. Also, buy a super top plan for yourself and your wife.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Now, about financial independence, it is good that it a not a hard requirement. Let us punch the above numbers into the freefincal robo advisory tool to check if the reader can achieve financial independence in 13 years by age 47.
- Current monthly expenses we will assume as Rs. 70,000 plus an additional annual expense of Rs. 50,000 for paying insurance premiums etc.
- Value of current equity investments Rs. 20 lakh (approximately)
- Value of current debt investments Rs. 30 lakh (approximately)
- Inflation before retirement (%) 6
- The assumed life expectancy of the younger spouse is 90 (we have assumed she is two years younger)
- Inflation during retirement (%) 6
- Years to retirement 13
- Monthly expenses in the first year of retirement 1,58,192
- Years in retirement (until younger spouse reaches age 90) 45
- The total corpus required is Rs. 6 crores, out of which Rs. 4.72 crores have to be realised from future investments.
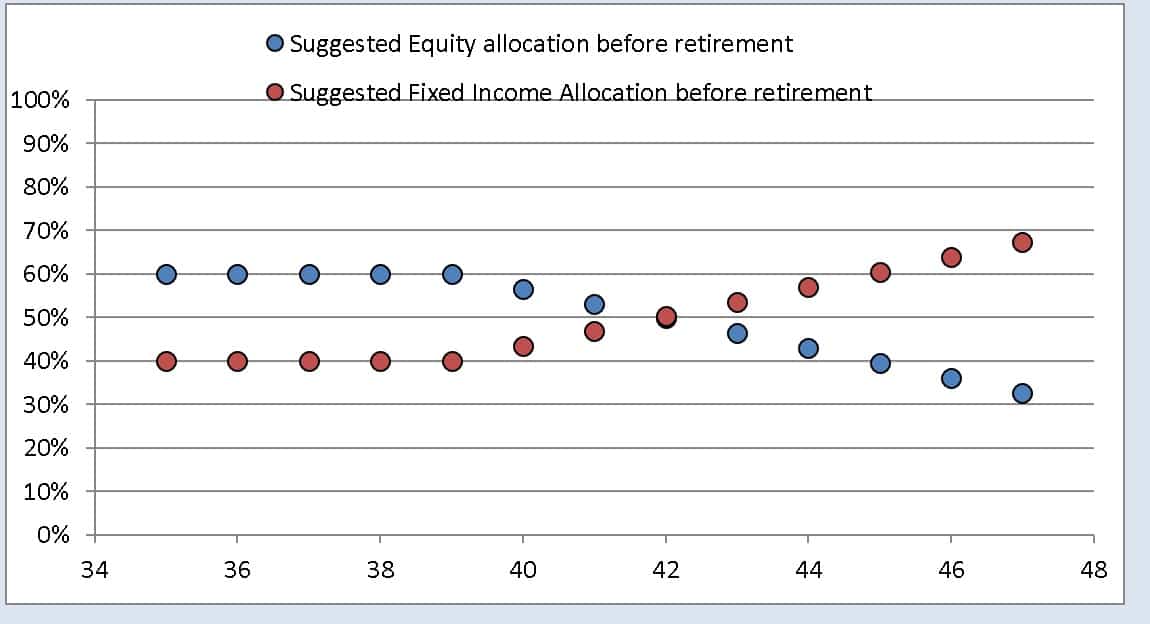
We recommend increasing the equity exposure to 60% as soon as possible and following the asset allocation schedule recommended by the robo tool.
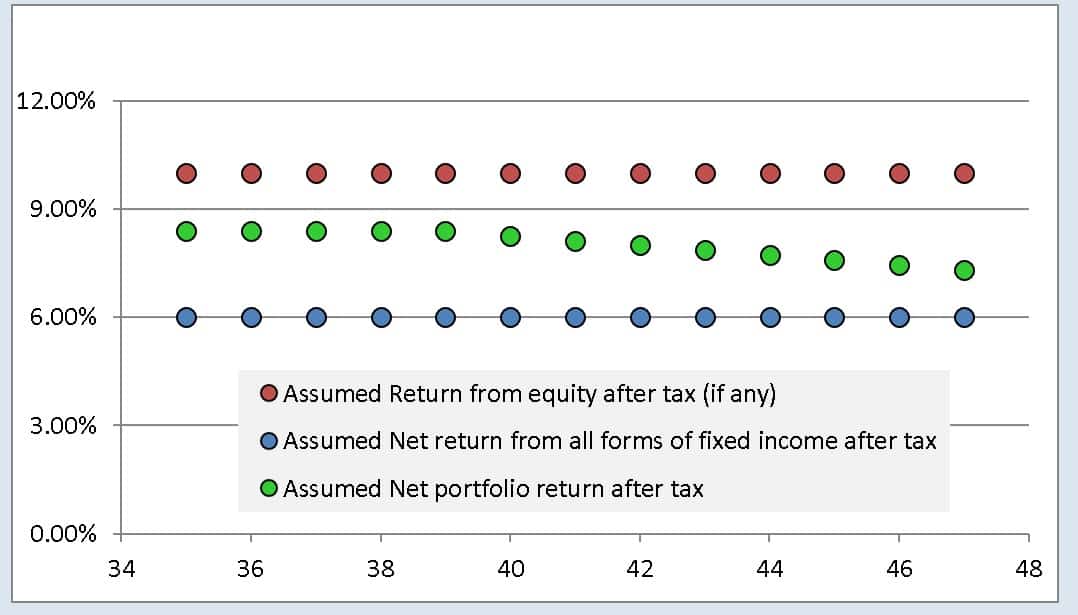
We have used 10% return from equity and 6% from fixed income (debt), and therefore, the portfolio return will gradually decrease from 8.4% to 7.3%, as shown below.
Further, a retirement bucket strategy where the corpus is divided into an income bucket; a low risk bucket; a medium risk bucket, and a high-risk bucket is also part of the calculation. For example, see: I am 30 and wish to retire by 50; how should I plan my investments? And Retirement plan review: Am I on track to retire by 50?
The total investment in equity and debt required in the first year (increasing each year by 10%) is just a little more than Rs. One lakh, which is close to his current total investments.
Thus the reader is definitely on track to get close to financial independence in the next 13 years. Even if he cannot increase investments by 10% each year, as long as he does his best to increase it as much as possible, he should be in a strong position. We wish him all the best.