I have invested in the National Pension Scheme (NPS) since 8 March 2010. This is a performance report showing how the NPS has fared over the last 15+ years. We also compare the returns with the EPF.
Note 1 For government employees: We have extensively written about the Unified Pension Scheme vs the National Pension Scheme
- NPS vs UPS: How to make the right choice for your situation
- Why I will not opt for the unified pension scheme
- UPS vs NPS Calculator
Note2 for others: Kindly do not assume that I am recommending NPS instruments. My situation is quite different from most. NPS is a mandatory investment for me. The asset allocation is 15% equity and the rest in gilts (govt bonds). If you are in a corporate setup, please recognise that NPS has a lock-in of up to 60. Most corporate employees will not work until that age. If you exit before 60, 80% of your corpus will be locked into an annuity. So, our recommendation has always been not to invest in NPS.
Note 3: We now publish a monthly National Pension Scheme Fund Screener to shortlist consistently performing NPS schemes.
My NPS corpus is about 34.8% of my equity MF + stocks corpus tagged to retirement. It is about 20.4% of my total retirement portfolio. It has taken a lifetime to reduce the dependence on NPS. For more details, see Sixteen Years of Mutual Fund Investing: My Journey and Lessons Learned.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
I have been part of the NPS since 2006. However, the NPS was not ready for investment then. Until then, the organisation F&A held the money with 8% annual interest. The first investment into NPS funds was made on 8th March 2010.
We shall track the progress from that date. The money was almost equally divided among the three Tier 1 (central govt) schemes offered by UTI, LIC and SBI.
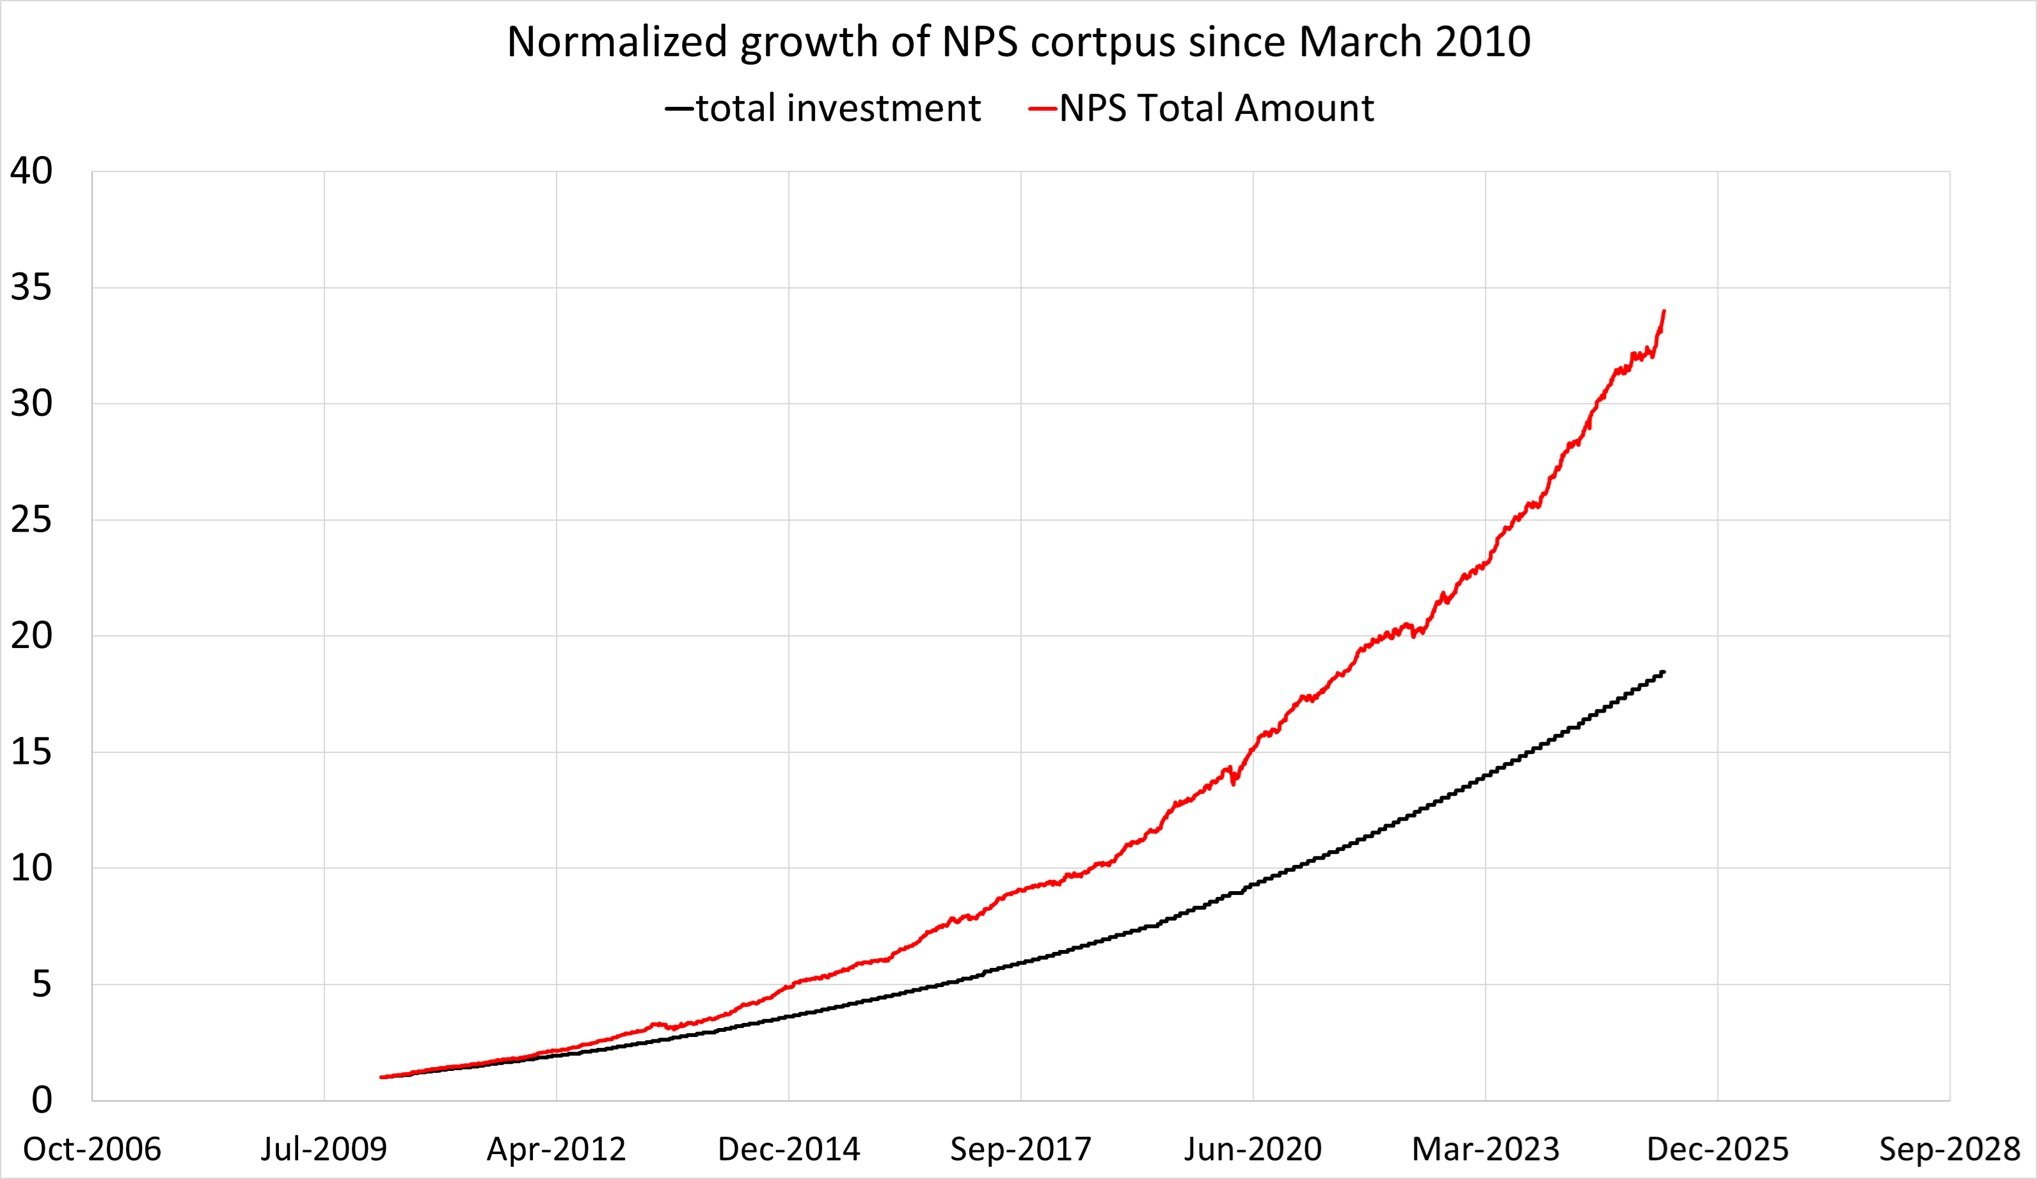
With employer contribution, NPS is one of the best step-up SIPs in a mutual fund. My monthly investment today is five times more than ten years ago. That is a 15.1% year-on-year investment increase spanning two pay commissions and a promotion. You can see that in the curvature of the total investment line below.
This is the growth of the NPS portfolio along with total investments. The XIRR as of 19th April 2024 is 9.36%. Not too shabby.
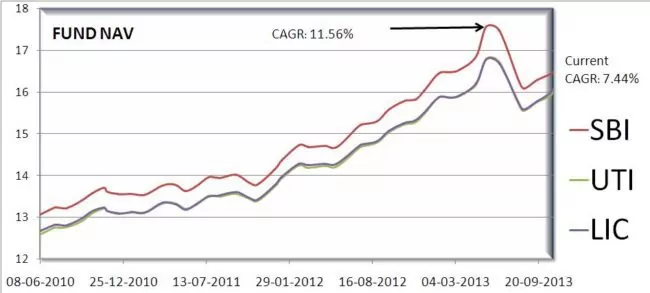
In July 2013, the RBI increased overnight rates by 2% to stop the fall of the Rupee. My gilt-heavy NPS portfolio took a mighty tumble. This is what the NAV looked like in Oct 2013. My NPS CAGR just before the fall was 11% ish; overnight, it became 6-ish%, recovering over the next few months. When this occurred, PFRDA realised, “Aisa bhi hota hai! What if this happens just before the person retires?!” and introduced staggered withdrawals.
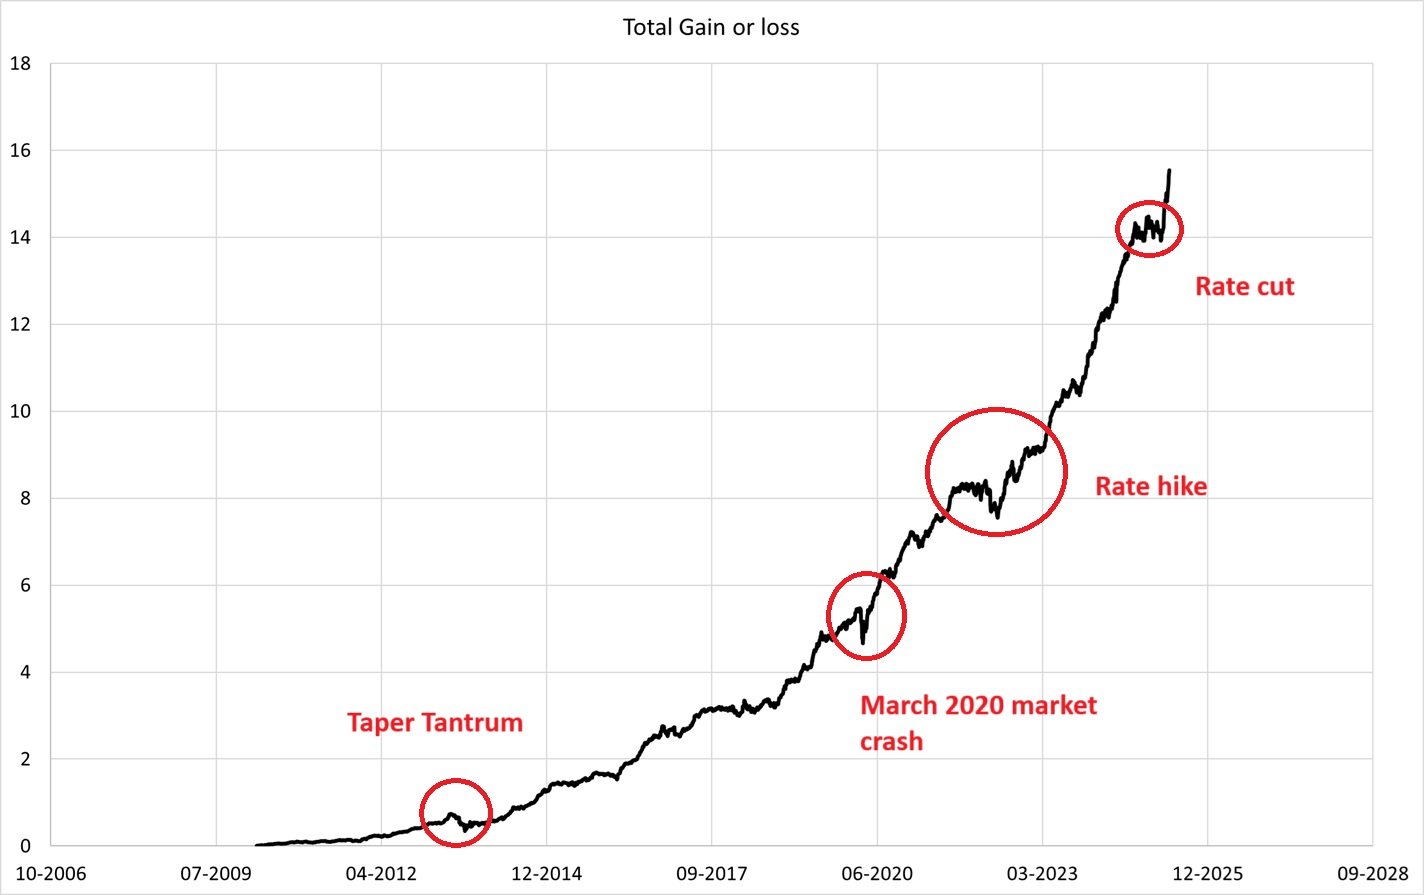
Annotated loss of gain in the NPS portfolio.
NPS vs EPF
This compares the NPS NAV (the SBI central govt fund has been used as a representative) and the EPF NAV (constructed from annual interest rate history).
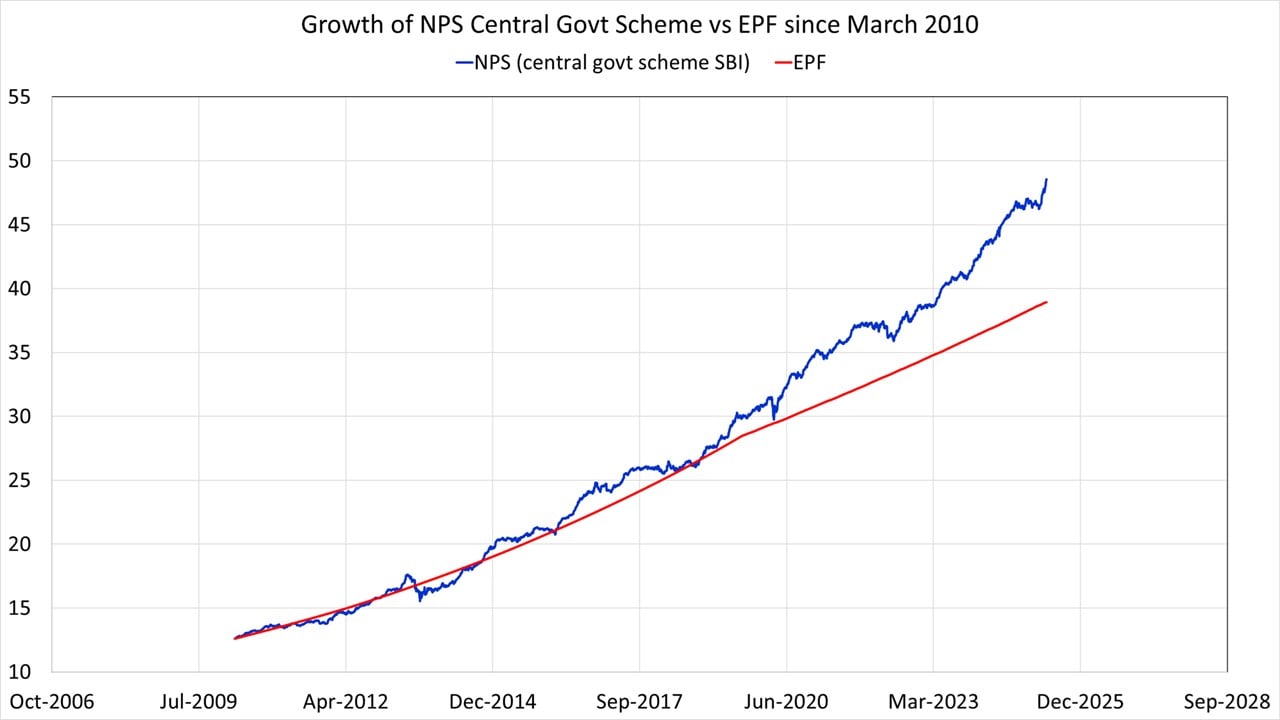
At the time of writing, NPS has outperformed EPF, but that may not always be true! If I had invested in EPF instead of NPS ten years ago, the NAV evolution (assuming daily growth = annual interest/365) would look like this.
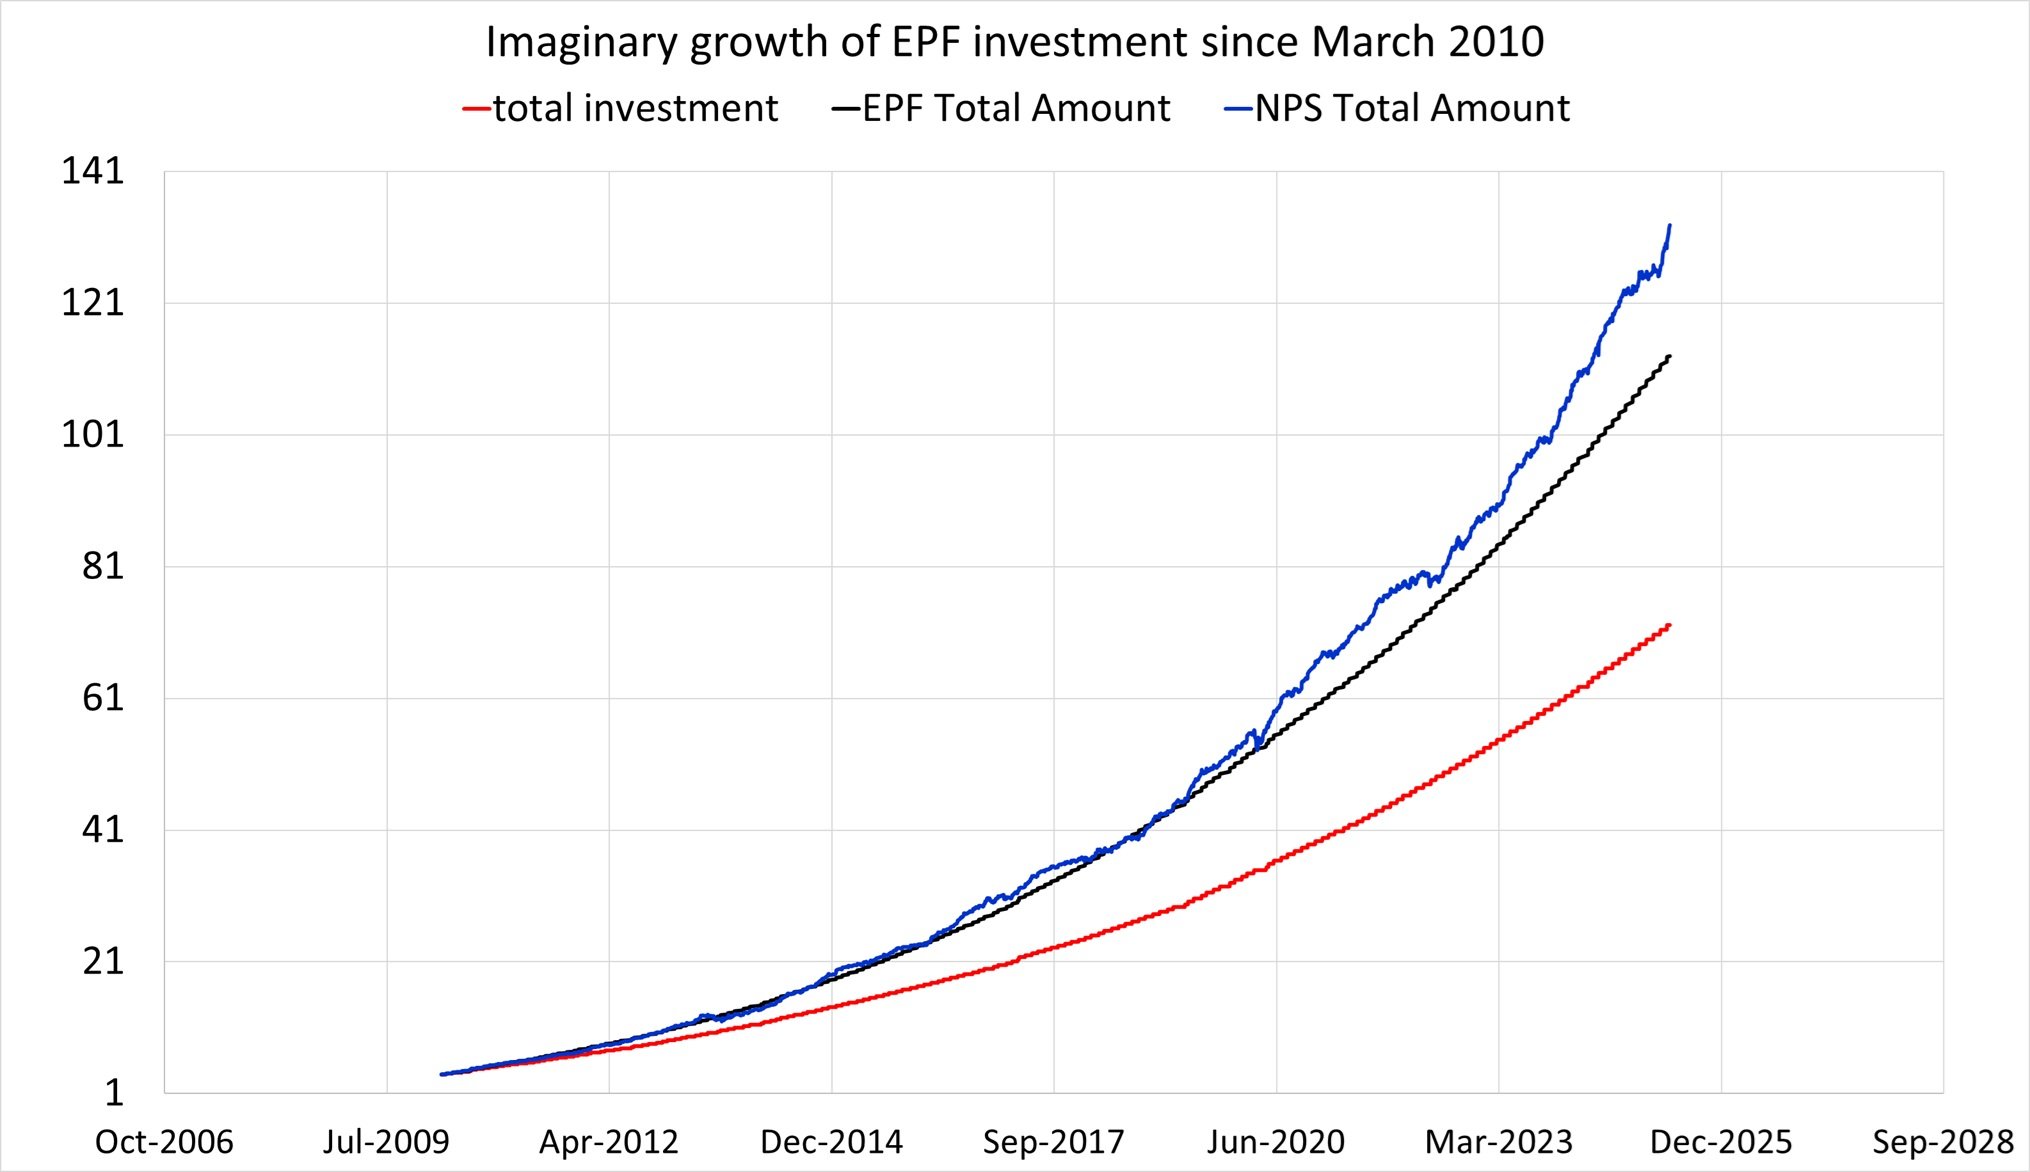
It is hard to beat the non-volatile growth of EPF, but it is not too shabby for a mandatory investment! The asset allocation of central govt employees can now be modified. I have not changed it (and recommend others not to do it too). Using NPS as a pure-debt fund and managing equity separately works well for me
Also, see:
- Can I use NPS Tier II as a low-cost index fund?
- NPS equity schemes underperform Nifty, Nifty 100: time for passive approach?
- Why you should avoid equity (scheme E) in your NPS portfolio!