Last Updated on July 14, 2026 at 10:20 am
This is a question that we have received several times in the last few months: Since NPS (National pension scheme) is a low-cost product, can we use it as an index fund. Typically people wish to use Tier II this way since it has no lock-in. A discussion.
First, the basics. NPS Tier I and Tier II are low-cost mutual funds, but they are NOT passive funds or index funds! Go to any NPS PFM site (pension fund manager). Under “public disclosures”, look for “policies” or “investment policies”.
This, for example, is the objective stated by SBI Pension Fund
generating the best available returns for the subscribers over the long term while ensuring the safety and security of such investments. Keeping in view the fact that returns are market related, it is proposed to strive for yield maximization within the investment pattern approved by PFRDA and chosen by the subscribers
No “passive” investment would aim for this. Also, come to think of it, it is not safe for NPS to be a passive investment, nor is it practical. Sensex or Nifty or even NIfty 100 could have a few stocks with more than 10% weight. This could mean a huge chunk of AUM concentrated in a few stocks. NPS portfolios do have a few concentrated bets, but as its AUM grows, that decreases. The extreme example is the government NPS portfolio with each security weight not more than a few per cent.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Also, one cannot hold a Tier II account without a Tier I account. If NPS is mandatory for you or is provided as an option by the employer with employer contributions, then and only then does it make sense to discuss Tier II. Because NPS itself does not make sense otherwise.
The key reason for our vehement objection to NPS is liquidity (the ability to redeem when we want and how much ever we want). Most investors fail to appreciate this because they have a spreadsheet-like vision of the future: “If I invest Rs X every month and it grows at the rate of Y per cent, how much will I get after Z years”. It is fun to play this game in a spreadsheet, but there can be a hundred reasons why we would need the money before the Z years are complete in real life.
NPS has an atrocious exit clause. Exit at age 60 or after, you can get back 60% of your corpus tax-free – this is quite fine. Exit one year earlier, and you lose 40% of that corpus to an annuity.
All sorts of arguments were invented by investors who only invested in NPS because of the “extra 50K tax-saving”: “but a retirement product should have a lock-in”, “investor should use other investment for liquidity”, etc. The logic is similar to an emergency fund: those who have never witnessed an emergency try to find out the “best way to invest the emergency fund”. Similarly, those who have never seen a liquidity crunch assume it is not necessary.
So when Tier I does not make sense (unless you have a stable job and get tax-deductible contributions from an employer), there is no point discussing Tier II. Leaving alone this talk of liquidity which few would appreciate, let us look at scheme returns.
The NPS trust publishes weekly returns, and some portals like Value Research or ET provide daily updates. In Sep 2019, we published a detailed study of NPS Tier 1 Equity Scheme Performance vs Nifty 50 and Nifty 100 and showed that established NPS PFMs have underperformed the Nifty 100.
Some reactions to this were amusing: “but look at HDFC PFM. They have got better returns”. If you look at returns as of March 12th 2021, HDFC beat the index over 3/5/7 years underperformed the index by almost 3% in the last year like a typical active fund. Also, the spread in returns across PFMS is high again, typical of active funds.
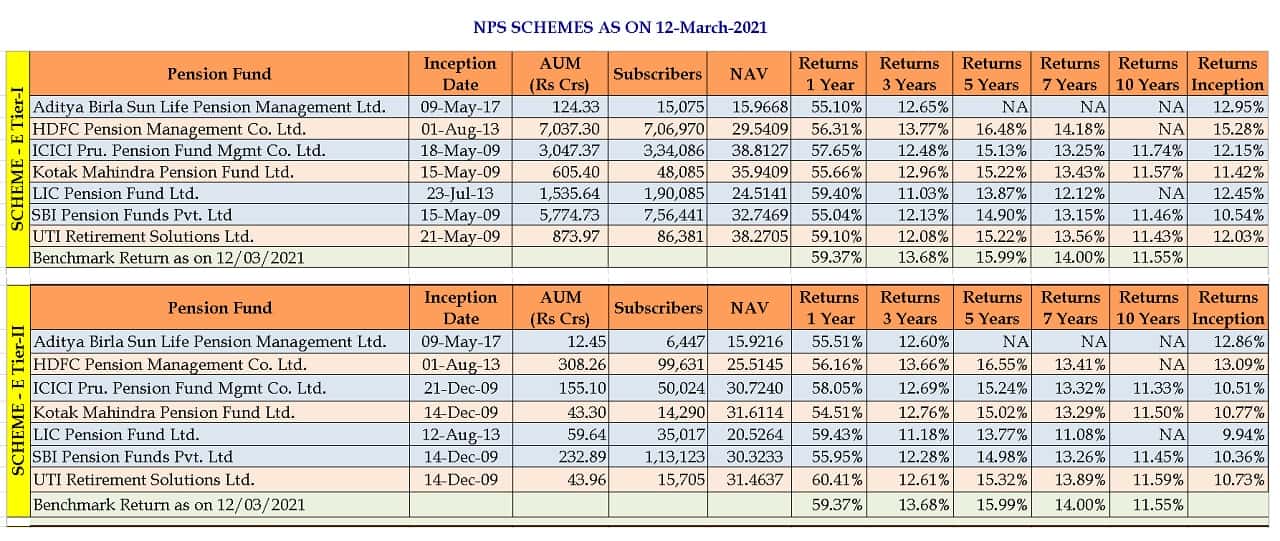
To say the least, the investment strategy of these funds (assuming there is one) is vague. It makes no sense to invest in NPS Tier II (or Tier I) just because the TER (0.01% PFM fee + 0.005% NPS trust fee + 0.0032% custodian fee + POP fee on investment) is “low”.
Even if a Sensex/Nifty index fund (0.1%) fee is about 1.7 times higher than the typical Tier I or Tier II equity scheme, the mandate is clear. NPS funds may be “low cost”; they are also “low” on active management, too, with many of them not doing more than following the index or even underperforming it. This is unacceptable when the mandate is to “maximise gains/yield”. There is more to investing than “low fees”.
Then there is the factor of taxation. No one knows how Tier II is to be taxed. That is, there is no official documentation on it. This means until there is such documentation, you have to report these as “income from other sources” and tax them as per slab!
- If you invest in corporate or individual NPS, we recommend that you use a mix of G (govt bonds) and C (corporate bonds) schemes in Tier I and avoid Tier II.
- If you invest in govt NPS, we recommend you stick to the default allocation: 15% of Equity and the bulk of the remaining in G.
- If you are considering NPS for saving tax, we recommend that you stay away. If you cannot sleep in peace without getting that “50K benefit”, at least ensure you invest enough elsewhere!