A Let’s Get Rich with Pattu podcast listener writes, “If I have invested ~40-50% of the house price, is it a good idea to take out that amount and pay as a downpayment, or take the max loan amount possible, keeping the investment intact, paying more EMI and hence lesser investments thereafter till the loan is repaid. (Assuming already saved investments give ~10-12% returns vs. house loan at ~8.5%)”
We always recommend that home buyers do a full-fledged retirement planning exercise before the purchase. This helps them balance the house purchase with investments for retirement (and other goals like children’s future, etc.).
While paying 40-045% as a downpayment while getting a home loan is a good idea, it is important to consider the source of these funds.
Suppose the investment of 40-45% of the house prices was made specifically for that purpose, without compromising on retirement planning and other long term goals. In that case, it is quite obvious that the entire amount should be the downpayment. Unfortunately, this is rarely the case with most wannabe home buyers.
In our opinion, this is the ideal post-tax monthly income breakup to balance EMIs with expenses and investments.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
- 30% expenses
- 30% EMI
- 30% investments (this includes mandatory deductions like EPF/NPS)
- 10% buffer for emergencies
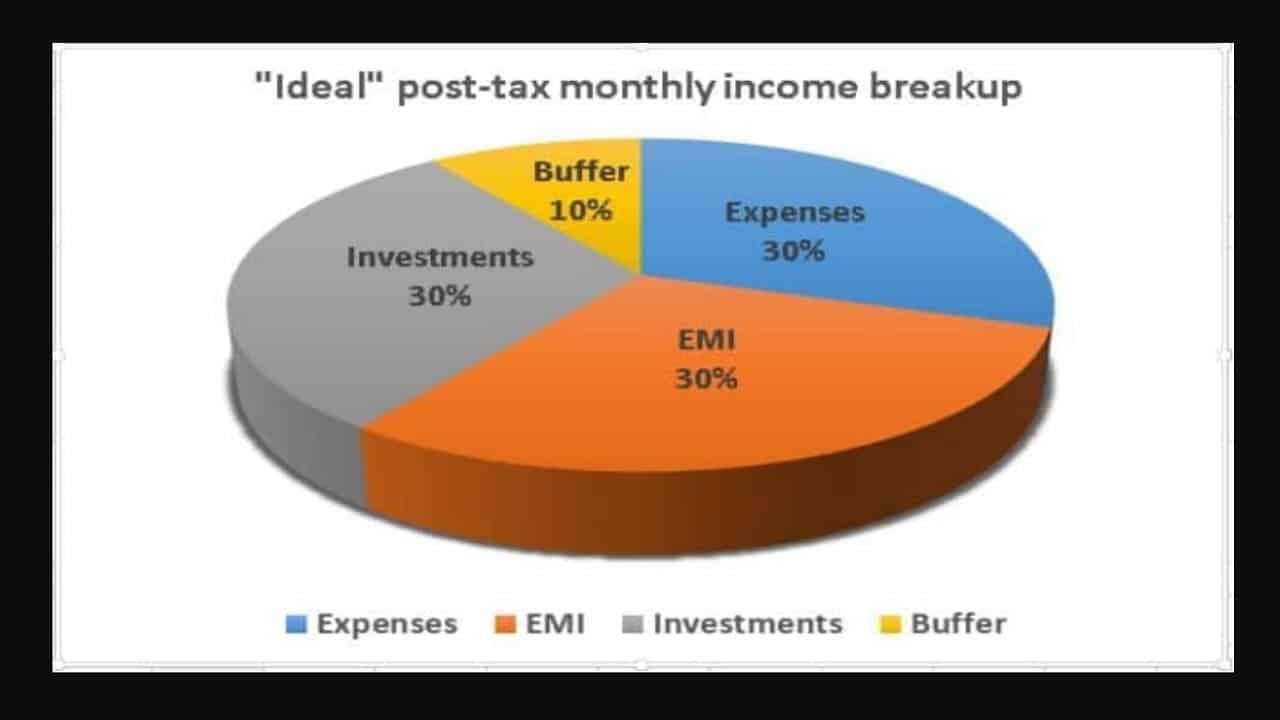
At best, the EMI can increase to 40% of post-tax income. Any higher than that would be stifling. Therefore, we recommend the following:
- Do not worry about home loan rates and investment returns. A comparison is pointless as their purposes are different.
- Focus on investing for long-term goals and invest what you can for the home loan down payment.
- Wait until your EMI take-home EMI is between 30% to 40% of your post-tax before getting the home loan.
- Once the home loan starts, do not give up on investments. Try to keep them up as much as possible.
- Do not be in a hurry to pre-close the loan. As long the EMI is comfortable to handle, it can be continued for as long as possible. Focus on investing and increase investments by 5% to 10% each year as your salary increases.
- You can use your bonuses every few years to gradually prep-pay the home loan. There is no flaming hurry to do this. See: Why this kolaveri to pre-pay home loans?!