A reader asks, “I will be earning around ₹10 lakh as business income in FY 2025–26. Additionally, if I earn ₹2 lakh as gains from debt mutual funds. I’m confused about how these debt fund gains will be taxed this financial year.”
“Here are two versions of what I’ve come across online: Some sources claim that debt fund gains are no longer classified as STCG/LTCG, and instead, they are taxed according to the individual income tax slab. → So if my total income (business + debt gains) is under ₹12 lakh, it means zero tax on these gains.”
“Others are saying that debt fund gains are taxed as per your slab but separately from business/professional income as STCG, and hence tax applies on the example I told. (gains taxed as per the slab rate) → so I have to pay tax for the 2L gains from the debt fund even if the total income does not exceed the 12L limit”.
About the author: Manmohan Sethumadhavan is a freelancer, investor, and personal finance enthusiast “in search of the absolute truth.” You can follow Manu on Twitter @ManuTsr.
The nil tax liability up to ₹ 12 lakhs is available through the 87A rebate. This rebate, under the new regime, applies only to incomes whose tax is calculated using slab rates.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
See:
- Is 87A rebate applicable debt MF purchased before 2023 and sold in Feb 2025?
- Is 87A rebate applicable for capital gains after budget 2025?
For debt funds, the tax calculation is explained in the Freefincal Capital Gains Tax Ready Reckoner Version 2.0. No.8 Hybrid MF: EQ 0-35%. This is a screenshot.
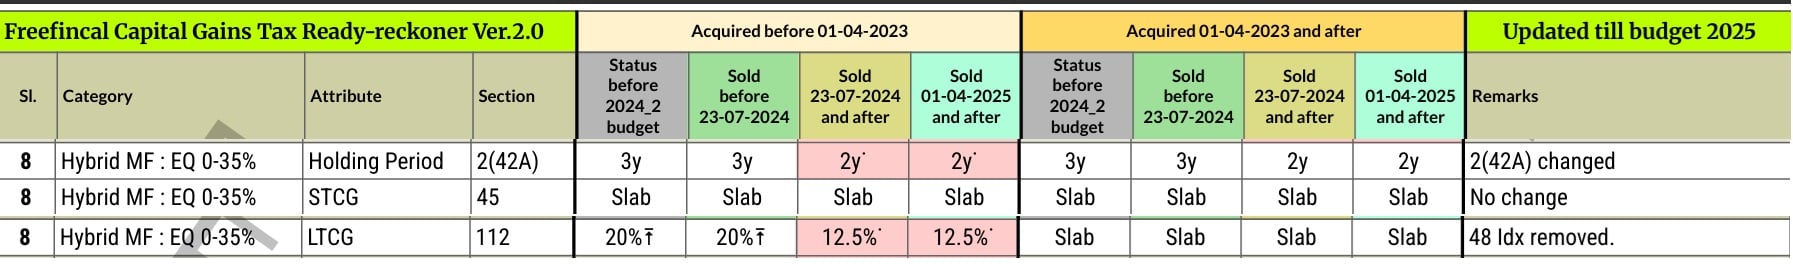
If the tax is calculated under slab rates depending on your date of acquisition, the 87A rebate applies, and in your case, it is not taxable. However, if it is calculated under special rates, such as 12.5%, no rebate is applicable and thus taxable in your case.
Also see: Mutual Fund Taxation Ready Reckoner FY 2025-2026