While reading about living trusts and retirement planning, I came across a very important regulatory update from SEBI – one that directly affects how your investments are handled if you become temporarily or permanently unable to sign documents due to a physical condition.
About the author: Manmohan Sethumadhavan is a freelancer, investor, and personal finance enthusiast “in search of the absolute truth.” You can follow Manu on Twitter @ManuTsr. He is the author of the popular Revised Capital Gains Taxation Rules Ready Reckoner for FY 2025-2026.
On January 10, 2025, SEBI released a circular revising and revamping nomination facilities in the Indian securities market, followed by an amendment circular on February 28, 2025. Based on these, a common Standard Operating Procedure (SOP) for all Depositories and Mutual Fund AMCs has been introduced, detailing how accounts can be operated in case an investor becomes physically incapacitated but remains mentally competent to contract. These changes will come into effect from 15th December 2025.
Empowering a Nominee to Operate During Incapacitation
An investor can now authorise one of their registered nominees (other than a minor) to operate the account if the investor becomes physically incapacitated. This means that even when you cannot sign documents due to illness or accident, your investments can still be managed – redemptions, switches, or other transactions – through an “empowered nominee.”
However, this facility applies only if you are still mentally sound and capable of entering into a valid contract under the law. The provision covers both single-holder and joint-holder accounts. However, for joint accounts, the clause becomes active only when all joint holders are simultaneously incapacitated. So if even one holder remains capable of signing, the usual operation continues. In case of joint accounts with “joint” operation, where one investor alone becomes incapacitated, the new rule does not apply, and the operation would not be possible.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
The definition of incapacitation is quite specific. The investor should still have the capacity to enter into a contract as per section 11 of the Indian Contract Act, 1872. It covers only physical incapacitation – where the investor cannot sign due to illness or disability – but still has the mental capacity to understand and consent. People who are in a coma, unconscious, mentally unsound, or on life-support systems like ventilators do not fall within this category. In such cases, the operation of the account would follow legal procedures (such as court orders).
Investors are free to change nominees any number of times and may specify either a percentage or an absolute value of assets that the empowered nominee can encash. This limit is applicable to the investor at the PAN level in case of Mutual Funds, and for each demat account separately.
The process for implementation in an incapacitation
All this sounds like a welcome move and offers investors a sense of security. However, in practice, it may not be as simple as it appears on paper. The process of activating this facility involves several layers of verification, documentation, and in-person checks.
- When an investor becomes incapacitated, a written request must be sent to the AMC or Depository Participant (DP) informing them of the situation. This can be done either by the empowered nominee or by any other person. The request must be accompanied by a medical certificate from a qualified doctor stating the reason for and duration of the incapacity.
- After receiving the request, a responsible officer from the AMC or DP must personally visit the incapacitated investor to verify the condition. Video calls are not allowed – the verification must be in person. This is to prevent misuse or fraud.
- If the investor has not registered any nominee earlier, the incapacitated investor must first register a nominee and then assign that person as the “empowered nominee”, strictly under the presence of the officer. It’s a crucial clause since allowing someone to act on your behalf without proper verification could lead to serious misuse. Also, this is an area where collusion and fraud can happen.
- During the verification visit, the officer must obtain the thumb or toe impression (or any mark) of the investor. The officer also has to explain the implications of empowering the nominee to act on the investor’s behalf.
- An independent witness, unrelated to both the investor and the AMC/DP, must also sign the document confirming this act.
- Once all formalities are completed, the AMC or DP will take 48 hours (a cooling-off period) before allowing the empowered nominee to transact.
The empowered nominee cannot change the investor’s registered bank account. All redemptions or withdrawals during this period will be credited only to the original bank account linked to the folio or demat account. No other service requests – like bank change, email/mobile update, or address change – can be made by the nominee.
While the new rules are a welcome step that gives investors peace of mind, the process is not as simple as it sounds. Each step involves multiple verifications, documentation, and in-person checks to ensure safety and prevent fraud. In reality, this facility might take time to implement smoothly, especially for elderly investors or those living away from urban centres. The requirement of in-person visits and independent witnesses may cause delays in urgent situations.
This new framework is a thoughtful reform meant to protect investors and prevent misuse of their assets. However, it is not a replacement for an emergency fund or joint holding arrangement.
Investors are advised to:
- Add a joint holder (with “Either or Survivor” operation) for quicker access, or
- Plan alternate arrangements such as trusts or power of attorney, especially for long-term contingencies.
The intent is good – to make sure your money can be managed safely even when you physically can’t – but like many regulatory processes, the execution might not be quick or easy.
We are on Google News
Use this button to add freefincal.com as a preferred personal finance source on Google News.
Explore 1,400+ videos on YouTube!
Subscribe to get posts via email!
Join 32,000+ readers and get free money management solutions delivered to your inbox! (Link takes you to our email sign-up form)Join our WhatsApp Channel
Explore our products
🔥Join our community of 9000+ users! 🔥- Use our Robo-advisory Tool to create a complete financial plan! More than 3,500 investors and advisors use this! Use the discount code robo25 for 20% off. Plan your retirement (early, normal, before, and after), plus non-recurring financial goals (such as child education) and recurring financial goals (such as holidays and appliance purchases). The tool helps anyone aged 18 to 80 plan for retirement, plus six non-recurring and four recurring financial goals, with a detailed cash flow summary.
- Our Flagship Course! Learn to manage your portfolio like a pro to achieve your goals regardless of market conditions! More than 3,500 investors and advisors are part of our exclusive community! Get clarity on how to plan for your goals and achieve the necessary corpus no matter the market conditions! Watch the first lecture for free! One-time payment! No recurring fees! Lifelong access to videos! Reduce fear, uncertainty and doubt while investing! Learn how to plan for your goals before and after retirement with confidence.
- Join the freefincal investor circle! An exclusive space for investors, advisors, fintech employees and students to access financial planning and insurance tools, mutual fund and stock analysis tools, coding strategies and Excel macros for data extraction. 750+ members are now part of our investor circle.
- Increase your income by getting people to pay for your skills! More than 900 salaried employees, entrepreneurs and financial advisors are part of our exclusive community! Learn how to get people to pay for your skills! Whether you are a professional or small business owner seeking more clients through online visibility, or a salaried individual looking for side or passive income, we will show you how to do it by showcasing your skills and building a community that trusts and pays you. (Watch the 1st lecture for free). One-time payment! No recurring fees! Lifelong access to videos!
- Portfolio Tracker! Track your mutual funds and stock investments with our Google Sheet!
- We also publish monthly screeners for
Our Podcast: Let's Get Rich With Pattu
On Spotify: Let's Get RICH With PATTU! Every single Indian CAN grow their wealth! On Audible: Listen to the Let's Get Rich with Pattu Podcast
Listen to the Let's Get Rich With Pattu podcast on YouTube.
Now watch Let's Get Rich With Pattu தமிழில் (in Tamil)!About The Author
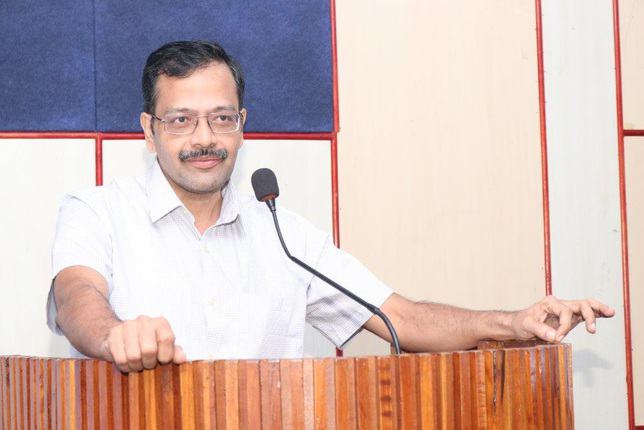
Dr M Pattabiraman giving a lecture
- Dr M. Pattabiraman (PhD) is the founder, managing editor and primary author of freefincal. He is an associate professor at the Indian Institute of Technology, Madras.
- He has over 14 years of experience publishing news analysis, research and financial product development. He has over 28 years of teaching and research experience. He is also a public speaker and keynote presenter.
- He is a patron and co-founder of “Fee-only India,” an organisation promoting unbiased, commission-free, AUM-independent investment advice.
- Connect with him via @pattufreefincal on X LinkedIn YouTube
- Pattabiraman has co-authored three print books.
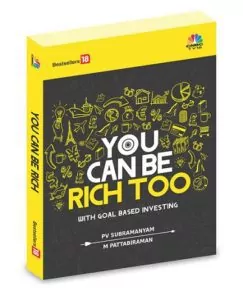
This book helps you ask the right questions and find the right answers. It also includes nine online calculators to create custom solutions.
(2) Gamechanger: Forget Startups, Join Corporate & Still Live the Rich Life You Want. 
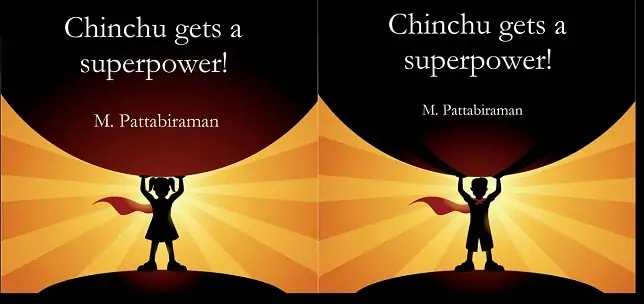
Both the boy and girl versions of "Chinchu Gets a Superpower".
Most investor problems stem from a lack of poor decision-making. We made bad decisions and money mistakes when we started earning, and we spent years undoing them. Why should our children go through the same pain? What is this book about? As parents, what if we had to groom one ability in our children that matters not only for money management and investing but for every aspect of life? My answer: Sound decision-making. So, in this book, we meet Chinchu, who is about to turn 10. The story follows what he wants for his birthday and how his parents plan it, while also teaching him key ideas about decision-making and money management. What readers say! 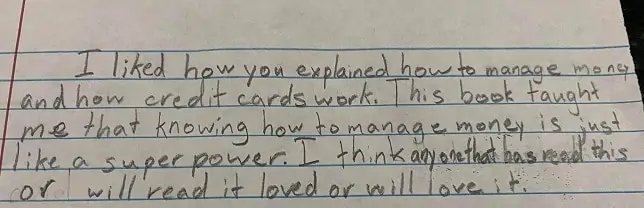
Feedback from a young reader after reading Chinchu Gets a Superpower!
Must-read book even for adults! This is something that every parent should teach their kids right from a young age. The importance of money management and decision-making based on their wants and needs. Very nicely written in simple terms. - Arun.
About freefincal & its content policy
Freefincal is a News Media organisation dedicated to providing original analysis, reports, reviews and insights on mutual funds, stocks, investing, retirement and personal finance developments. We do so without conflict of interest and bias. Follow us on Google News. Freefincal serves more than three million readers a year (5 million page views) with articles based only on factual information and detailed analysis by its authors. All statements made will be verified with credible and knowledgeable sources before publication. Freefincal does not publish paid articles, promotions, PR, satire or opinions without data. All opinions will be inferences backed by verifiable, reproducible evidence/data. Contact Information: To get in touch, please use our contact form. (Sponsored posts or paid collaborations will not be entertained.)Our publications
- Your Ultimate Guide to Travel. This is an in-depth exploration of vacation planning, including how to find affordable flights, budget accommodations, and practical travel tips. It also examines the benefits of travelling slowly, both financially and psychologically, with links to relevant web pages and guidance at every step. Get the PDF for Rs 300 (instant download)
- How to profit from content writing: Our ebook is for those interested in getting a side income via content writing. It is available at a 50% discount for Rs. 500 only!