A reader posed an interesting question: Suppose I wish to hold my entire retirement corpus as cash without investing it or saving it or buying pension or monthly income products, what will be the corpus required?
At a first glance, this may seem like a silly question. Yes, it is certainly impractical, but working this out leads us to a practical strategy that combines safety with prudence without going to extremes. So do bear with us.
We shall deliberately use a high inflation rate and practical return expectations to err on the side of caution. After all, life does not care if we used 6% as our inflation estimate.
We shall consider a 30-year old wanting to retire by age 50 and hoping to live until age 90. We shall assume 10% inflation each year before and after retirement. The only reason this inflation assumption is not practical is that the corpus required will be unattainably large by most. Retirement planning should be a mix of pragmatic and motivating assumptions!
In a real calculation, we recommend using 8% to 7% inflation before retirement to account for lifestyle creep (at least some of it) and 6% inflation after retirement.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Now, with 10% inflation and about Rs. 45,000 expenses each month that will continue in retirement, we shall find out the retirement corpus required if the entire amount is put into a current account after retirement (no return on corpus in the withdrawal phase).
At age 50, the person will need Rs. 36.23 lakhs for expenses in the first year of retirement. If we inflate this by 10% each year for the next 39 years and add all the annual expenses we get, (hang on to your chairs) a whopping Rs. 160.8 Crores!
That is if the person had accumulated Rs. 160.8 Crores by age 50 and put it all in the current account(s), he can simply withdraw from it until age 90 (assuming there are no huge unexpected one-time/recurring expenses.
Yes, I appreciate what you are thinking: “Why would anyone do that?! I will invest some portion of the corpus, save some portion and use some portion as income”.
Of course, we should deploy the corpus into various buckets. We have illustrated this many times before: I am 30 and wish to retire by 50 how should I plan my investments?
We punch in the above assumptions in the freefincal robo advisory tool along with a modest 10% return from equity (after-tax) and 6% return from fixed income after tax (remember this is the return at the time of retirement and beyond) and 5% return from an income bucket.
If we assume about 40% (43% to be exact*) is deployed in equity and the rest in fixed income and the money is divided among four buckets – an income bucket, a low-risk bucket, a medium risk bucket and a high-risk bucket, the corpus required reduces from Rs. 160 Crores to …. (can you guess?)
For more details on the above retirement bucket strategy, see Retirement plan review: Am I on track to retire by 50? * The robo tool recommends equity allocation after retirement depending on the inflation and the return assumptions made. The 43% equity exposure may seem large to older readers (and perhaps too little to younger readers!) but this is linked with the inflation assumption of 10%. If we assume 7% inflation before retirement and 6% after, the equity allocation post-retirement drops to about 30%.
Now getting back, did you guess how much corpus is? It is about Rs. 22 crores (remember with 10% inflation). That is a reduction of about 86%. Instead of keeping the money idle for about three decades, investing some of it and saving some of it makes a huge difference to what is needed at the time of retirement and therefore the amount necessary for investing.
If we reduce the inflation estimate to 7% before retirement and 6% after, the corpus further reduces to Rs. 6.6 Crores. Even with the reasonably sedate return expectations used (which are kept unchanged), the monthly investment is about Rs. 50,000 but increasing at the rate of 10% each year. This investment includes the mandatory EPF or NPS deductions made by an employer.
There is a go-between strategy, which combines the safety of the 160 crores approach without overdoing it and the prudence of the bucket strategy. This is known as the income flooring approach.
Here, we take the estimated annual expense in the first year of retirement (let us call it X) and assume we purchase an annuity with a part of the retirement corpus such that X is the annual pension payout for life.
For example, with 7% inflation before retirement, Rs. 45,000 a month at age 30 will increase to Rs. 174,136 a month at 50 or Rs. 20.8 lakhs a year in the first year of retirement.
Assuming a post-tax annuity rate of 4%, the corpus required to provide an annual pension of Rs. 208 lakhs is Rs. 522 lakhs (approximately). We then subtract Rs. 20.8 lakhs from the expected expenses in the remaining years and find out the corpus required. This is shown schematically below. Please note that expenses are expected to increase by 6% after retirement. For more details see: Creating the “ideal” retirement plan with income flooring!
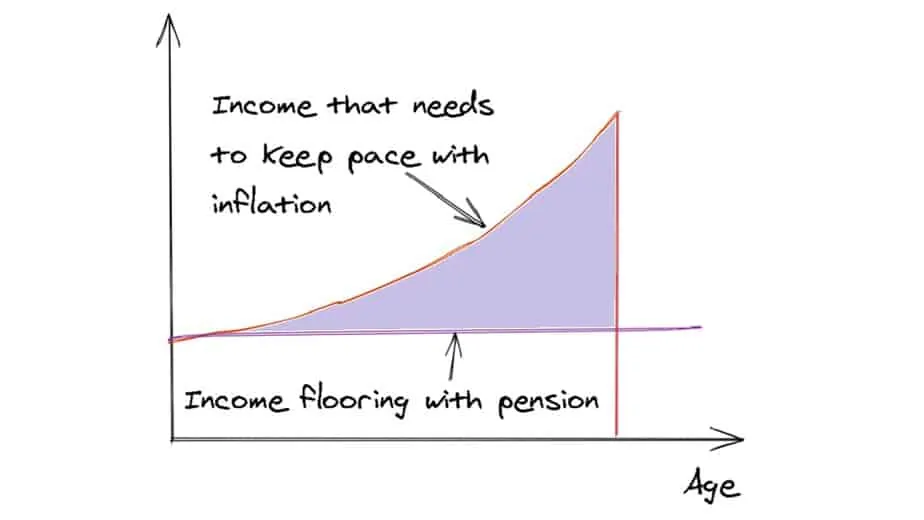
With an income flooring assumption (plus buckets), the corpus (computed with the robo tool) increases to Rs. 8.66 Crores a 31% increase if we only had buckets. The investment required increases from Rs. 50,000 to Rs. 66,000 increasing at the rate of 10% each year.
Is income flooring necessary? The answer depends on our risk appetite, our capital market experience and most importantly the amount we can invest. If a 30-35% increase in investment can easily be handled then there is no harm in considering income flooring. It will only reduce the risk of using retirement buckets.
Income flooring is one of my retirement goals. Since I have a mandatory NPS and have to annuitize at least 40% of the corpus, I might as well set the pension as my guaranteed income floor.