Let us discuss a retirement plan for a 28-year-old who wishes to retire by age 50. These are the following inputs and assumptions used in the retirement calculation.
Age 28; Retirement age 50; Life expectancy age 90; Monthly expenses Rs. 40,000; Current corpus is practically zero; Inflation before retirement: 7% and after retirement 6%, Return expectation 7% from EPF and 10% from equity. Increase in monthly investment each year: 10%
Let us now do the calculation using the freefincal robo advisor tool with the following modifications (remaining assumptions stay the same):
The retirement corpus required is Rs. 6.16 Crores, and the monthly investment required is Rs. 33,750, increasing each year at 10%. The recommended change in asset allocation and the corresponding change in overall portfolio return are shown below.
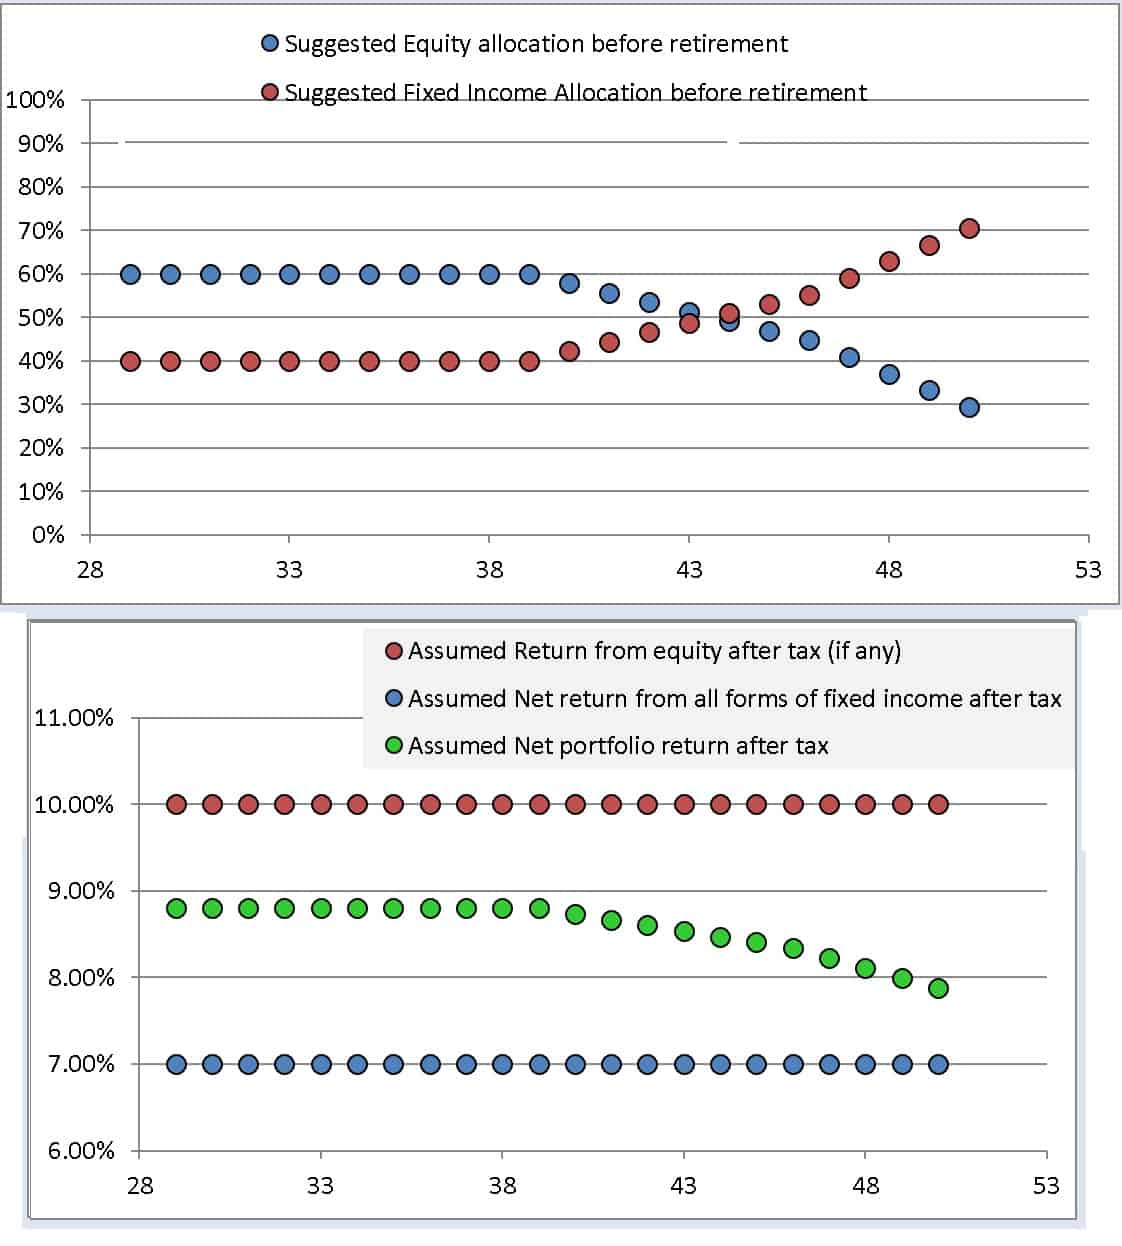
The equity allocation is gradually reduced from an initial 60% equity to 29% at age 50.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Even though the equity allocation reduces, the initial investment required is reasonable because of the assumed 10% increase in investments each year. This is possible with regular income hikes, bonuses and promotions.
How do we invest the retirement corpus?
Of the total corpus of Rs. 6.16 crores, 5% is kept aside for emergencies. Of the remaining corpus, 29% is set aside for equity; the rest is fixed income distributed among four buckets.
- An income bucket with 47% of the remaining corpus for guaranteed income for the first 15 years of retirement. During this time, investments will be made in the following three buckets.
- A low-risk bucket with 24% of the remaining corpus for income from year 16 to year 25 in retirement. The low-risk bucket will have an asset allocation of 30% equity and 70% debt during the investment period (years 1 to 15 of retirement).
- Corpus from a medium risk bucket with 15% of the remaining corpus will provide income from years 26 to 33 in retirement. This bucket shall have an asset allocation of 50% equity and 50% debt during the investment period (year 1 to year 25)
- Corpus from a high-risk bucket with 8% of the remaining corpus will provide income from years 34 to 40 in retirement. This bucket shall have an asset allocation of 70% equity and 30% debt during the investment period (year 1 to year 33)
- The buckets will be actively managed to reduce risk during this investment period via rebalancing and profit booking from one bucket to another. To understand how this works, try The Retirement Bucket Strategy Simulator.
- After 15 years, the low-risk bucket will be turned into 100% debt and provide income for about ten years. After that, the other buckets will also be progressively used.
The 28-year-old should be on track to retire by age 50 if he can stick to the above-mentioned investment schedule.