Last Updated on October 1, 2023 at 5:41 pm
Here are some less-understood facts about the National Pension Scheme (NPS).
- National Pension Scheme comes with no guarantees of returns.
- NPS is a mutual fund and carries with it all the risks associated with any old mutual fund. Read more: NPS investments are mutual fund investments!
- The aim of NPS is to generate a corpus and not provide a pension.
- When it is time to withdraw (after age 60), the subscriber should take the corpus generated (40% minimum) and buy an annuity (pension) from any of the designated annuity providers like LIC, SBI, ICICI, HDFC and Star Union. Details here: Annuity Service Providers
- The annuity provider will offer a pension at the annuity rates applicable at the time of purchase. There is no special annuity rate for the NPS, or at least there need not be (and is not at the time of writing)!
- Anyone with a big enough sum can purchase these annuities from the insurers. An NPS account is not necessary! This is point the title conveys. It is not NPS that provides the Pension. The annuity provider does – which they would for any individual whether they are NPS subscribers or not. NPS is only a means to obtain a retirement nest egg. There are other ways to obtain a much healthier corpus with a lot more efficiency.
- Can I open an account to invest only 50,000 under 80CC1(B) and invest elsewhere for 80C deductions? Yes, as long as you open, the govt. will be happy!
- Where can I find information about the returns generated by various pension fund managers? Here: Return of NPS Schemes
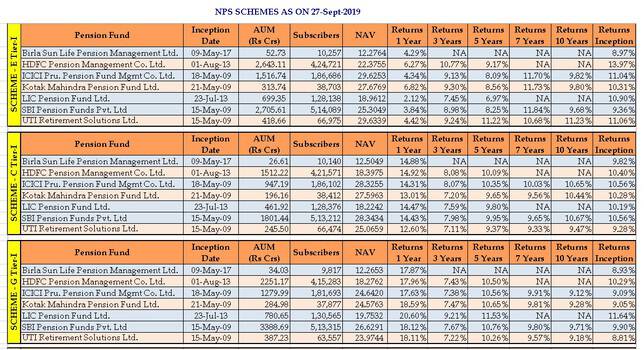
- Where can I find portfolio details of each scheme? Here: Portfolio of NPS Schemes
- Can I invest online? Yes, but beware of processing charges. Read more (including comments): How to make online contributions to NPS Tier I and Tier II accounts
- Is tier II eligible for tax benefit? Only for central govt servants within 80C
- How do I estimate the pension I will receive from NPS? You can only estimate the corpus you will receive using any standard SIP calculator. You can then use that corpus to find out the pension with current annuity rates (before tax as per slab!) NPS Calculator: How the National Pension Scheme works
- My employer wants me to shift to NPS from EPF. Is it a good idea? In EPF you get the entire corpus tax-free whenever you retire (hopefully well before 60). In NPS you need to annuitize 80% of the corpus if you withdraw before 60! It is a trap! Read more: Stay away from Corporate NPS, if You Wish to Retire ASAP!
With inputs from Facebook group, Asan Ideas for Wealth.
Update 2: NPS: Partial Withdrawal Rules 2019 are just awful! Beware.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈