A reader says, “You have repeatedly demonstrated how to deploy a retirement corpus into different buckets using the freefincal robo advisory tool. In all these examples, you assume the retiree will have or should have enough money in a safe income bucket to handle inflation-indexed expenses for the first 15 years of retirement. I find this condition quite restrictive. Is it possible to create a custom retirement bucket strategy using the robo tool?”
These are some of the illustrations mentioned by the reader:
- Retirement plan review: Am I on track to retire by 50?
- Am I on track to achieve financial independence in the next 13 years?
- I am 30 and wish to retire by 50; how should I plan my investments?
- When can I stop worrying about managing my retirement corpus and leave a legacy?
What is a retirement bucket strategy? We have seen how our parents and grandparents manage their money after retirement. For most of them, a pension would be the main component. The remaining corpus would be distributed among senior citizen saving schemes, PMVVY, monthly income schemes, fixed deposits etc.
The main purpose is to obtain constant income after retirement with some liquidity to handle small emergencies. Most of them did not have enough corpus to try and fight inflation – that is, an increase in day-to-day expenses – after retirement. More details can be found here: How to create retirement buckets for inflation-protected income.
The primary thumb rule we follow in our robo advisory template is the retiree should have enough money to generate inflation-proof income for the first 15 years of retirement. If this is not available, creating a bucket strategy is quite risky. A few years of poor market returns, especially in the first few years of retirement, can wipe out much of the corpus. Thus 15 years is ample cushion to reasonably handle a poor return sequence.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Can we create a custom retirement bucket strategy using the freefincal robo advisory tool?
Yes, of course! However, we strongly recommend that you don’t because the 15-year window is based on extensive backtesting with Indian and US markets, with some cushion to account for future market downturns. Most of our 1000+ investor and advisor userbase are happy with this 15-year cushion.
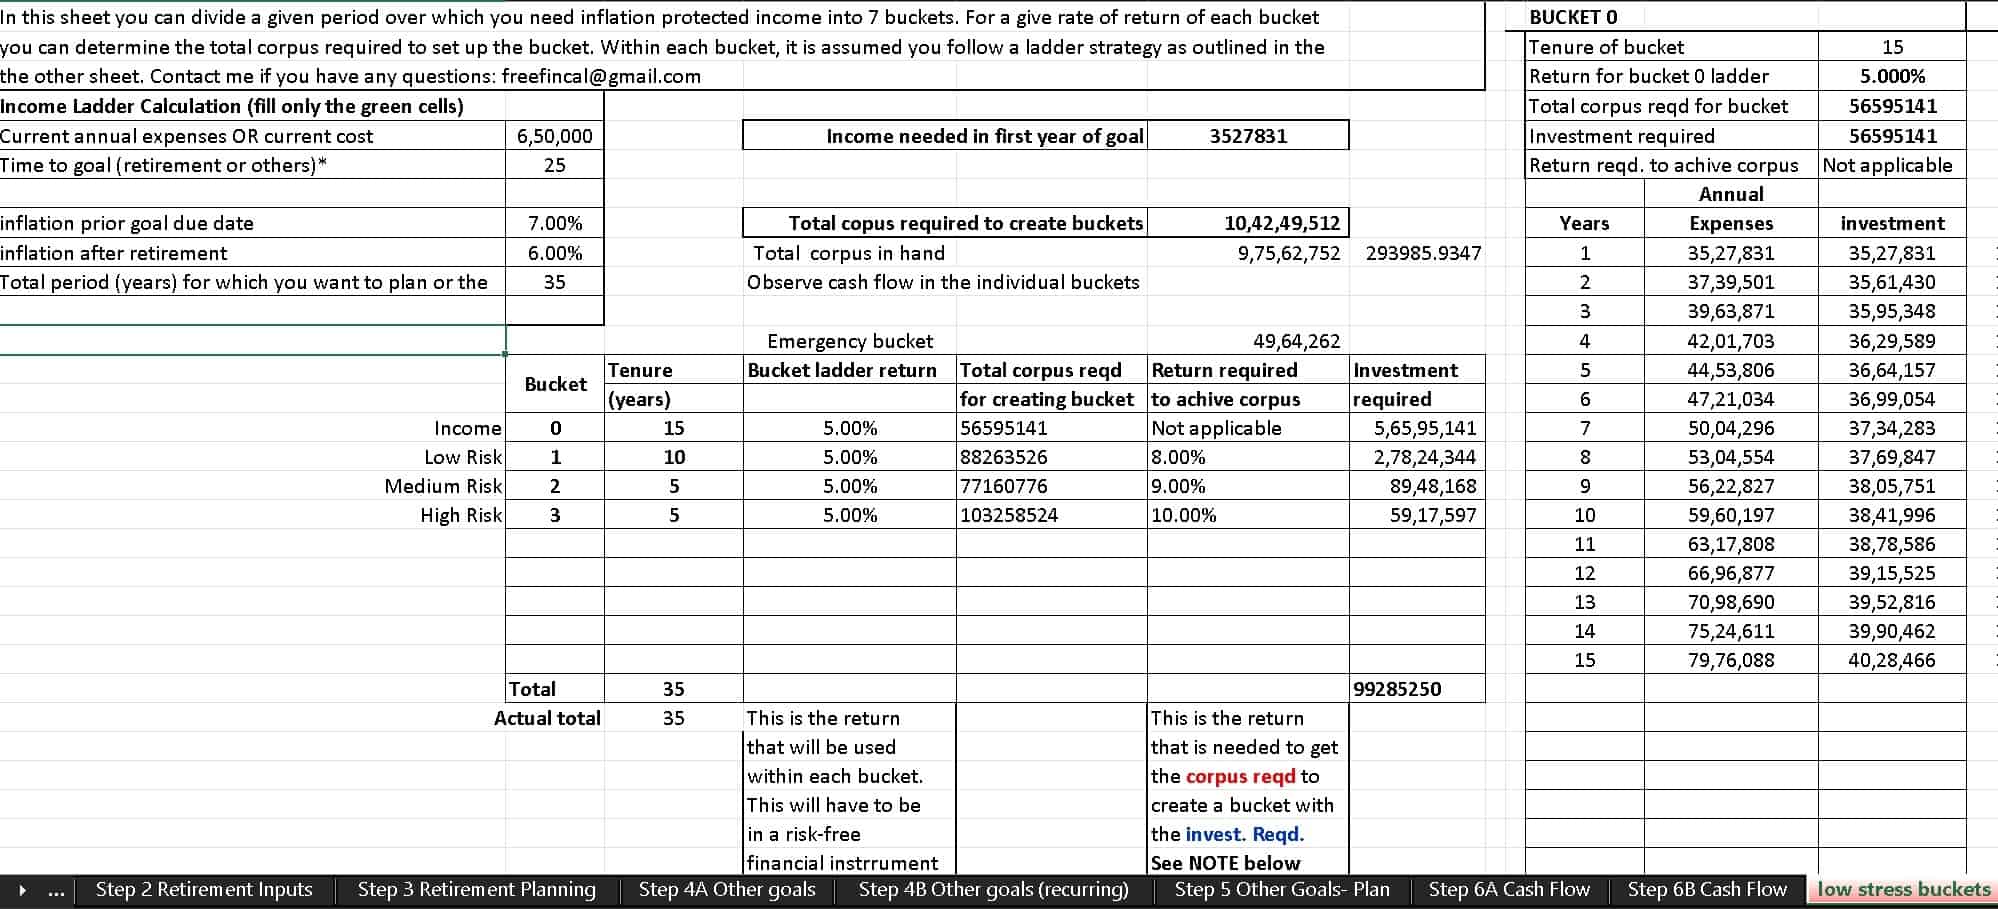
However, if you insist on modifications, then it is certainly possible. The robo tool is completely open-source, and the user can modify all settings. This is a screenshot of the bucket strategy sheet.
This is a screenshot of the setting page. The area encircled in red sets the bucket durations. These are typically not entry cells and have formulae. If you wish to create a truly DIY bucket strategy, you can change these entries to suit your needs.
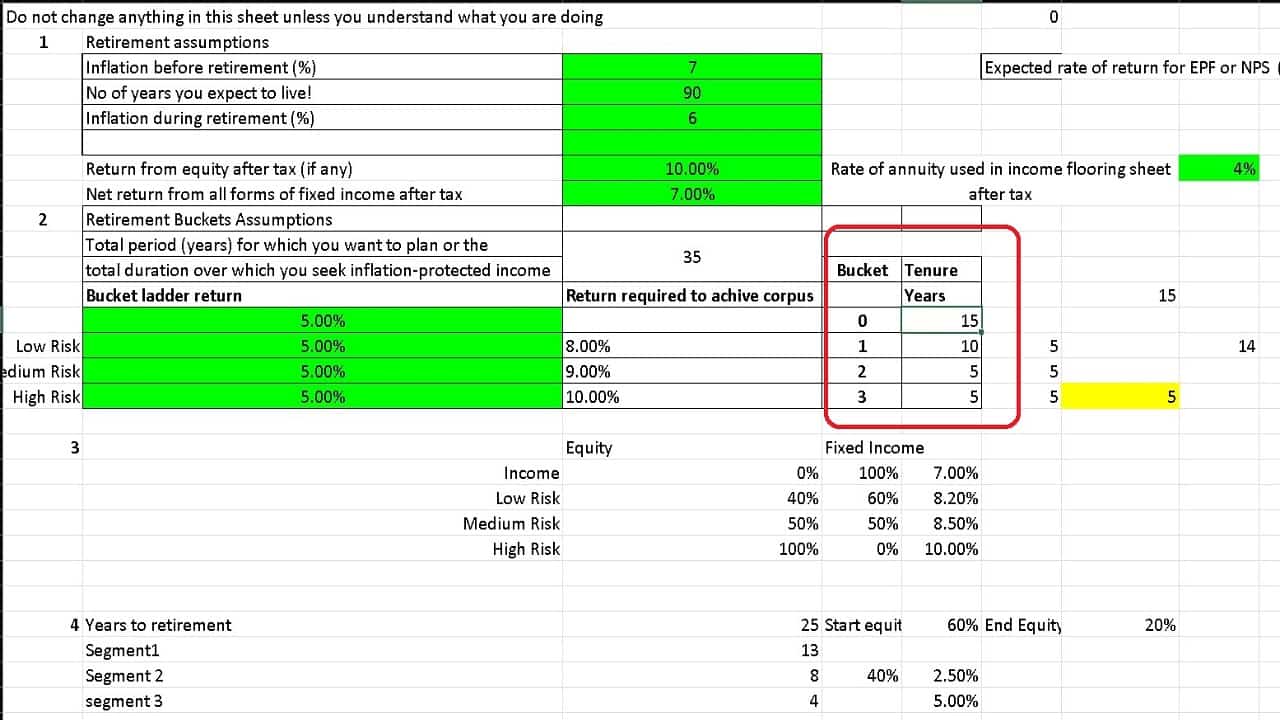
However, remember that the sum of the encircled “tenure in years” cells should add to the years you expect to spend in retirement.
In summary, although the freefincal robo advisory tool can be used to create a custom DIY retirement bucket strategy, we strongly recommend against it unless you are an experienced investor or advisor.