A reader says. “I live with my mother, and I am 52. However, I have a corpus of only one crore invested in equity. I retired in 2019 as vice president. My monthly expenses are 30k. Is my corpus enough?” This was in response to “How much do I need to retire in 2024?”.
Let us compute this using the freefincal robo advisor tool. This provides an accurate estimate compared to approximate calculations using spreadsheet formulae. The robo tool can also include three post-retirement income streams. It also offers suggestions on how to invest the corpus. The robo tool offers risk management advice for those far from retirement with a variable asset allocation schedule. See an example: I am 30 and wish to retire by 50; how should I plan my investments?
Please note: I am running the numbers based on the reader’s email. A monthly expense of only Rs. 30K seems quite low. Also, you will have to account for your mother’s health insurance and healthcare costs. Since we do not have details on this, we do not address it here. We shall only ask and answer the limited question if a Rs. One Crore corpus is enough if monthly expenses are Rs 30K.
First, we check if the corpus is enough to create a robust retirement.
The retirement corpus is assumed to be invested in five buckets. It is important to recognize that the figures below are only an illustration. The robo tool’s output is influenced by numerous factors. Therefore, do not extend these numbers or percentages to your circumstances without conducting a comprehensive retirement planning analysis.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
- An emergency bucket to handle unexpected expenses about 5%: Say Rs. 5 Lakhs
- An income bucket provides guaranteed income for the first 15 years of retirement. About 56% of the remaining corpus, or Rs. 58 lakhs, is invested here. There is no equity exposure in this bucket.
- During this time (first 15 years), investments are made in three buckets: low-risk, medium-risk, and high-risk.
- The buckets will be actively managed to reduce risk: rebalancing and profit booking from one bucket to another. To understand how this works, try The Retirement Bucket Strategy Simulator.
- After 15 years, the low-risk bucket will be turned into 100% debt and provide income for about ten years. After that, the other buckets will also be progressively used.
- Alternatively, one can manage the buckets so that at all times, 15 years of expenses are always available in the income bucket.
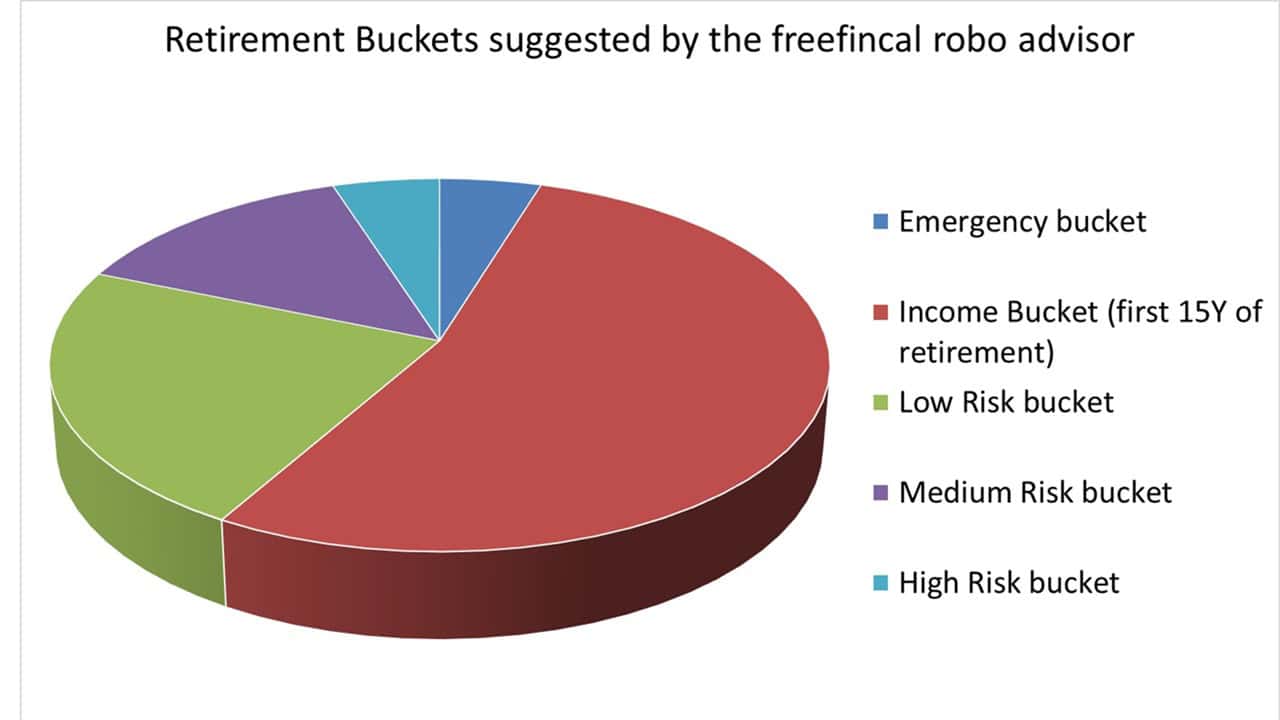
Details of the other buckets are given below.
- Corpus is from a low-risk bucket that provides retirement income from year 16 to year 25. To provide this income, the low-risk bucket will have an asset allocation of 30% equity and 70% debt during the investment period (years 1 to 15 of retirement). About 24% or Rs. 25 lakhs is invested here.
- Corpus from a medium-risk bucket will provide retirement income from years 26 to 33. To provide this income, this bucket shall have an asset allocation of 50% equity and 50% debt during the investment period (year 1 to year 26). About 14% or Rs. 15 lakhs is invested here.
- Corpus from a high-risk bucket will provide retirement income from years 34 to 38. To provide this income, this bucket shall have an asset allocation of 70% equity and 30% debt during the investment period (year 1 to year 34). About 5% or Rs. 5.5 lakhs is invested here.
The overall equity exposure is only 26%, excluding the emergency bucket; therefore, it is reasonably safe. The inflation assumed is 6%, the expected post-tax return from equity is 10%, and the expected post-tax return from fixed income is 5% (for bucket investments). All these numbers can be varied by the user on the settings page of the robo-advisor tool.
The total corpus is Rs. 108.5 Lakhs. Since the shortfall is only 8.5 lakhs, I think it is manageable. However, as mentioned above, we have only answered a limited question. There are other important factors to be considered by the retiree. We recommend finding a source of gainful employment, full-time, part-time, freelancing, consultancy, etc.