A reader asks, “Our daughter is five months old. How should we start investing for her future?” It is always best to start planning on a clean slate before making any investment. Let’s dive straight into the goal-planning steps.
The goal-planning steps
- We need a target corpus after 17/18 years, depending on when she was born. That is after school graduation.
- Let us first set the target corpus = UG fee. The corpus can easily be enhanced to include a PG or other expenses. A UG fee of Rs. 1.5 lakh per semester x eight semesters + a joining fee of Rs. 5 lakhs + another Rs. 5 lakhs for relocation, travel, etc. Please make enquiries to set a target.
- So that is about Rs. 22 lakhs. Make that Rs. 25 lakhs as the current cost. That is, if your child were to enter a four-year UG program today, that is what it would cost approximately.
- What is the likely cost for your child after 17/18 years, as the case would be when we start planning?
- We will use inflation of 10%-12%.
- At 10% inflation, the corpus will be about Rs. 1.25 crores after 17 years.
- Suppose the parents can invest Rs. X each month for this goal. About 50-60% of X should be invested in stocks or equity mutual funds, assuming a post-tax return of 10% from equity. A good calculator can compute this X; see point 12 below.
- The remaining amount can be invested in debt instruments with a return of about 6%. Remember, this is not the return you will get next year. This is the return you expect after 17 years.
- But which debt instruments? We recommend PPF and debt funds. SSY (Sukanya Yoana can also be used, but it is more suited for marriage expenses and not a college education). Also see Sukanya Samriddhi Yojana vs PPF: An Illustration.
- The debt funds depend on your comfort level with the bond market. By increasing NAV volatility, our recommendations are Money market funds < Edelweiss Short Duration Index Fund <= Corporate Bond Funds <=Parag Parikh Conservative Hybrid Fund <= Gilt Funds.
- The above-mentioned future target corpus is only for UG education. If you wish to include her PG education expenses, marriage expenses, etc., you can suitably inflate the above corpus and continue investing in it beyond school.
- What is more important is asset allocation after we start investing. We cannot hold on to 50% or 60% for most of the journey. A string of poor returns will upset our plans. Entering the above details into our robo advisory tool, we get 60% equity for 7-8 years and then gradually taper down to 0% for the rest of the journey. Many goal calculators input a single future return expectation to compute the monthly investment required. This is incorrect, as the asset allocation will vary and affect the required investment amount.
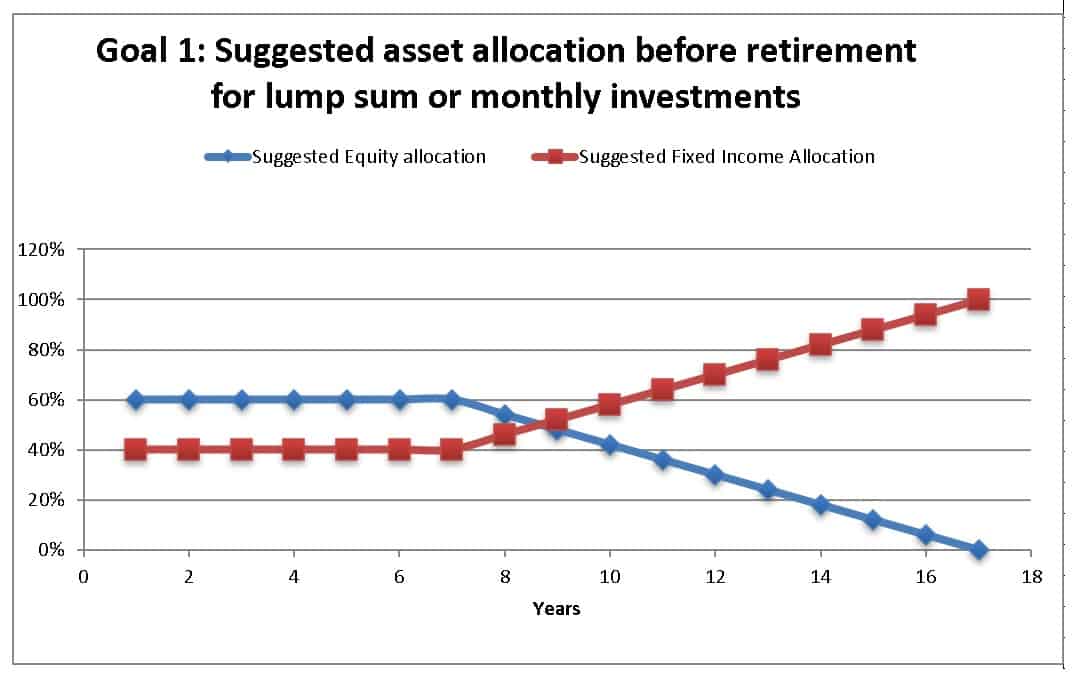
The suggested asset allocation by the freefincal robo advisory template for a child’s college education that is 17 years away. - With this variable asset allocation, the total monthly investment required in the first year of investing is Rs. 15,500. Each year after this, the investment should be increased by 10%.
- Do not rush to invest Rs. 1.5L a year in PPF (or SSY) just because it is tax-free with a guaranteed return. In the above plan, the total investment in debt will only be Rs. 74 K. Until the equity allocation starts decreasing, as mentioned above, the debt investment will not exceed Rs. 1.5 L a year. After this, a debt mutual fund may be added to accommodate the higher debt investment.
- The above calculation should be repeated each year with updated inputs and assumptions.
All the best!
For other illustrations, see:
- I am 30 and wish to retire by 50; how should I plan my investments?
- Retirement plan review: Am I on track to retire by 50?