A reader says, “This concerns the required retirement corpus and whether I am on the right track. I am 32 years old, my spouse is 26, and both are working (private jobs and no job security). I wish to retire by age 45. How should I plan, and what is the corpus required?”
“Current retirement saving: EPF – 10 Lakh, Equity – 10 Lakh. Yet to reach the 70:30 allocation (as all my EPF was fully loaded initially, and thank God I catch up at least with 50 50 in two years)”
“Monthly expense: 35000, Annual expense (health insurance/Bills/Bike insurance etc): 1 Lakh. Since a newborn entered our life last month, I can now invest for my retirement 40,000, and the EPF contribution of both myself and my wife is 18,252; hence, a total of 58,252 contributed to my retirement monthly, and I am not sure whether it is sufficient”.
“Based on my retirement calculation plan, the corpus is around ten crores, and the monthly investment is around 130000. Whether am I making any mistakes?”
By “retirement”, I assume you refer to quitting a salaried existence and pursuing your passions with security and flexibility. It does not mean cessation of gainful employment, as many people incorrectly presume.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Let us punch these numbers into the freefincal robo advisor and find out.
Note: This retirement planning illustration depends on several inputs and assumptions. Not all of them are shown here. The individual must change these inputs and assumptions according to their circumstances. Please do not use these illustrations as a framework or copy these numbers for personal use without a proper calculation.
These are the inputs and assumptions from the freefincal robo tool.
- Current monthly expenses that will persist in retirement: 35,000
- Annual expenses that will persist in retirement 1,00,000
- Your age at the end of the current year is 32
- Age you wish to retire 45
- Years to retirement 13
- Total average monthly expenses (annual/12) 43,333
- Percentage by which your monthly investments can increase each year (until you have accumulated enough for retirement): 5%
- Post-tax return expected from equity investments % 10.00
- Post-tax return expected from current taxable fixed income % 6.50
- Rate of return expected from current tax-free fixed income % 7.50
- Value of current equity investments ( stocks and equity mutual funds) 10,00,000
- Total Value of current tax-free fixed income investments (PPF + EPF etc.) 10,00,000
- Inflation before retirement (%) 7
- Assumed life expectancy of younger spouse 90
- Inflation during retirement (%) 6
- Years to retirement 13
- Monthly expenses in first year of retirement: 1,04,427
- Years in retirement (until younger spouse reaches age 90) 51
- Do you want to use the income flooring option? No, See: Use this annuity ladder calculator to plan for retirement with multiple pension streams
- Target Corpus: 4,92,08,418 (Rs. 4.92 Crores)
- If we account for the growth of the existing corpus, the amount to be accumulated is about Rs. 4.32 Crores. This corpus calculation considers a bucket strategy explained here: Can I retire at 47 with Rs. 5.7 Crores?
Suggested equity and fixed income allocation before retirement by the freefincal robo advisor tool
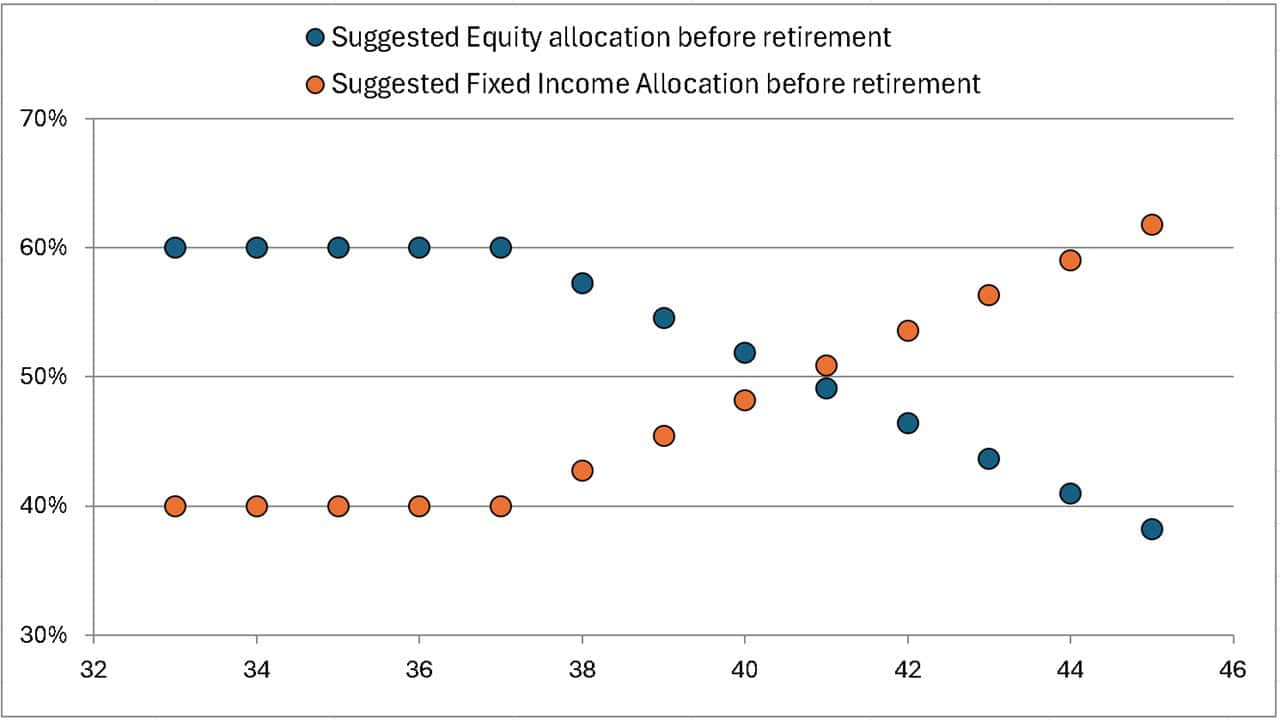
With the above inputs and assumptions, it is necessary to calculate Rs. 1.15 Lakhs, including total EPF contributions each month.
So yes, your calculations (aside from differences in assumptions) are correct. You may not be able to retire by 45 as the investment required is nearly twice what you invest today. Increase your income and postpone your retirement plan by at least 5-10 years. For your current investment levels (assuming they increase by 5% a year), you can afford to retire close to 55.
Do not get disheartened by this result. That is how a retirement planning calculation will be for most folk. Put your head down and invest without expectations. Review your plan each year. Hopefully, you will get there by 50 or so. I wish you all the best.