Last Updated on October 1, 2023 at 5:56 pm
Use this annuity ladder calculator to find out how to beat inflation after retirement using multiple income streams. We all appreciate the importance of a secure income (pension) after retirement. However, inflation also has to be factored in.
The primary requirement for fighting expenses increasing in retirement is a robust corpus. To accumulate this, we need to invest each month an amount at least equal to our monthly expenses (excluding school fees, EMIs, and expenses for parents and kids). More on this in another article.
Our focus here is, on how we manage money after retirement to generate inflation-protected income. That is, how can we increase our income each year in retirement by 6% (or any rate which represents inflation).
The most efficient way to do this is via a well-diversified retirement portfolio consisting of fixed income and equity investments, pension products, dividend income, passive income and passionate gainful employment. See: Building the ideal retirement portfolio that goes beyond money.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
There are two extreme options in retirement planning: one where the corpus is managed in a diversified portfolio and an increasing income is withdrawn from it as required. This is known as the bucket strategy.
We had earlier illustrated how to plan for retirement with such a strategy: I am 30 and wish to retire by 50 how should I plan my investments? And, Retirement plan review: Am I on track to retire by 50?
The second extreme option is to use pensions or annuities or secure fixed income products. As one can imagine, this will guarantee a fixed income for life but increasing the income each year or as required at the rate of inflation would be hard.
The main advantage of using a bucket strategy is a lower retirement corpus. Although it is not hard to implement, many retirees (particularly those with little or no capital market experience) feel it is difficult to do so. Therefore, we had earlier discussed a hybrid strategy using retirement buckers and a pension plan called income flooring: How to beat inflation after retirement along with guaranteed pension. This option was also incorporated into our robo advisory tool.
Income flooring reduces the corpus that needs to be managed in buckets but increases the retirement corpus. In an earlier article, we showed How to use income laddering with annuities to plan for retirement.
This annuity ladder calculator has now been incorporated as a stand-alone module in our robo advisory tool (existing users have already been sent the latest version). Kindly ensure the email “pattu {AT} freefincal {dot} com” is included in your contact list so that it is not sent to spam.
The annuity ladder calculator exploits the fact that insurance annuities aka immediate pension plans offer higher rates when the age of entry is higher. So we can buy a new pension plan every 10 years or so in retirement.
For new readers, this is the full series of articles leading up to the multiple annuity illustration:
- Part 1: What are the annuity rates of LIC Jeevan Akshay VII from Feb 2022?
- Part 2: How LIC annuity rates have changed over the last 20 years
- Part 3: I need a pension: Should I buy an annuity or a govt bond?
- Part 4: How can I use my corpus to get a pension at the best return?
- Part 5: How to use income laddering with annuities to plan for retirement
Naturally, the trade-off is a much higher retirement corpus. Considering the various inputs and assumptions that go into the calculation, we strongly recommend that investors far away from retirement should NOT use the annuity laddering calculator module. It is only for those who have just retired or are on the verge of retirement with a large enough corpus.
It is important to recognise that annuity laddering does not eliminate retirement corpus management in buckets. It only makes it simpler. As mentioned it comes with a price – a much higher corpus. So it is not suitable for everyone.
This is a screenshot of the annuity ladder calculator module from the freefincal robo advisory template. The expenses are increasing at a defined rate of inflation. Each step shows an annuity purchased every 10 years.
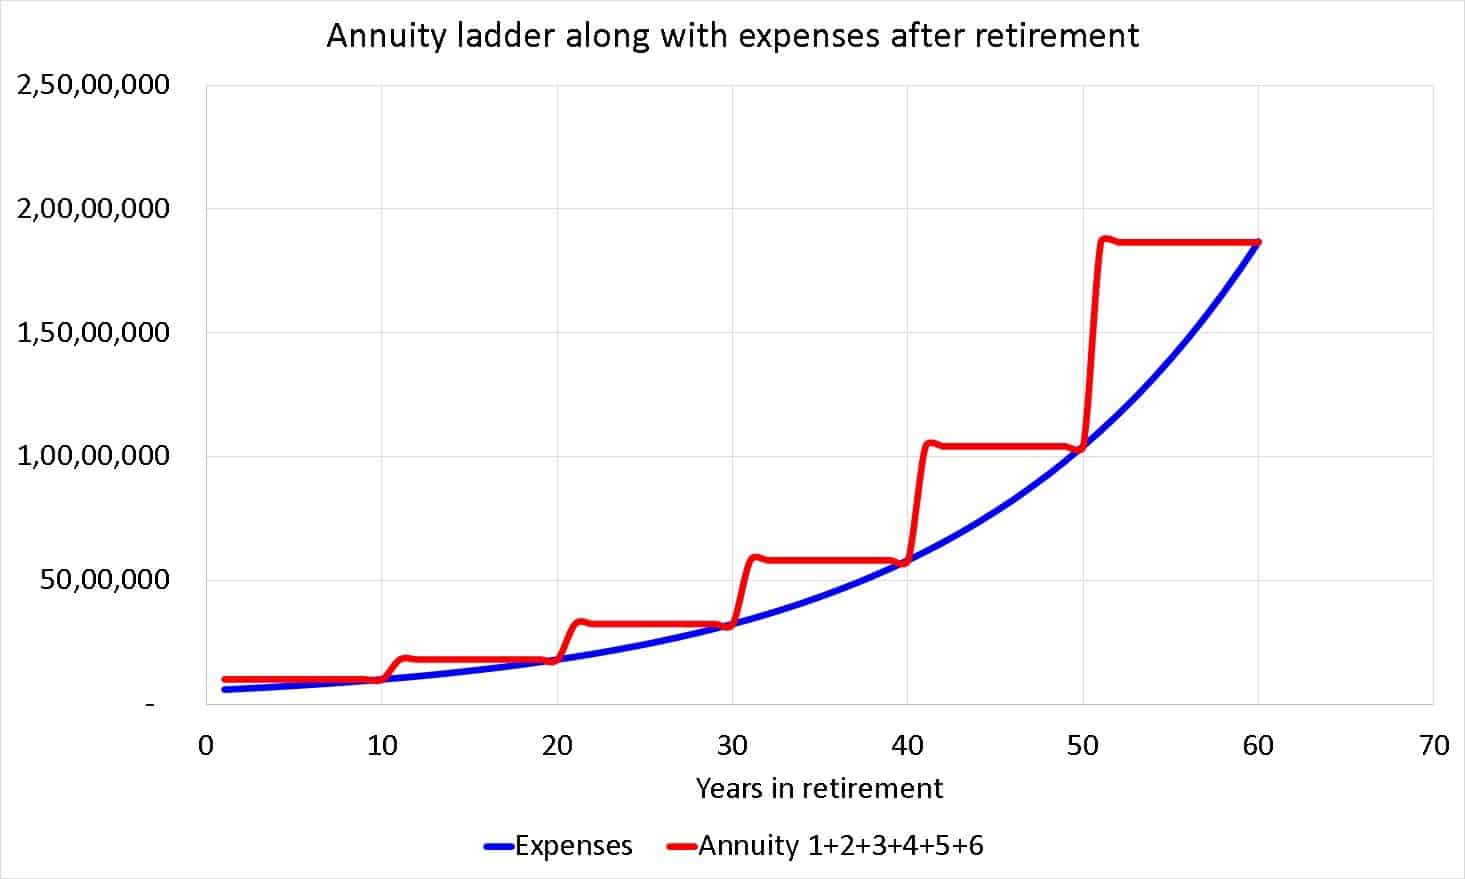
The example below is an extreme case of 60 years in retirement (this can happen if a spouse is much younger. The robo tool plans for retirement up to age 90 of the younger spouse).
As one can see from the above picture, the annuity purchased each years is done in such a way that the sum of annuities is always above or equal to the inflation-adjusted expenses.
Here are some screenshots that explain how the annuity laddering calculator works.
The current annuity rate inputs are depreciated by a tax rate and by 1% per year to account for lower annuities in future. These settings can be changed at will by the user as the robo tool is open-source.
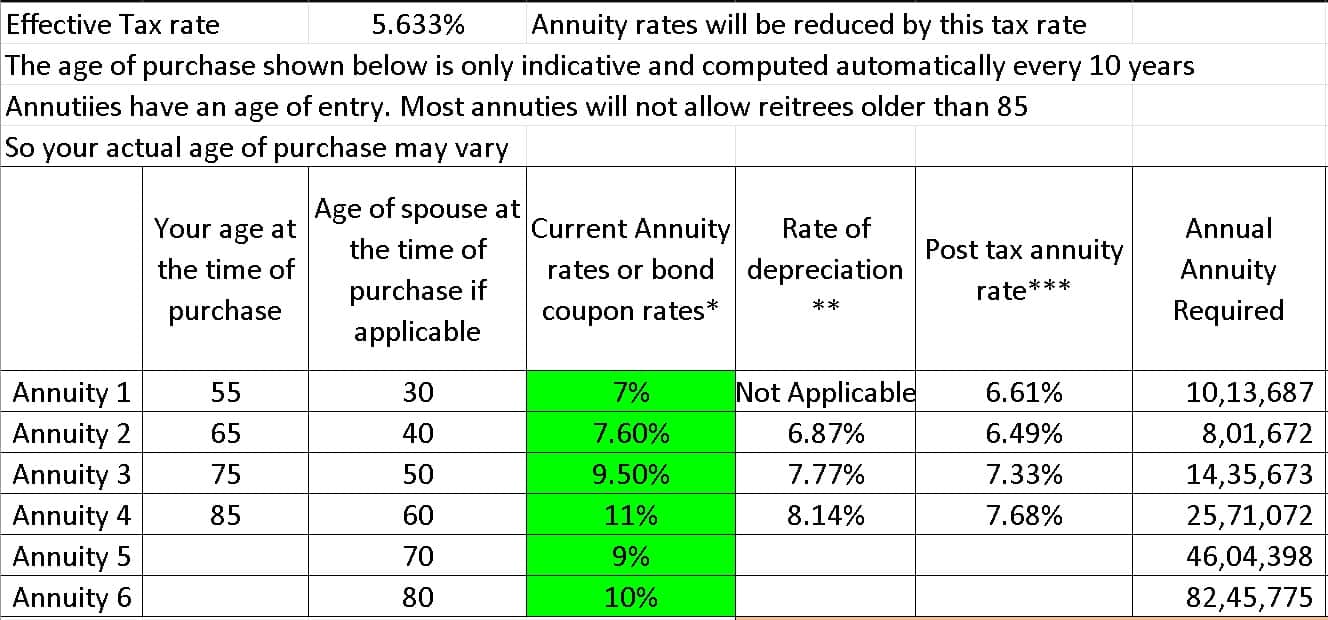
Out of the six annuities shown (typical retirement scenarios would only need about 3-4). only the first one will be immediately purchased. The remaining will be done after 10Y, 20Y, 30Y and so on. So there is ample time for an investment to grow into the amount required for the future purchase.
The investment can be made in a mix of equity and fixed-income investments. The key difference between annuity laddering and a pure bucket strategy is:
- Bucketing requires multiple buckets (at least mentally) to ensure the sequence of returns risk is mitigated. The investment for annuity laddering can be done in a single equity + fixed income bucket with withdrawals made every decade or so since the multiple annuities account for a big chunk of risk management. The equity allocation should not be high in both cases.
- Annuity laddering is well suited for retirement planning of super senior citizens (75+) when they may have difficulties with a bucket strategy.
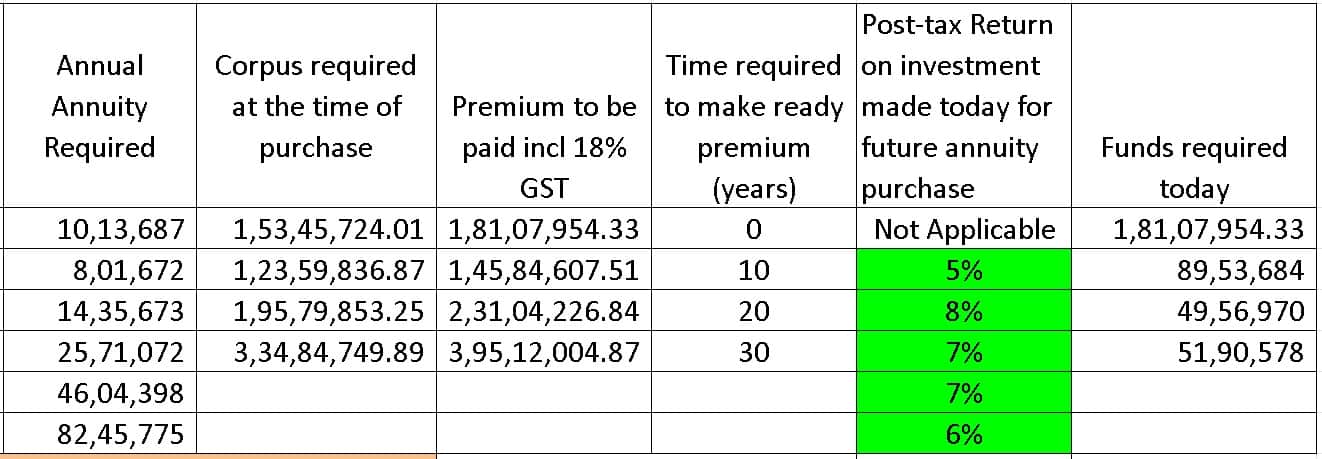
In the next step, the current investment necessary for future annuity purchases (incl GST!) is computed. The (post-tax) returns can be adjusted at will. We recommend being conservative.
Finally, the corpus required is computed after ensuring an ample sum is kept aside for emergencies.
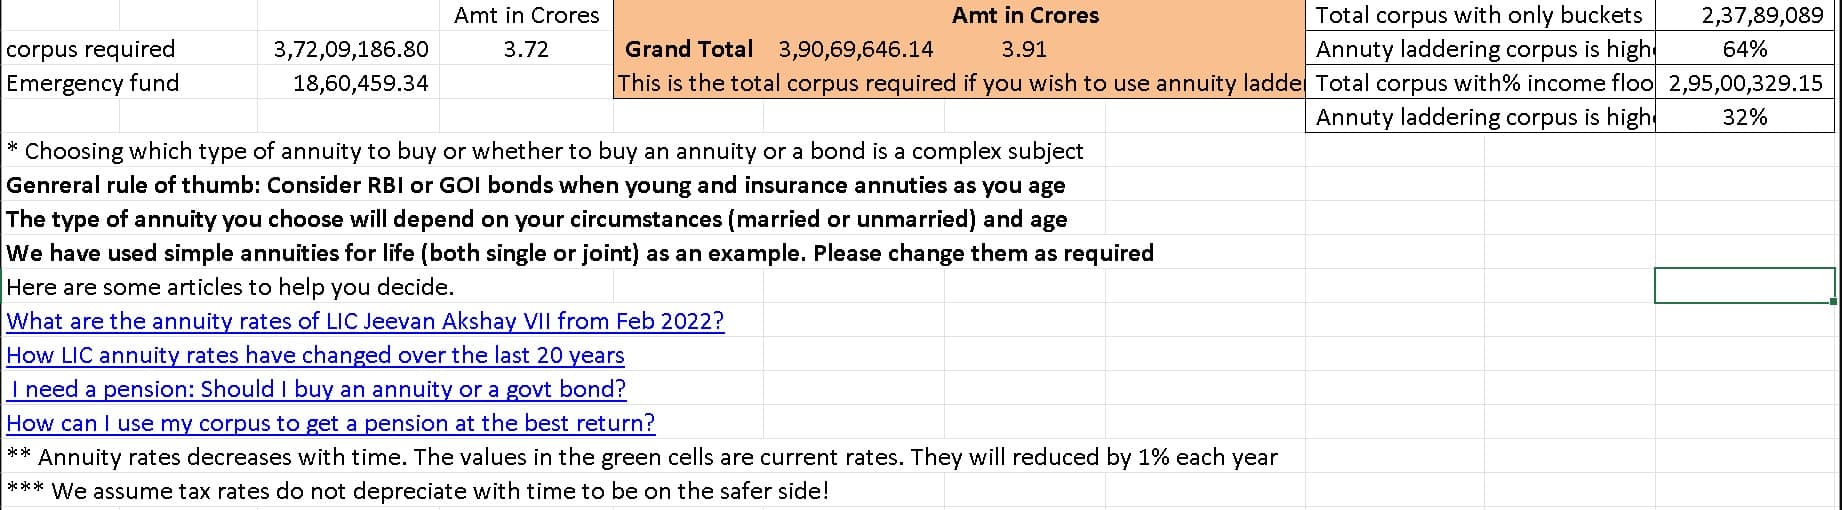
The annuity laddering corpus is compared with the income flooring corpus and the bucket strategy corpus. Unfortunately, the annuity laddering corpus is considerably higher. So it is suitable only for this with a robust retirement corpus. This is why we recommend that this option be considered only close to retirement or at an advanced age.
How to get the robo advisory tool with income flooring and annuity laddering modules?
- Existing users: All future updates are free, and the latest version was sent by email on May 16th. If you have not received it, please let me know via the email used to purchase the sheet.
- New users: Get our flagship robo advisory tool for Rs. 5160 only. One-time purchase; lifetime access! All future feature updates are included! For a full list of features, see the video guides below.
Other features of the robo tool can be seen in these video guides.