Last Updated on October 2, 2023 at 9:26 am
In this article, we list the annuity rates of LIC’s Jeevan Akshay VII (Plan No. 857, UIN : 512N337V02) launched in Feb 2022. While preparing a retirement planning illustration based on laddered annuities we wanted to find the latest Jeevan Akshay VII annuity rates. Unfortunately, neither the sales brochure nor the policy document mentions this!
Other sources on the web still list annuity rates for the Jeevan Akshay VII (Plan No. 857, UIN: 512N337V01) policy which was withdrawn 1st Feb 2022. Therefore we thought it best to use LIC’s online premium calculator and list the annuity rate ourselves. To avoid confusion, we shall refer to the new policy as LIC’s Jeevan Akshay VII (Feb 2022)
We shall follow this up with historical Jeevan Akshay annuity rates (no I to no VII) and then move on to our ultimate goal of retirement planning with laddered annuities.
LIC’s Jeevan Akshay VII (Feb 2022) is a Non-Linked, Non-Participating,
Individual Immediate Annuity Plan. Non-linked means not linked to market movements. Non-participating means the policyholder will not get a slice of the insurer’s profits via bonuses or dividends. An immediate annuity plan means the income (annuity) will commence immediately upon purchase.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
There are multiple options to receive the annuity. We shall list the rates for the options in bold.
Option A: Immediate Annuity for life.
Option B: Immediate Annuity with a guaranteed period of 5
years and life thereafter.
Option C: Immediate Annuity with a guaranteed period of 10
years and life thereafter.
Option D: Immediate Annuity with a guaranteed period of 15
years and life thereafter.
Option E: Immediate Annuity with a guaranteed period of 20
years and life thereafter.
Option F: Immediate Annuity for life with return of Purchase
Price.
Option G: Immediate Annuity for life increasing at a simple
rate of 3% p.a.
Option H: Joint Life Immediate Annuity for life with a provision
for 50% of the annuity to the Secondary Annuitant
on the death of the Primary Annuitant.
Option I: Joint Life Immediate Annuity for life with a provision
for 100% of the annuity payable as long as one of
the Annuitant survives.
Option J: Joint Life Immediate Annuity for life with a provision
for 100% of the annuity payable as long as one of
the Annuitant survives and the return of Purchase Price
on the death of the last survivor
The option that looks most beneficial to us is least beneficial to the insurer and therefore the annuity rate will be lower. For example, in option A, the insurer gets to pocket the purchase price on the death of the annuitant. Whereas in option F the insurer will have to return the purchase price to the nominee.
So they would offer a terrible interest rate (annuity rate) on option F and the best rate for option A! For all options other than A, the rate will drop quick and fast!
In option G, the income increases each year by 3%. If the annuitant is old, (55 or above) this has a higher rate than option F. Because older people are likely to die sooner and the insurer with option F has to repay sooner!
Annuity rates dramatically increase with age because older people need not be paid for long! This is the underlying principle behind laddering annuities (more on this in the coming days). We shall also study the time value of money for these options. To learn more see: How Annuity Plans Work. Also see: When should senior citizens purchase an annuity?
Purchase price less than Rs. 1.5 lakh (it cannot be lower than 1 lakh) will have lower annuity rates!!
Minimum Age at Entry: 30 years (completed)
iv. Maximum Age at Entry: 85 years (completed) except for Option F
100 years (completed) for Option F.
Joint Life: The joint-life annuity can be taken between any two
lineal descendants/ascendants of a family (i.e. Grandparent, Parent,
Children, Grandchildren) or spouse or siblings. The second annuitant must be aged 30 or above.
Annuity Rates of LIC Jeevan Akshay VII from Feb 2022
The image below shows the rates for different options at different ages. For joint like (cols E and F), the spouse is assumed to be 5Y younger except for age 30 when they are assumed to be of the same age. The data is also presented option-wise below.
The numbers correspond to the annual payout only. Other payout options will have lower annuity!!
For example, a 47-year-old opting for “annuity for life” will Rs. 10 lakhs will receive an annual payout of Rs. 69,250; a half-yearly payout of Rs. 33,975 (x 2 = 67950 less than the annual payout or annual rate of only 6.795%).
The quarterly payout is Rs. 16,825 corresponding to a rate of only 6.73%. The monthly payout is Rs. 5,571 corresponding to a rate of 6.68%.
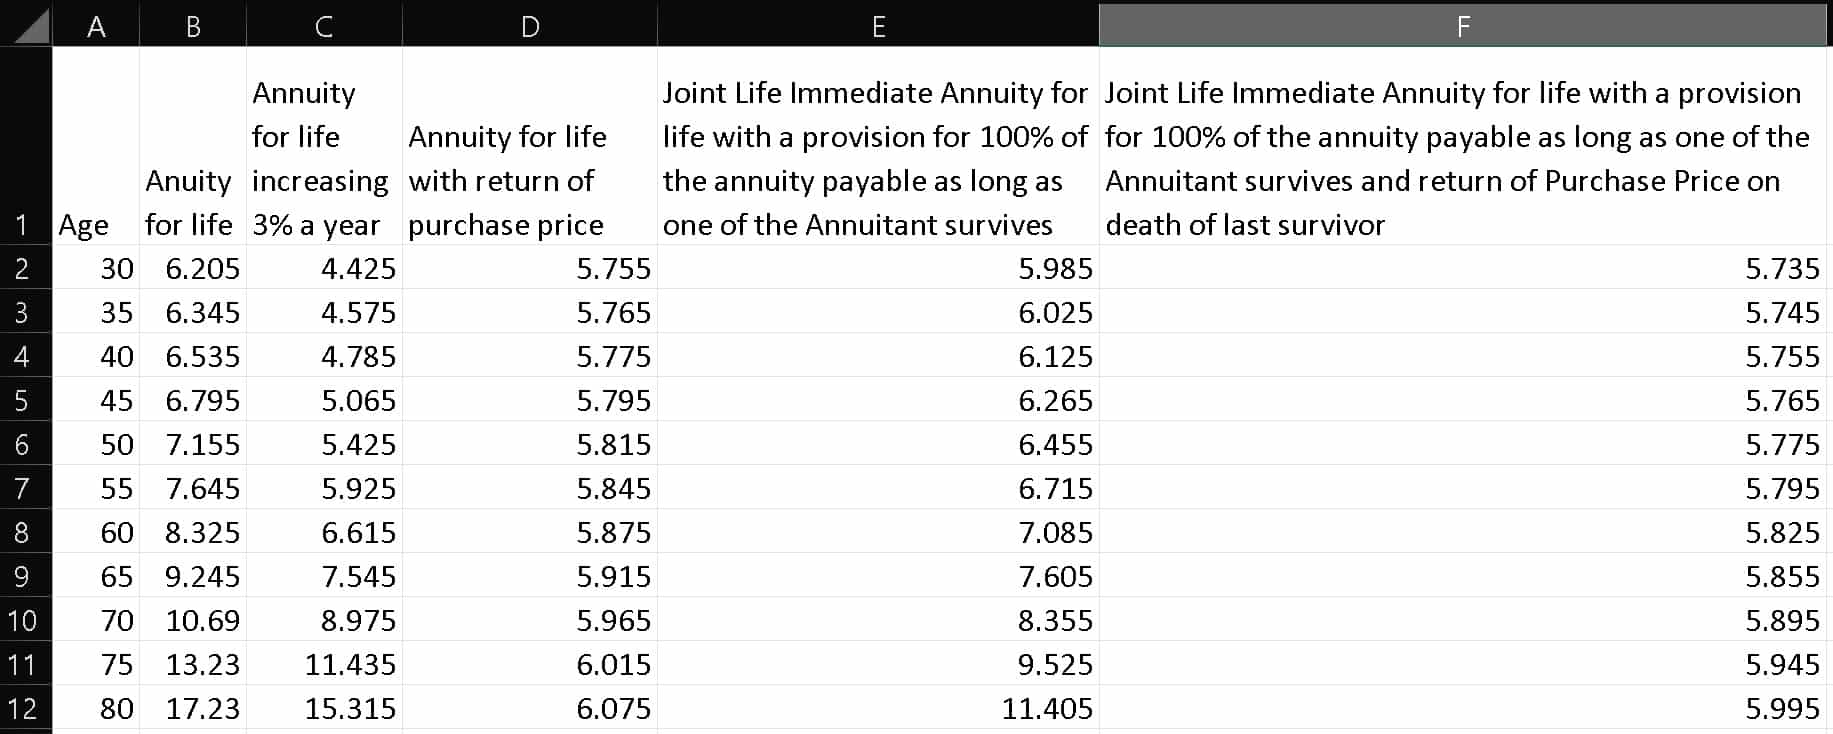
Notice that younger retirees might get a better deal if they buy govt bonds (although this is not guaranteed income for life and could be recalled by the govt). See an example: How I used RBI Retail Direct to buy govt. bonds and create an income source. Also see:
- RBI Retail Direct: A look inside: how to register and what you can buy/sell
- RBI Retail Direct for govt bonds: Who should use it and who should not
LIC’s Jeevan Akshay VII (Feb 2022) Rates for Annuity for life
| Age | Annuity for life |
| 30 | 6.205 |
| 35 | 6.345 |
| 40 | 6.535 |
| 45 | 6.795 |
| 50 | 7.155 |
| 55 | 7.645 |
| 60 | 8.325 |
| 65 | 9.245 |
| 70 | 10.69 |
| 75 | 13.23 |
| 80 | 17.23 |
LIC’s Jeevan Akshay VII (Feb 2022) Rates for Annuity for life increasing 3% a year
| Age | Annuity for life increasing 3% a year |
| 30 | 4.425 |
| 35 | 4.575 |
| 40 | 4.785 |
| 45 | 5.065 |
| 50 | 5.425 |
| 55 | 5.925 |
| 60 | 6.615 |
| 65 | 7.545 |
| 70 | 8.975 |
| 75 | 11.435 |
| 80 | 15.315 |
LIC’s Jeevan Akshay VII (Feb 2022) Rates for Annuity for life with return of purchase price
| Age | Annuity for life with return of purchase price |
| 30 | 5.755 |
| 35 | 5.765 |
| 40 | 5.775 |
| 45 | 5.795 |
| 50 | 5.815 |
| 55 | 5.845 |
| 60 | 5.875 |
| 65 | 5.915 |
| 70 | 5.965 |
| 75 | 6.015 |
| 80 | 6.075 |
LIC’s Jeevan Akshay VII (Feb 2022) Rates for Joint Life Immediate Annuity for life with a provision for 100% of the annuity payable as long as one of the Annuitant survives
| Age | Joint Life Immediate Annuity for life with a provision for 100% of the annuity payable as long as one of the Annuitant survives |
| 30 | 5.985 |
| 35 | 6.025 |
| 40 | 6.125 |
| 45 | 6.265 |
| 50 | 6.455 |
| 55 | 6.715 |
| 60 | 7.085 |
| 65 | 7.605 |
| 70 | 8.355 |
| 75 | 9.525 |
| 80 | 11.405 |
LIC’s Jeevan Akshay VII (Feb 2022) Rates for Joint Life Immediate Annuity for life with a provision for 100% of the annuity payable as long as one of the Annuitant survives and return of Purchase Price on death of last survivor
| Age | Joint Life Immediate Annuity for life with a provision for 100% of the annuity payable as long as one of the Annuitant survives and return of Purchase Price on death of last survivor |
| 30 | 5.735 |
| 35 | 5.745 |
| 40 | 5.755 |
| 45 | 5.765 |
| 50 | 5.775 |
| 55 | 5.795 |
| 60 | 5.825 |
| 65 | 5.855 |
| 70 | 5.895 |
| 75 | 5.945 |
| 80 | 5.995 |