Last Updated on May 2, 2022 at 7:48 pm
In this article, Anand Vaidya shares his experience of using the RBI Retail Direct portal to buy govt. bonds (gilts) and create an income source.
About the author: Anand studied E&C Engg, worked at Wipro and then left for a job in Singapore. He started his own IT consultancy in Singapore. After 15 years, he returned to India in 2011 and continued the same IT services co. He forced himself to retire in 2022 (hopefully, the corpus accumulated is good enough 🙂 ) and is now planning to focus on other interests in life (Travelling, Gardening, reading books, investing etc)
WARNING! This is post is written by a retiree who wants a source of income. Do not buy these bonds looking at the int rate if you don’t want an income.
Liquidity is low for these bonds and you will not be able to sell them in the secondary market! CONTEXT MATTERS!
I have been thinking of creating a “base income” (call it a pension, if you will) that will yield a fixed “reasonable” income for decades. I am interested in 7%-8% range products lasting at least 2 decades
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
It MUST be secure. That leaves only Central Gov bonds. Until now, I have only purchased NCDs or Tax-free bonds as a long term fixed income alternative to FDs. (Most are in the 8.8%-9.9% range with Gov, AAA, AA)
Recently the government has opened up the Government Securities for purchase directly from RBI/Gov to ordinary citizens. Until now only institutions were allowed to buy such gov bonds.
This is my experience of selecting and buying one such issue. First a few basic things.
- Should you buy such bonds in the first place?
- Create an RBI Retail Direct account first. This is very well explained in this freefincal article: RBI Retail Direct: A look inside – how to register and what you can buy/sell
Please add a joint E or S holder, and/or at least a nominee without fail.
Note that the following types of bonds are available:
Central Gov bonds (CG)
State Gov bonds (SG)
Central Gov Treasury Bills (T-BILL)
Sovereign Gold Bond (SGB)
Each category may offer multiple bonds with varying duration (a few days to few decades), varying interest rates from floating rate to 6%+
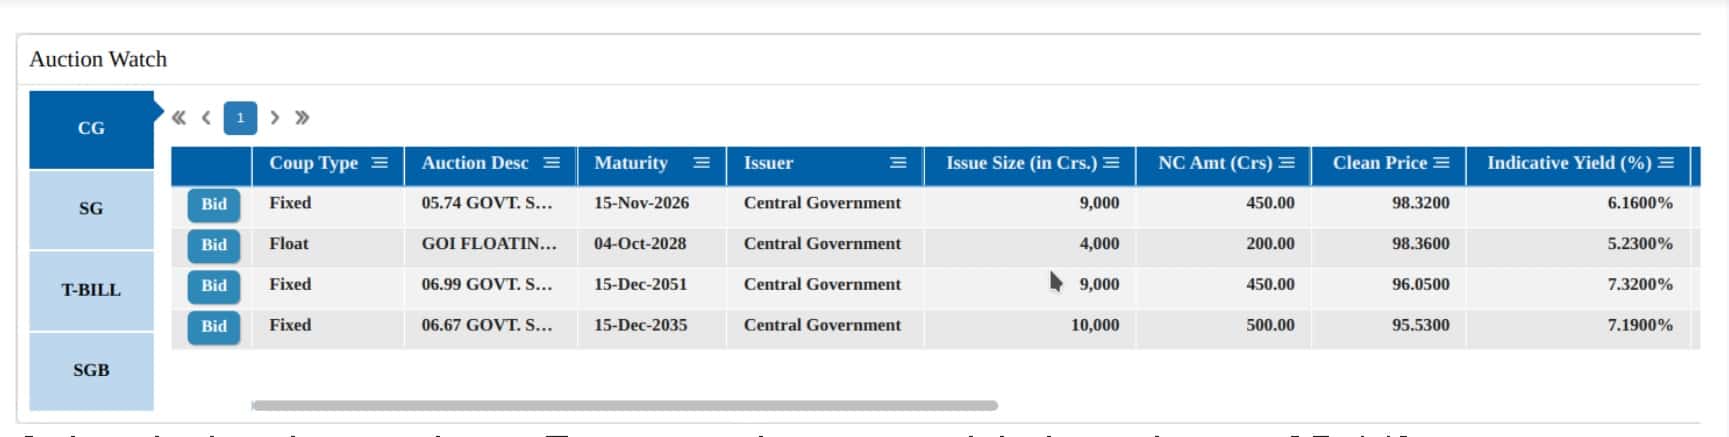
Select the bond to purchase. Ensure you have enough balance in your SB A/C.
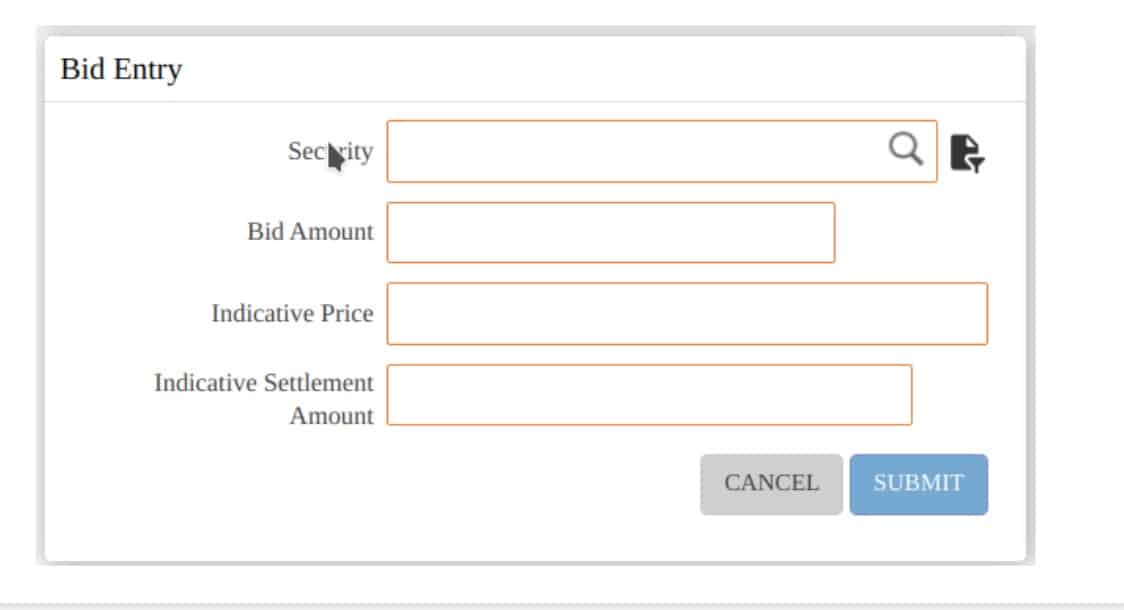
Fill in the Bid Entry form, and continue to payment. Pay the amount as indicated via net banking. A bank account with a high net banking transaction limit is good to have (10-20 lakhs per day).
The bid is immediately shown in the My Bids Tab.
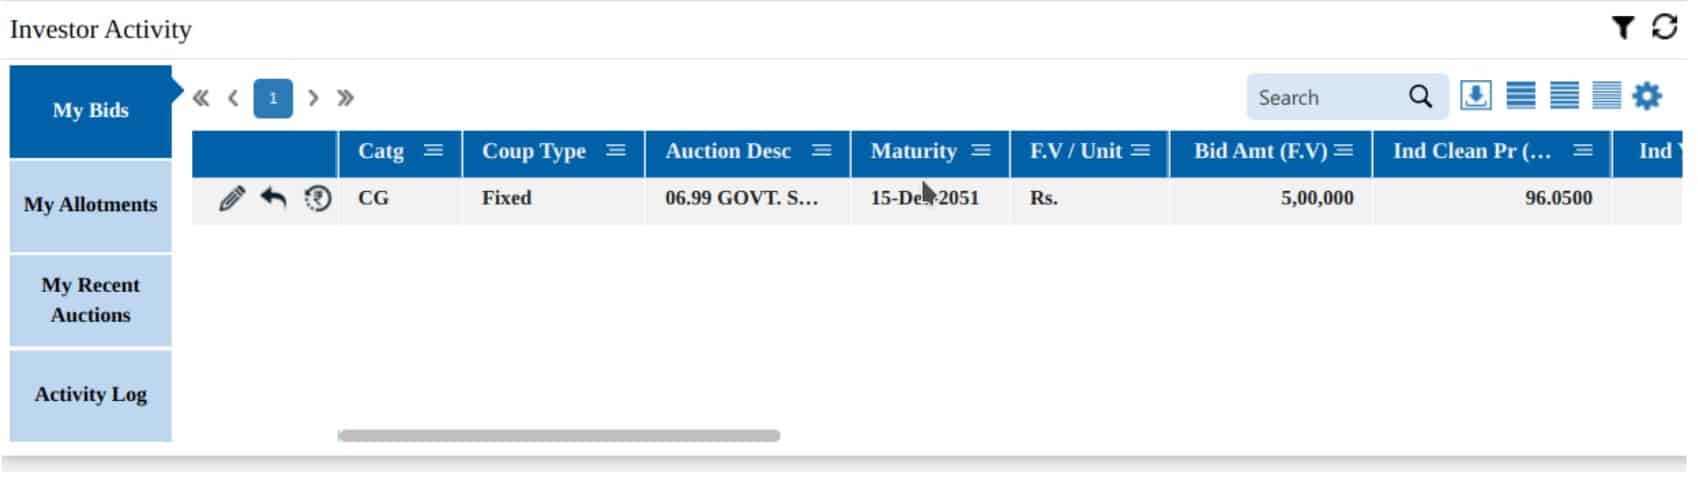
I had selected 6.99% Gov Security maturing in 2051, I wished to buy maximum of Rs 5L or 5000 bonds of Rs 100 face value each.
I Applied and paid Rs 516511.67 on 6/Apr/2022. The Allotment date was set as 8/Apr/2022. The additional 16511.67 was displayed as “Clean Consideration + AI + Markup. AI here stands for accrued interest which has to be paid by the buyer when we buy the bond mid-term.
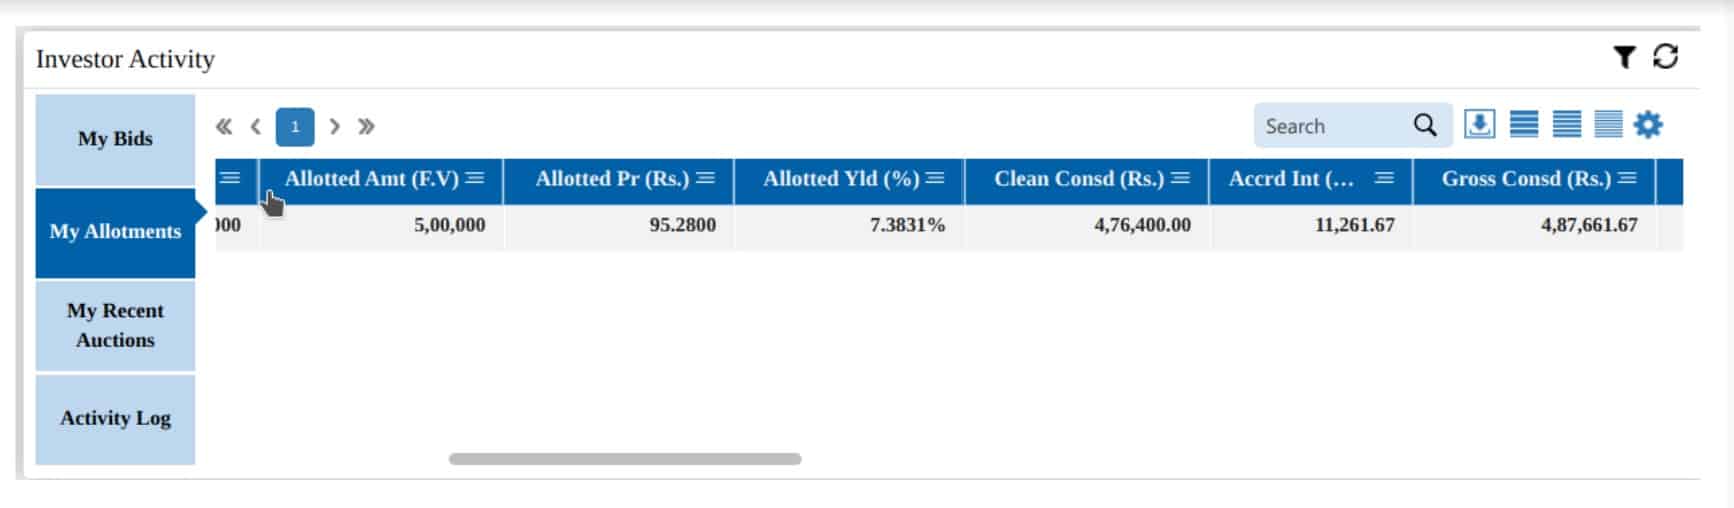
On the 8th evening, CCIL informed me via SMS that my bid was successful. However, the purchase price was Rs 95.28 instead of Rs 100 per bond and hence I was charged only Rs 4,76,400 (5000*95.28). They also indicated Rs 11261.67 as Accrued interest.
Hence an amount equal to 516511.67 – 4,76,400 – 11261.67 = Rs 28850 was refunded by 6 pm!
The yield to maturity= 7.38% which is not bad, compared to bank FD at 5%-5.5%
The details are available in the “My Allotments” tab.
| Maturity | ’12/2051 |
| Coupon Rate | 6.99% |
| Applied | 06-04-2022 |
| Allotted | 08-04-2022 |
| Listed BSE | 11-04-2022 |
| Bonds Applied (A) | 5,000.00 |
| Face value (B) | 100 |
| Cost (C= A*B) | 5,00,000.00 |
| AI+Markup (D) | 16,511.67 |
| Total Paid,pre-allotment (E= C+D) | 5,16,511.67 |
- Summary:
A very easy, straightforward method to buy gov bonds. Really well implemented. The only quibble is the bad fonts they have selected for the website and the excessive L-R scrolling - It all “just works” including refunds. Unexpected surprise for a gov agency
- I was lucky enough to get a 7.38% RoI for the next few decades.
- I will try to buy more bonds in future with higher net RoI, if possible to build a very secure “base income” layer.
- Can I park some money that I leave around unused in SB and move it to T-Bills? Eg: a 182-day T-bill gives 4.45%! Need to check.