Last Updated on October 1, 2023 at 8:12 pm
“How much money do I need to retire comfortably?” is the central question of retirement planning. Comfortably refers to (1) generating an income that will keep pace with inflation; (2) having some buffer in the corpus to handled unexpected expenses (recurring or one-time). However, there is more to retirement planning than just money and that how that money is invested and where it comes from matters. Here is how we can build an “ideal retirement portfolio”.
Let us borrow a term used by PV Subramanyam of Subramoney.com: retirement portfolio basket. This refers to different income sources in retirement including pension and investments.
The first step is to list components of an ideal retirement portfolio
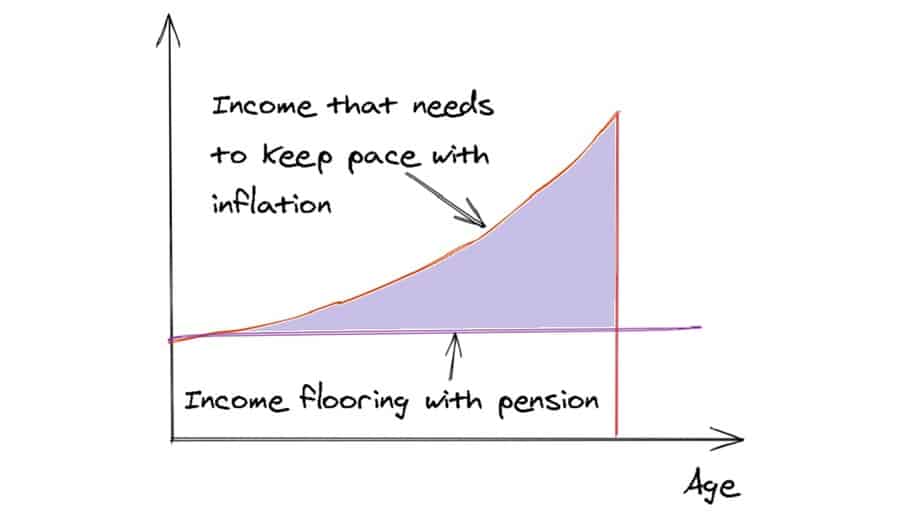
- Pension: This is an obvious and important component. Also known as income flooring. This will remain the same until the death of the surviving spouse (this means the following: say you now 40Y of age and your spouse 35. Assuming the younger spouse dies later, retirement planning should provide an income until the death of the younger partner).
- Inflation protected income: This increases gradually and drops to zero ideally only after the death of the surviving spouse.
As discussed earlier – Creating the ideal retirement plan with income flooring – if the pension = initial monthly expenses at the start of retirement, the burden of creating inflation-protected income considerably reduces. We will focus on the components of this inflation-protected income in this article.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
- Investment in retirement buckets which can be classified as safe; low-risk and medium-risk. These can be fixed deposits, liquid funds, hybrid funds etc. A mix that requires management to ensure it does not drop in value too much. See for example The Retirement Bucket Strategy Simulator
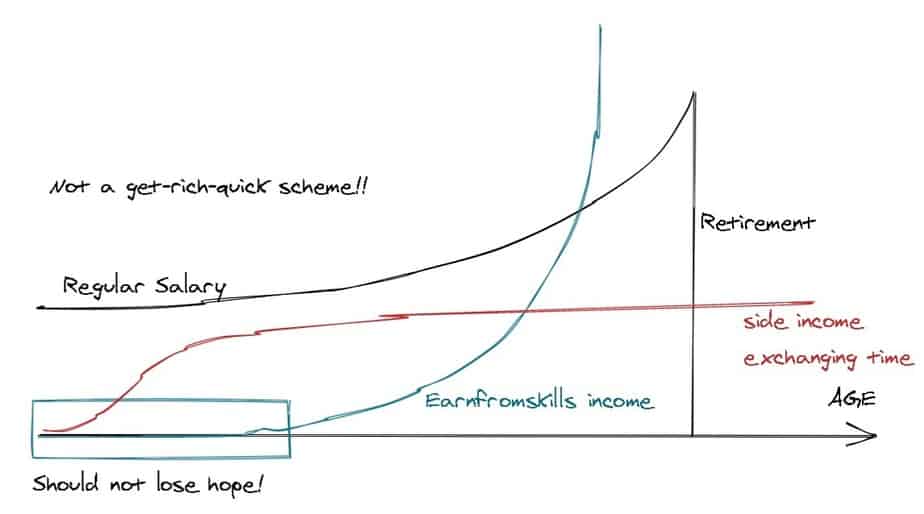
- Active income sources: Retirement need not mean zero active income. One gradually turn skills acquired over a lifetime of employment into freelance consulting. See: How to build a second income source that will last a lifetime
- Passive income from skills: One can, and I would argue must turn those skills into passive income. This can make a big difference to our lifestyle in retirement. See: Passive income is a crucial part of your retirement plan: How to get started
- Passive income from stocks: A direct equity portfolio built during the accumulation stage can make a non-trivial contribution to your retirement portfolio via dividends.
- Rental income: Naturally rental income can make a huge difference to a retirement plan. You can use the robo advisory template to factor in multiple sources of pension and rent to see how the retirement corpus reduces.
The reason for listing out the elements of an ideal retirement portfolio is to plan out which ones we are going to include. For example, if you already have sources of rental income or are likely to inherit some real estate before retirement, you can plan for this with the robo template.
One can sow the seeds of active and passive income right away, years before retirement so that it builds to something significant. This is the main theme of our new course: How to get people to pay for your skills (see syllabus and FAQ here) – 588 members have signed up so far.
As mentioned above, there is more to retirement planning than just pension, beating inflation and income sources. What we do with our time after retirement will determine our mental and physical health and how our close family treats us. Are we going to let our children take our time for granted after retirement, expecting us to take care of our grandchildren? Or are we going to keep ourselves busy with our passion with or without active + passive income? The time to think and prepare for this is now, not close to retirement!