A reader says,” I wish to diversify 10-15% of my portfolio with gold. I am equally attracted to Sovereign Gold Bonds and Multi-Asset Funds but cannot choose. Can you please help?”
First, let us address if it makes sense to diversify a portfolio with gold. The short answer to this question is one can certainly add 10% to 20% of gold to a long-term investment portfolio. However, there are some caveats to be kept in mind.
The USD-INR exchange rate dominates gold returns in the past. In particular, the exchange rate zoomed up when the economy opened up in the nineties. Gold INR returns recently have been in step with Gold USD because our currency is more stable now.
This can be seen in the rolling return chart below. So, a backtest that shows a with-gold portfolio outperforming should not be taken too seriously as repetition is unlikely – unless the country is in serious trouble.
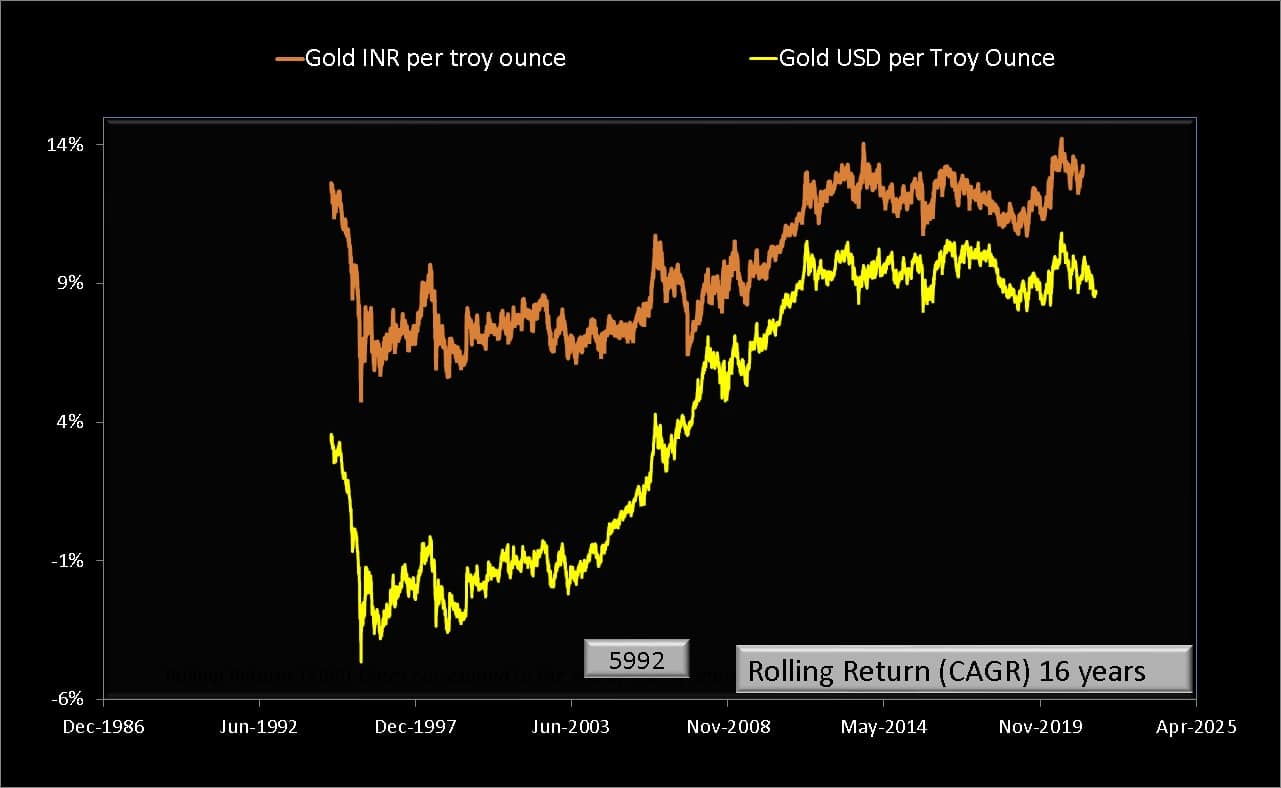
See Gold Price Movement: USD vs INR for more charts and perspectives. These are the conclusions from our previous backtest:
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
- There is no harm in doing so, but one must not do it under the assumption that one will do better than a without-gold portfolio.
- An equity+ gilt portfolio has often done just as well without higher volatility.
- The annual rebalancing will require more effort in the with-gold portfolio. Although it may not need to lead to higher taxes, it is certainly a higher effort. Most investors fear rebalancing, fearing the process and tax with just equity and debt. Three asset classes will only make it harder for most.
- Gold INR is significantly more correlated with gold USD now, and the past high returns of gold are unlikely to be seen again.
- If equity is an asset class driven by optimism, gold is often driven by pessimism and fear. During extended bull markets, gold can go through years of poor returns. So, it would be frustrating to hold it.
- Gold does not always offer a reward commensurate with its risk. See Gold vs Equity (Sensex) 40-year return and risk comparison.
Taking all this into consideration, our recommendation is to avoid standalone gold for long-term goals. However, if you still wish to include a “small amount” of gold in your long-term portfolio, sovereign gold bonds (SGB) are unsuitable. SGB is only useful for buying gold jewellery eight years from now.
This is because they cannot be easily purchased and sold in the secondary market for a price close to the current gold price due to poor liquidity. A gold EFT or gold fund is better (ETF for those comfortable with trading and associated risks and fund for those who prefer a passive approach). This is especially true if your portfolio is already replete with equity funds.
Many readers often ask, “Why should I sell the SGB? I will hold it until maturity, and that way. I don’t have to pay tax as well”. If you start with 10% gold exposure, it will not remain the same. What should one do after a year if the exposure increases to 15% or drops to 6%?
Leave it alone like an untended garden to grow wild because we have satisfied the urge to hold 10% gold (at least initially). Or, like a responsible fund manager of our dreams and goals, reset it back to 10%? After all, we wanted gold for diversification, and the price of diversification is asset rebalancing and associated taxes. Are we ready to pay this price?
The sad truth is most of us are ready to do this. We want the benefit but not the cost. At least for those with young/new equity portfolios, there is such a choice – a multi-asset fund, provided it is one of the dominant funds in your portfolio.
You get “little exposure to gold” (these can hold other commodities like silver and derivatives, too) and don’t have to worry about fluctuating asset weights, rebalancing, or taxes. The only missing aspect would be the frivolous pleasure of regularly looking at gold returns in the portfolio.
It must, however, be noted that not all multi-asset funds are equity-oriented. We recommend using an equity-oriented multi-asset fund in the portfolio as a pure equity fund. Examples are funds from ICICI, Kotak, HDFC, etc. (please check holding history before purchasing).
Related Resources:
- How to choose a multi-asset mutual fund
- Aggressive Hybrid Funds vs Multi-Asset Funds: Which are better?
- Multi-asset mutual funds: performance analysis
- How are multi-asset funds taxed?
- Will ICICI Multi-Asset Fund become more volatile with Commodity Derivatives?
- ICICI Prudential Multi-Asset Fund Review: Suitable for new investors?
- Will ICICI Multi-Asset Fund become more volatile with Commodity Derivatives?