I have been investing for my son’s future (college and other expenses) since Dec 2009 – a month before he was born (He is 14 now). Here are some lessons from this journey.
Many years ago, I asked in the Jagoinvestor forum, “If anyone has achieved their financial goals using mutual funds, please share your experience”. To this, Manish responded, “It is unlikely that any forum member would have done this”. So I told myself, “Let me be the first person I know to have done this”. Thanks to the freefincal community, I know many more now.
When I started investing for this goal, money management basics were almost in place, except for term insurance, which I got a few months later (March 2010). So, from day one, investments were made with asset allocation in mind – 60% equity and 40% fixed income. Contrast this with how most of us (including me) plan for retirement: heavy on EPF/PPF and trying to catch on to equity exposure for several years.
During the last trimester of my wife’s pregnancy, I started thinking about how to start investing for the college fees. We are victims of our own experience. It took me 14 years after school to land a “permanent position”. Although my father retired in 1997 and my mother in 2002, both with meagre salaries, they never pushed me to get a job,
So, I wish the same for my son. Hence this post: What if our children never had to work?! Very few people (Subra being one of them) understood what I wanted to say there. Parents should provide a wide platform for children to blossom, find themselves, and experiment after school. Also, see: How can we help our children choose their careers?
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
So, after a rough estimate of UG + PG education, I decided on a target corpus when my son finishes school. My son would like to explore a career in physics/astronomy.
I exploited the fungibility of my mother’s cash flow with mine and opened a PPF account for her. I used this as the fixed income component for my son’s education goal.
As her health worsened, I had to consider the possibility of premature closure of the PPF account. So I opened one more in my son’s name. I neither claim these as “good decisions” nor do I recommend that. I am just stating facts.
To this day, neither PPF account has been maxed. The total investment per account per financial year is nowhere near Rs. 1.5 Lakh. If I had done this, the first casualty would have been asset allocation.
First, a SIP in HDFC Top 200 was started for the equity. I added HDFC Prudence and ICICI Dynamic Fund (now multi-asset) a few years later. The Top 200 was shifted to Prudence, and Mirae India Opportunities was added at some point. Again, I am merely stating facts. Unlike what many think, no complex calculations were involved in these decisions. Initially, I was planning for his marriage expenses separately, but later on, I merged it with the education goal.
Readers familiar with my yearly financial audits may recall the equity portfolio.
For an update on my retirement portfolio, see 16 years of Mutual Fund Investing: My Journey and Lessons Learned.
Equity: Asset allocation 58%. Overall portfolio return: 15.74%
| Fund | XIRR | Weight |
| HDFCBalAdv | 21.36% | 31.39% |
| ICICI Multi-asset | 19.46% | 48.05% |
| Mirae Largecap | 16.04% | 20.30% |
| HDFC Sensex | 32.77% | 0.26% |
HDFC Sensex fund is a recent addition with a small exposure (0.12%). See: My 13-year-old begins his investing journey with an index fund.
Fixed income Asset allocation 42%
| Fund | XIRR | Weight |
| ICICI Arbitrage | 6.08% | 24.91% |
| ICICI Gilt | 6.38% | 19.02% |
| Parag Parikh CHF | 16.00% | 16.92% |
| PPF | 39.15% |
I have kept the equity allocation close to 60% throughout these years. Rebalancing five times – three times into the PPF account and twice into an arbitrage fund (ICICI). Initially, I wanted to reduce equity to 55% and lower but backed off after accumulating fairly enough in fixed-income assets.
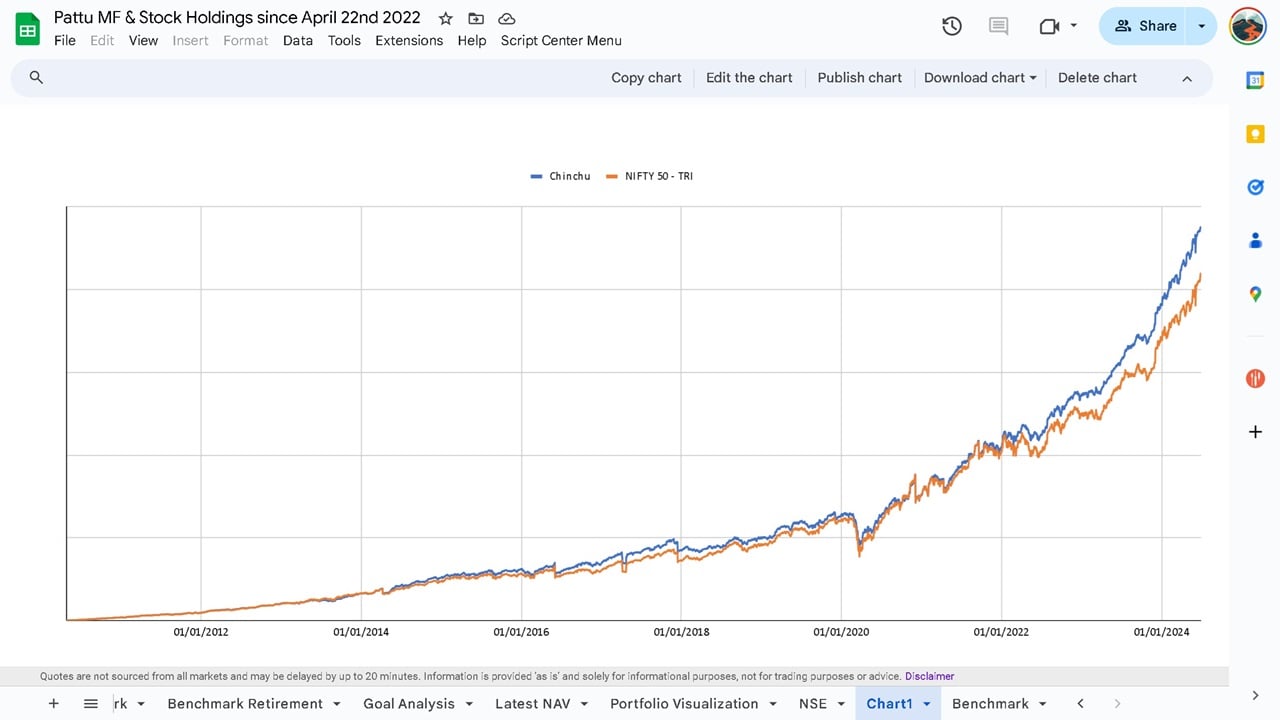
This is the normalized equity portfolio evolution since its inception (Jan 2010), along with an equivalent investment in Nifty 50 TRI. This was plotted with the freefincal portfolio tracker.
Lessons in this 14-year journey
- Time is crucial. I had 18 years before he finished school (because he is Jan-born). Starting allows us to take significant portfolio risk. This applies not just to the initial phase of the investment but also to the latter half.
- Luck is crucial. I have not seen a major market crash in this period.
- Goal-based rebalancing/re-alignment is crucial. I have been able to gradually allocate an amount equal to current PG expenses over the last few years. This allows me to have a high equity exposure despite the sequence of returns risk.
- Increasing the amount invested each year is a huge factor. I have increased my investment amount by about 15% each year. This is the hardest. Luck plays a big role here. Any big expense or break in employment can make things difficult.
- Focus is important. Focus on inflation first. Even 10% is an underestimate here. Despite that, people ask, “Is X child plan good? The “where to invest” question should start here.
- Investing each month based on a system is systematic investing. This investment can be manual or automated but must be based on a plan. Merely automating when money will be debited from a bank account is called SIP.
If you want to start systematically, use our robo-advisor tool to create a complete financial plan.