A reader asks, “Sir, My wife and I are both working in the same company and do wish to have children. We are both aged 27. We have just started working in well-paid jobs, so our networth is essentially zero. Our dream is to put an end to salaried existence in at least 13 years’ time by the time we turn 40. Can we achieve financial independence in 13 years, starting from scratch?”
When we sought more details, the couple mentioned that their current monthly expenses are about Rs. 30,000. They did not wish other details to be disclosed in the article.
Let us find out what the freefincal robo advisory tool coughs up for this scenario. The assumptions and inputs are listed below.
- Age at the end of the current year: 27
- Age you wish to retire 40
- Years to retirement 13
- Total average monthly expenses (annual/12) Rs. 30,000
- Percentage by which your monthly investments can increase each year (until you have accumulated enough for retirement) 10%
- Post-tax return expected from equity investments 9% (expect less, and you will not be disappointed!)
- Post-tax return expected from current taxable fixed income 6%
- Rate of return expected from current tax-free fixed income 7%
- Inflation before retirement 6%
- The assumed life expectancy of the younger spouse: 90 (in this case, both of them are the same age)
- Inflation during retirement 6%
- Years to retirement 13
- Monthly expenses in the first year of retirement Rs. 63,988
- Years in retirement (until younger spouse reaches age 90) 50
Results:
- Retirement Corpus required 2,98,39,853
- Initial monthly investment required, including EPF/NPS contributions Rs. 46,331
The investment schedule generated is given below.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
| Age | Monthly investment in equity | Monthly investment in fixed income, including total EPF/NPS contribution. If the EPF/NPS contribution is greater than this, adjust the equity investment to align with the suggested asset allocation (above graph or columns H & I |
| 28 | 27,799 | 18,533 |
| 29 | 30,579 | 20,386 |
| 30 | 33,636 | 22,424 |
| 31 | 37,000 | 24,667 |
| 32 | 40,700 | 27,133 |
| 33 | 42,680 | 31,937 |
| 34 | 44,648 | 37,431 |
| 35 | 46,583 | 43,703 |
| 36 | 48,459 | 50,856 |
| 37 | 50,245 | 59,002 |
| 38 | 51,902 | 68,269 |
| 39 | 53,389 | 78,799 |
| 40 | 54,654 | 90,753 |
The suggested asset allocation schedule is given below.
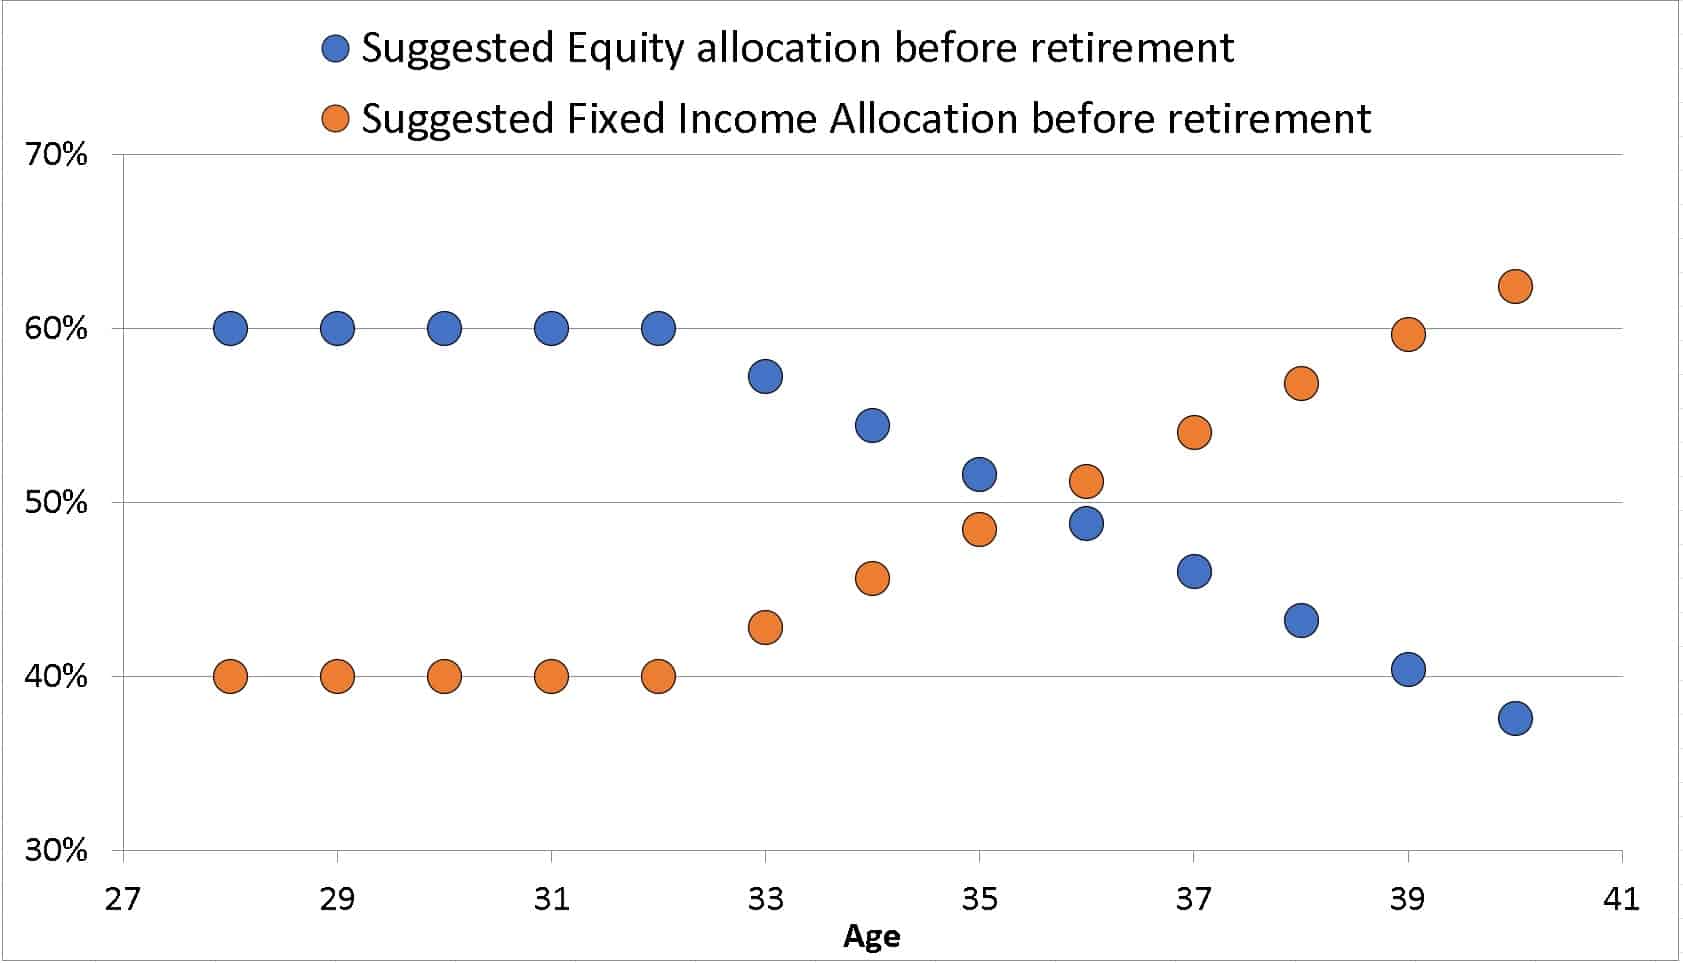
After retirement, the calculation assumes the use of a retirement bucket strategy as explained here:
- I am 30 and wish to retire by 50; how should I plan my investments?
- Retirement plan review: Am I on track to retire by 50?
In summary, can this couple achieve financial independence in 13 years, starting from scratch? They certainly can if they invest more than twice their current monthly expenses. This is possible with a large total income and low expenses. They should ensure that lifestyle creep in future does not affect the investment schedule.
However, this should not come at the cost of reducing their wants today. They must find a balance between needs, wants and future goals and not deprive themselves of any pleasure – especially those that can only be enjoyed when young. If they are not able to invest the suggested amount, then we recommend not fretting about financial independence and investing whatever they can. They will still be on course to normal retirement.