We discuss a tactical entry and exit strategy for small cap mutual funds. This is the second such article. In the first part, we discussed a strategy based on the ratio of the small cap index to Nifty 50. This had a lower risk than a systematic investment in a small cap instrument and a better risk-adjusted return (return per unit risk taken). See: How to reduce the risk of investing in a small cap mutual fund.
In this article, we shall discuss the use of double-moving averages. This has a higher risk than a systematic investment in a small cap instrument with a potential for higher reward. Even at this stage, it should be obvious that the ratio-based approach is far superior, but for what it is worth, Let us look at the data. This study extends a previous report: Do not use SIPs for Small Cap Mutual Funds. Try this instead!
Before we proceed, several warnings, disclaimers and caveats should be disclosed. Unless you appreciate these, please do not proceed further.
- The entry and exit signal chosen (explained below) is arbitrary and based on past data, which is not too long (only since April 2005). The same criterion may or may not work in future. Similar to metrics like PE and PB, this will change as market history is added.
- A backtest may look wonderful today, but that does not guarantee it will work in future. See, for example, A risk in market timing that 122 years of backtesting failed to reveal! There is no guarantee that it will work in future.
- This is especially true of most Indian indices, particularly small cap indices, where the historical data is quite short, and the actual traded history is often even shorter.
- Anyone who uses the ideas described here or in our tactical asset allocation archive of articles does so at their own risk. Freefincal or this author/editor is not responsible or liable for any gains or losses that may result.
- Results shown in backtests do not factor in future market movements, human emotions, taxation and exit loads. All these would impact the outcome of market timing.
Shown below is the NAV (blue), the six-month moving average (green), the twelve-month moving average(red) and the dotted line, which is equal to “1” when the green line is above the red line (6MMA > 12MMA) and “0” if 6MMA < 12MMA.
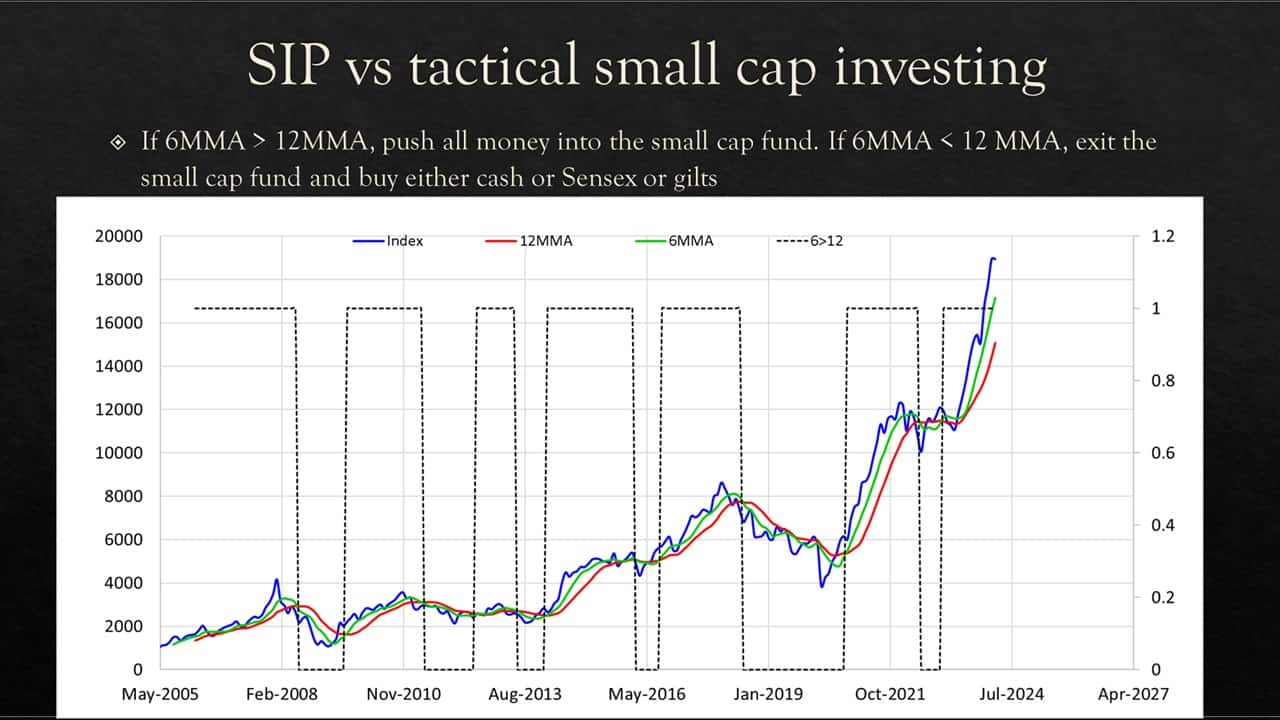
- Systematic strategy: Normal SIP in a small cap fund (index in this study)
- Tactical strategy with double moving averages: If 6MMA > 12MMA, push all money into the small cap fund. If 6MMA < 12 MMA, exit the small cap fund and buy cash (“yielding” about 6% yearly), Sensex/Nifty, or gilts (three different options). In this case, we will only consider cash and Nifty. Taxes and exit loads have not been considered throughout.
There are some previous studies with this double MMA model. Also see A tool for tactical buying and selling using moving averages.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
- Is it possible to time entry and exit from gilt mutual funds for better returns?
- Testing a double moving average market timing model (part 1): Nasdaq 100
- Testing a double moving average market timing model with S&P 500 (Part 2)
- Testing a double moving average market timing model with gold (Part 3)
This is a single 18Y run comparing the portfolio growth of the double MMA method vs systematic investment in a small cap index. Notice the tactical approach has higher volatility.
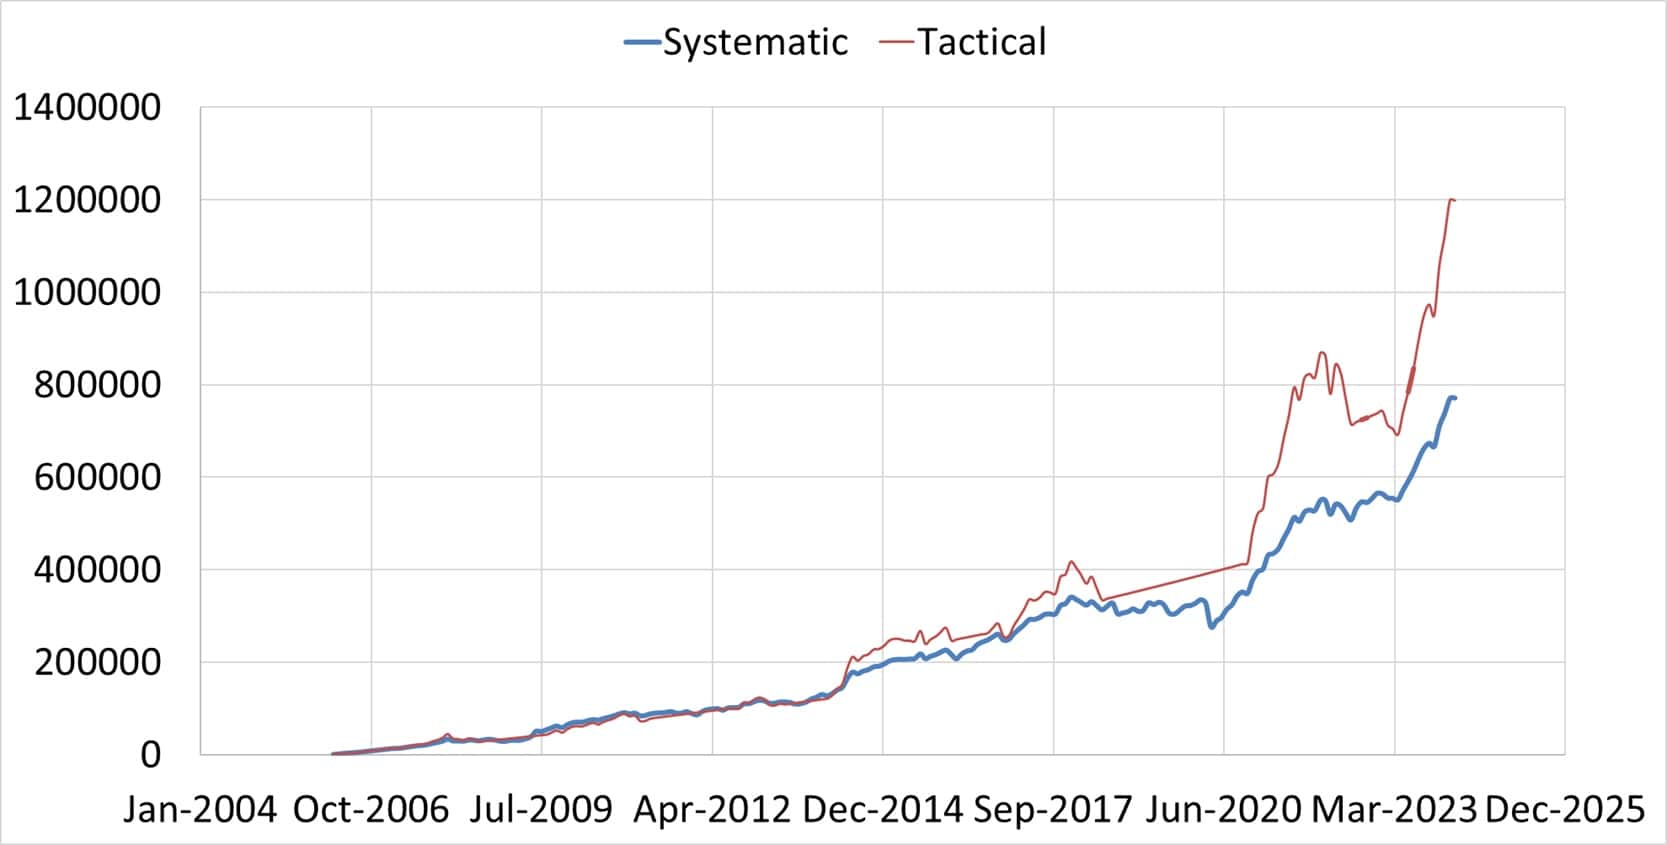
We can get further insights if we run the analysis for ten years. However, please note that the data (108 10Y runs) is still limited. So, this should not be considered as a probability of success.
Double-moving average study with cash
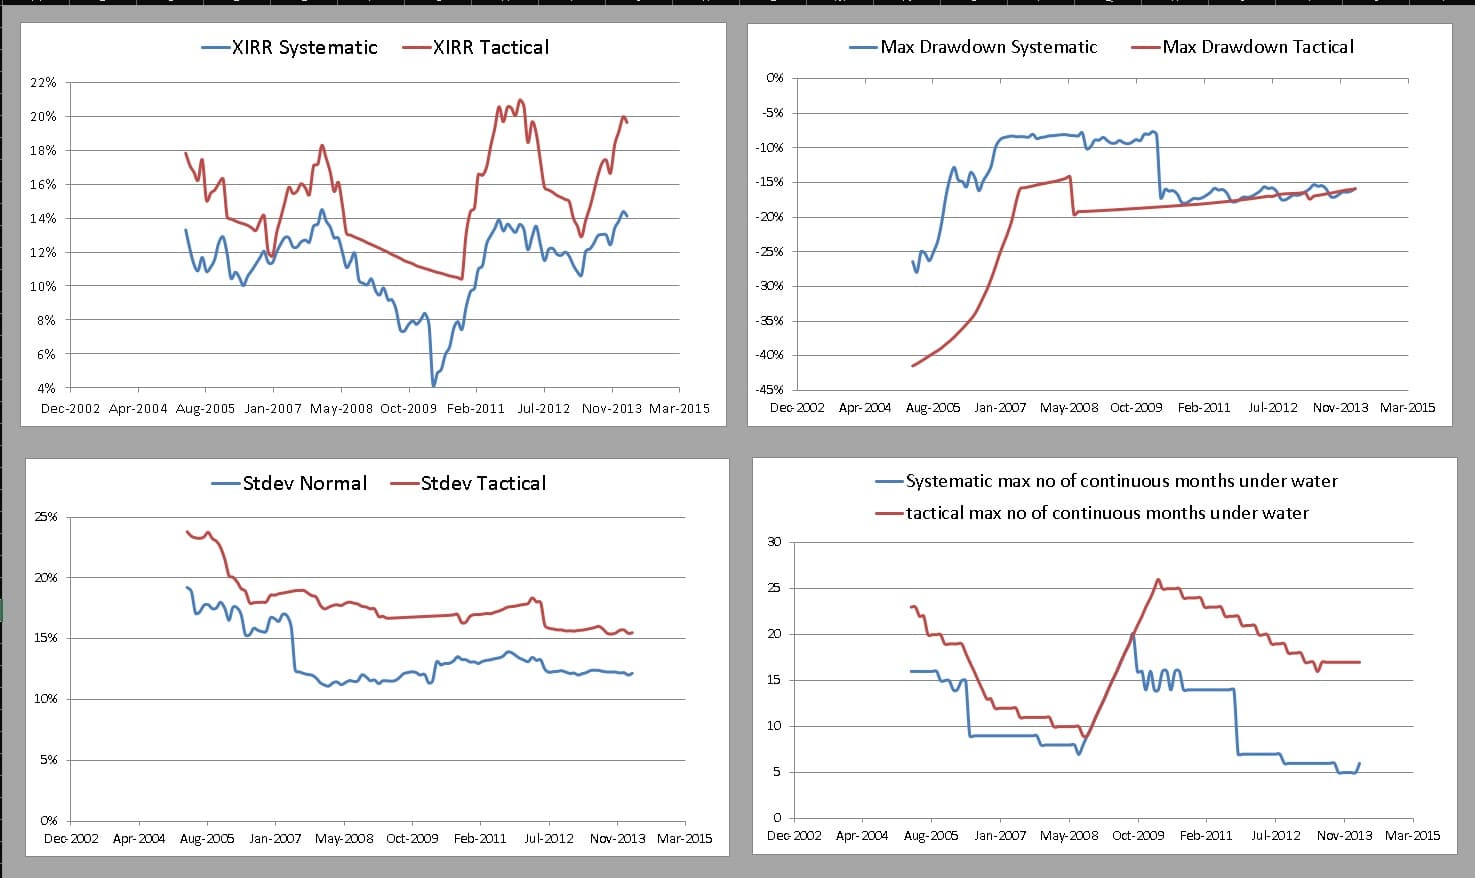
- Top left panel: the XIRR. The tactical strategy has done quite well for the period studied, but the return spread is at least as much as the tactical approach.
- Top right panel: The portfolio’s maximum drawdown (max fall from peak) is shown (the less negative, the better). The tactical strategy has a higher drawdown. That is a higher risk.
- Bottom left panel: The standard deviation or volatility (lower the better). The tactical approach has higher volatility.
- Bottom right panel: the maximum number of months the portfolio was below its peak or underwater (lower the better). The tactical strategy takes a longer time to recover.
Double-moving average study with Nifty (instead of cash)
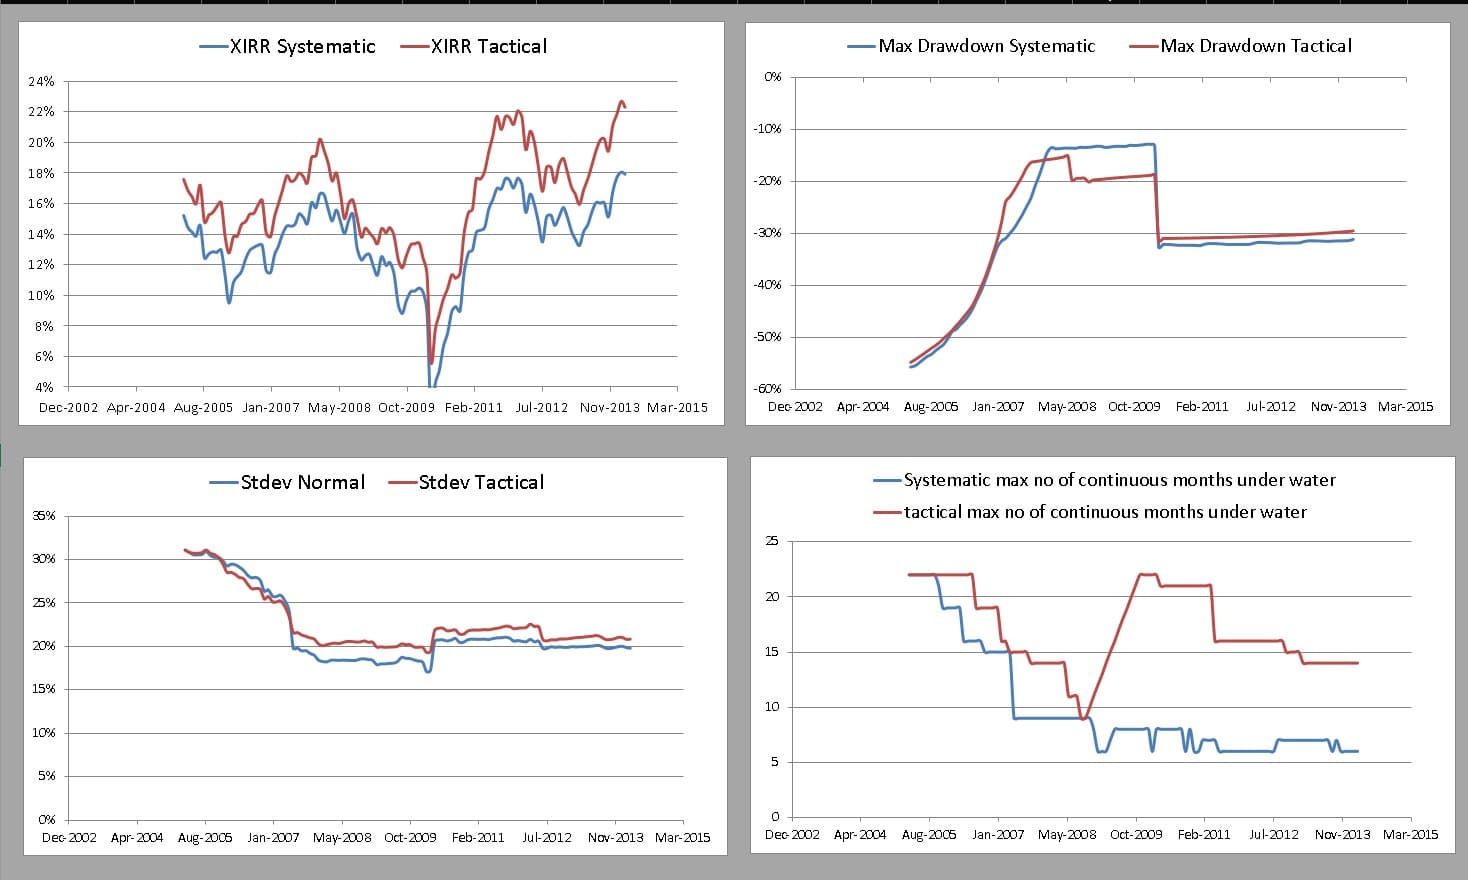
With Nifty (instead of cash), reward and risk (drawdown and volatility ) have decreased.
In summary, the tactical entry and exit strategy for small cap MFs using the ratio of the small cap index to Nifty 50 appears superior to the double-moving average-based strategy.
Explore our full archive of tactical asset allocation studies.