If diversification is about ‘not keeping all eggs in the same basket‘, rebalancing recognises that ‘what goes up, will come down‘. Let us revisit the topic of portfolio rebalancing and discuss what it is, why to do it, and simple ways to do it.
What is portfolio rebalancing?
- Rebalancing is redeeming from one asset class and reinvesting immediately in another. Rebalancing is not profit booking.
- Rebalancing is not timing the market.
- Rebalancing is not a method to get higher returns.
The primary idea behind portfolio diversification is asset allocation (% exposure to equity, fixed income, gold etc.).
A simple 50-60% equity and 50-40% fixed income for long-term goals with the equity exposure systematically reduced well before the goal deadline is sufficient to handle market ups and downs (sequence of returns risk).
As we keep investing and the value of these asset classes increases or decreases, the asset allocation will deviate from the target allocation.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Rebalancing refers to the method by which we reset the asset allocation. There are many ways to do this too. We will discuss a simple method here. Other examples can be seen in the posts below.
We start with a portfolio with X% equity allocation and Y% fixed income. At the end of each year, the asset allocation is reset back to X: Y (will become clear with the example below).
Let equity exposure be 40% (for illustration) and fixed income exposure 60%. Suppose a lump sum of Rs. 10,000 was invested at the start of 2003; the value of the equity portfolio and fixed income folio (fixed 8% return for simplicity) will evolve in the following way.
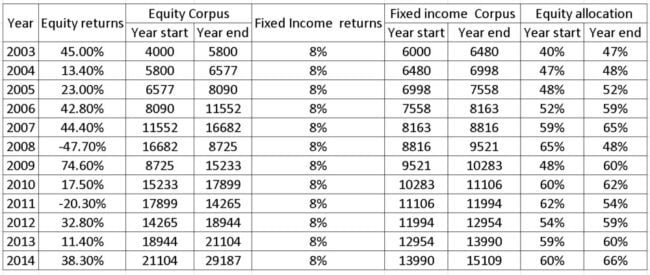
Notice how much the equity allocation varies from 40% at the end of each year. The idea behind rebalancing is to reset it back to 40% at the start of each year.
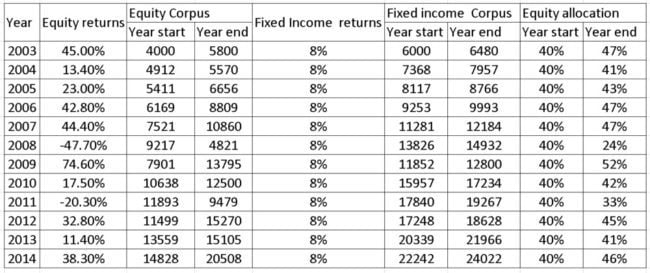
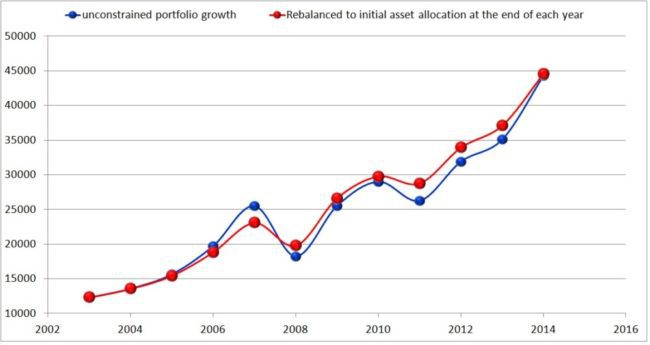
I can easily show you another return data set for which rebalancing lowers volatility and the final portfolio value.
An analysis of multiple runs is explained here. The data is sourced from our previous study: What are the benefits of portfolio rebalancing?
When I say volatility, I also refer to psychological comfort or mental peace, if you will. If the equity folio has moved up 90%, a fall is inevitable. Rebalancing is a way to cushion your mind and folio against such a fall. Whether it will lead to more returns is neither certain nor necessary.
Practical considerations
A diversified portfolio is ‘usually’ built with asset classes that are poorly or negatively correlated with each other. For example, a long-term gilt fund and equity is one way to do it.
Under ideal circumstances, interest rates are increased just before the start of a bull run. This allows the gains made in long-term gilts or gilt funds to shift to equity. As a bull run progress, inflation gradually increases, and interest rates will also increase. Gilt funds would fall, and the gains from equity could be shifted there.
Therefore, rebalancing is the process of shifting gains from an asset that has performed well to an asset that had done poorly but is expected to do well. This sounds easy to say but quite hard to implement. Also, both asset classes can rally or crash at the same time.
I refer to this as two-way rebalancing, which is illustrated above, although the fixed income rate is 8%. Two-way rebalancing requires two poorly correlated volatile asset classes.
Many generally prefer low volatile fixed income like PPF or EPF. Unfortunately, with such instruments, unconstrained withdrawals are not possible, and only one-way rebalancing is typically possible. That is, positive deviations from equity are shifted to fixed income like a money market fund, liquid fund, or even arbitrage fund. Negative deviations are ignored.
Positive deviations could have a threshold. That is, if equity allocation changes from 50% to 53%, do nothing. But if the difference increases by 5% or 10%, then and only then, rebalance. This will also reduce tax and exit loads.
I can use the benefit of hindsight to tell you what has worked. This does not mean such a strategy will work if you like the idea of lower portfolio volatility and peace of mind by shifting gains to fixed income or vice versa; rebalancing is a good idea.
Previous studies on rebalancing and portfolio management
- Portfolio Rebalancing: FAQ (part 1)
- Portfolio Rebalancing FAQ Part 2
- Portfolio Rebalancing FAQ Part 3
- Deciding on asset allocation for a financial goal