A reader says, “I have a generic question about retirement planning. Can you retire if your annual expenses equal 6% of your corpus? Say my monthly expenses are 1 lac. My corpus is two crores. I do SWP for 1 lac monthly. If the returns exceed 6% pa, it will also cover inflation. Is there anything missing in this assumption?”
The catch lies in “If the returns exceed 6% pa”. What would you do if you do not get that 6% return (after tax) for a few years? Spend less? What if you can’t spend less? What if you had to spend more?
You will be forced to withdraw from your corpus at a rate higher than at which it is growing. Eventually, you will run out of money soon. Even if we assume no new retirement expenses arise, the corpus will only last 16 years! In the 17th year, the annual expense would be 33% higher than the corpus!
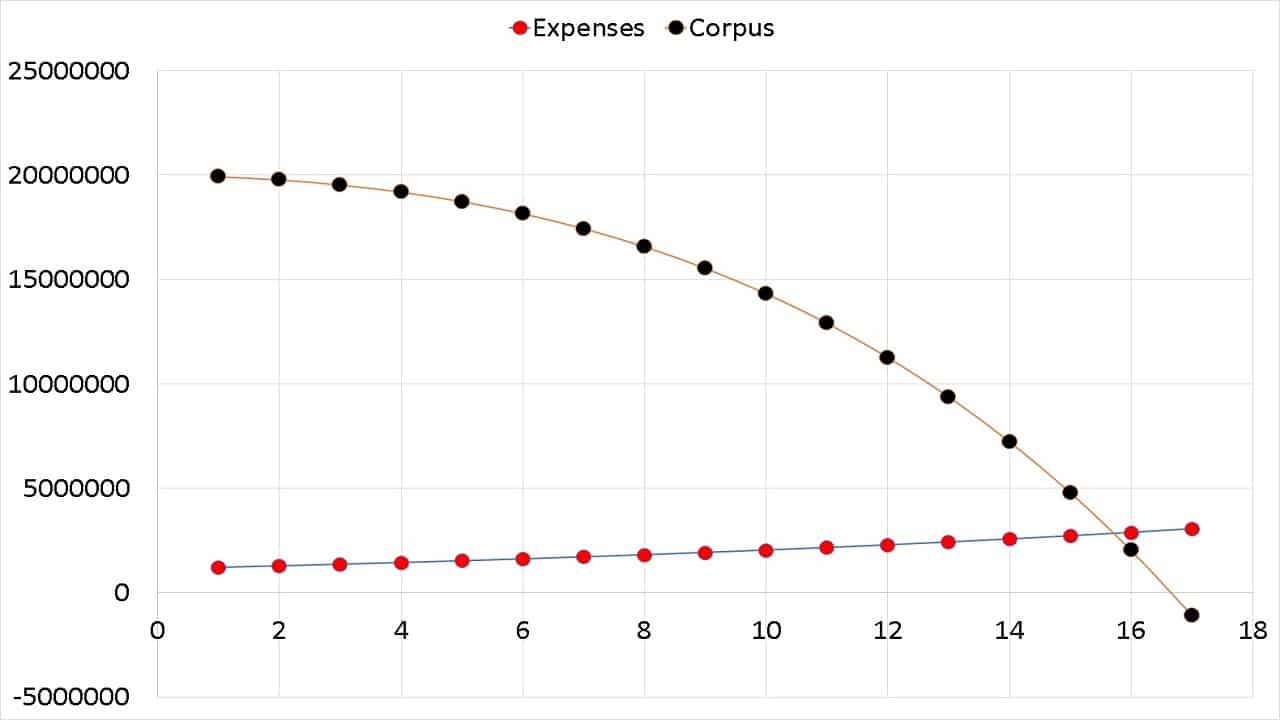
Even for retirement at age 60, having a corpus worth only 16 years (if expenses do not increase, returns do not fluctuate etc.) is a huge risk.
The situation presented by the reader corresponds to a withdrawal rate of 6% (12 lakhs divided by two crores). This is way too high to retire comfortably. Different scenarios have been presented: I plan to retire in 25 years; what should be my safe withdrawal rate? The withdrawal rate should be significantly below 4% to even think of retirement!
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
If the withdrawal is high – even 4% is high today! See Why we need to stop using Safe Withdrawal Rate (4% rule) for retirement planning – then even a small amount of equity (say, 20%) can increase risk significantly. A poor string of returns would deplete the corpus fast. Here are some thumb rules: How to use safe withdrawal rates to gauge retirement corpus health.
At 6% or even 5%, most capital market-linked products like debt funds are risky. The only solution is to buy pension products, small saving schemes or RBI bonds, maintain a small sum for emergencies, find work after retirement and pray … a lot.
Here is a detailed illustration using the freefincal robo advisory tool: My withdrawal rate is 5% – what are my post-retirement investment options?