Regular readers may know that freefincal curates a list of SEBI-registered financial advisors that charge clients a flat fee. That is, the fee is independent of a client’s net worth and does not increase as the client’s wealth grows.
The curated list is more than 10 years old and was created before the SEBI investment advisor regulations came into force. More than a 1000 members of our community are currently working with these advisors. These are results from past client surveys.
- Client Survey: The most important factor in choosing a fee-only advisor
- 685 investors rate their experience with SEBI registered fee-only advisors.
- Are clients happy with fee-only financial advisors?
In September 2017, an information association of such flat fee-only SEBI registered investment advisors – fee -only India, was launched.
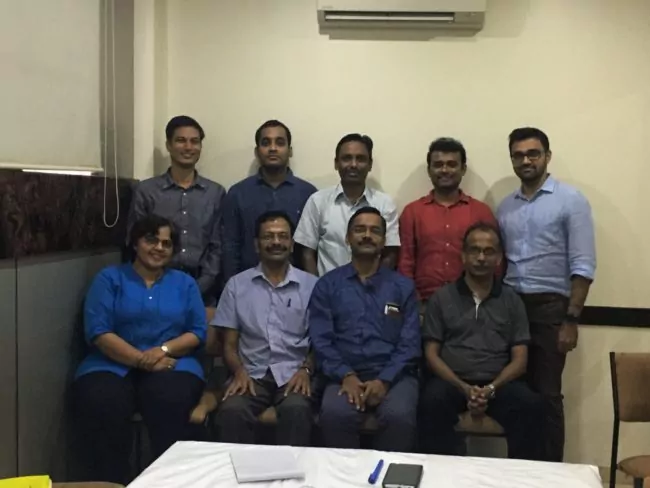
The founding members were: (standing from left to right)
- Chandan Singh Padiyar: Padiyars.com
- Piyush Khatri: Sahastha.com
- Sukhvinder Sidhu
- Swapnil Kendhe: vivektaru
- Vikram Krishnamoorthy: Insightful
Sitting from L to R:
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
- Shilpa Wagh
- Pattu
- Ashal. Admin Asan Ideas for Wealth FB page
- Melvin Joseph finvin
Also see article by Swapnil: Fee Only India – a group of ethical advisors I could finally identify with!
Why Fee-only India’s Financial Advisors Don’t Charge Wealth-Based Fees (Such a fee is called a flat fee or a fixed fee).
To commemorate the seventh anniversary of Fee-only India’s founding, we asked four representatives of the freefincal list of advisors and members of fee-only India to answer this question. Here are the responses.
Avinash Luthria fiduciaries.in
If the fee structure is completely flawed, then the advice is guaranteed to be completely flawed. The % of AUA fee structure is completely flawed and it is not possible to overcome those flaws.
The most common 1% p.a. of AUA fee structure is intended to get the client into an engagement when the client is relatively young, and their net worth is low. Hence the relatively young client will not be able to realize that by the age of 60, they will be paying 33% of their annual household budget as annual fees to the RIA. Such an RIA is hoping that by the time the client realizes this, it will be too disruptive for the client to end the engagement with the RIA.
Even a lower fee like 0.1% p.a. of AUA is deeply flawed. If the AUA is defined as the entire net worth of the client, then the client will be tempted to hide their fixed deposits, PF, PPF and real estate from the RIA so as to reduce the fees. This will ensure that the RIA will not have sufficient information to make sensible saving, asset allocation and investment recommendations. To fix that flaw, if the AUA is defined as excluding fixed deposits, PF, PPF and real estate, then the RIA will be tempted to recommend minimizing fixed deposits, VPF, PPF and real estate, so as to increase the RIAs fees.
Any % of AUA fee (including one that has multiple slabs) becomes more appealing for the RIA as the client gets older and has a higher AUA. This tempts the RIA to ensure that clients cannot terminate the engagement. To do this, the RIA will be tempted to create a very complicated portfolio e.g. with an unnecessarily large number of funds / bonds / PMS / AIFs etc. Such a portfolio will result in very high product fees and taxes. The RIA will also be tempted to trigger all mutual fund transactions and discourage the client from learning to do so. This will ensure that the client is dependent on the RIA for all investments / redemptions.
Basavaraj Tonagatti basunivesh.com
Some RIAs who charge a percentage of AUM lack clarity on which assets to include and exclude when calculating the AUM. As a result, illiquid assets such as real estate (other than self-occupied property), PPF, EPF, life insurance policies, or SSY are sometimes included in the AUM fee, leading to significant costs for clients.
Some RIAs may encourage clients to move from non-included assets to included ones in order to increase their fee. These instances prompted me to consider exploring a fee module that provides clients with clear advance knowledge of the costs involved. This approach offers greater transparency for both planner and client in terms of cost, and in my opinion, represents a pure form of conflict-free advice. Therefore, from the day I registered as an RIA, I have exclusively offered a fixed fee module.
Swapnil Kendhe Vivektaru.com
Good financial advice at retail investor level essentially boils down to 5 important things –
- Deciding asset allocation
- Constructing equity portfolio
- Selecting suitable debt products
- Managing liquidity in the portfolio &
- Recommending insurance policies
None of these 5 listed things require more time and effort for a 10 crore portfolio as against 1 crore. Therefore, charging 10 times more fee in the former case makes no sense.
Financial advisers are professionals, just like doctors, fitness trainers, lawyers, CAs etc.. You pay all professionals on a project basis. Fees of more experienced and more established professionals would be higher, but that has nothing to do with networth of the person taking their service.
Vikram Krishnamoorthy: Insightful
As my focus is on financial planning and on structuring the different aspects of personal finance toward goals, the time spent on each client, irrespective of the goal size, amount in hand or income, is mostly the same. Everyone is recommended the same types of simple investment and insurance products, but the amounts and the ratio is what differs for each person based on their risk profile and goal timelines. The time spent walking the clients through the process, no. of meetings, educating them on the basics, in a process, etc are the same.
It also helps us stand out in the advisory crowd, as this is a client-centric model, where the client is very clear on the fee, for the Value being offered (big picture planning) and what is not offered (returns, active management). He/she also does not get discriminated based on how much they have or their income, they like that the advisor spends the same amount of focused time with them as with anyone else with more money. It also helps in better holistic planning as the client is motivated to share all the relevant data and not hide assets as they may be charged more in other models based on assets held.