Last Updated on October 1, 2023 at 5:40 pm
Here is how the NPS Tier 1 Equity Schemes (“E”) have performed since inception. Many mistakenly assume NPS equity schemes are index mutual funds tracking Nifty 50. A look at the scheme portfolios would immediately dispel that myth. The NPS E schemes hold close to 100 stocks.
Getting the historical NAV history of the NPS schemes is an exercise in of itself and I shall detail how painful this with missing links and unhelpful web formats in a video. Kindly note that the following data/analysis is presented only for information. Regular readers may be aware that I am strongly opposed to the NPS. See: Do Not Invest Rs. 50,000 in NPS for additional tax saving benefit in 2019! Also: NPS has EEE (tax-free) Status! Here is why you should still not invest (ps. it is not exactly EEE, but that is how they like to portray it). If anything, these results will add one more reason for you to stay away from NPS!
NPS Tier 1 Equity Scheme Details
Date Source: NPS Trust Date: July 31st 2019
| Pension Fund (PF) | Assets (Crores) | Inception Date |
| SBI PF | 2,506.03 | 15-May-09 |
| LIC PF | 572.55 | 23-Jul-13 |
| UTI PF | 386.54 | 21-May-09 |
| ICICIPF | 1,395.84 | 18-May-09 |
| Reliance PF | 97.87 | 21-May-09 |
| Kotak PF | 284.97 | 15-May-09 |
| HDFC PF | 2,333.46 | 01-Aug-13 |
| Birla PF | 47.83 | 09-May-17 |
Notice that LIC, HDFC and Birla pension funds (PF) are quite new. The AUM here corresponds only to that of individual NPS subscribers. Govt, corporate and NPS lite AUM is held in separate funds.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
NPS Tier 1 Equity Scheme Returns (as on 31 July 2019)
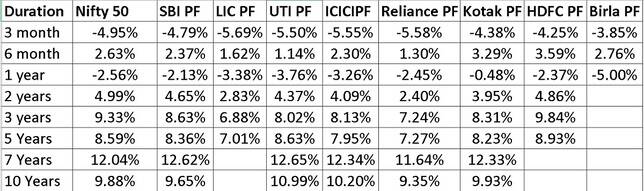
It is high time PFRDA makes NPS mutual fund schemes as plain index schemes!
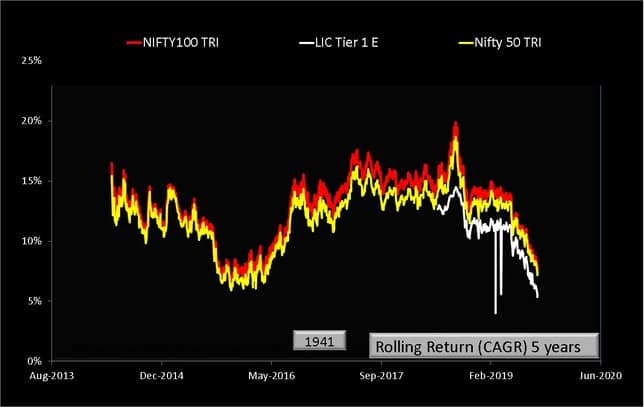
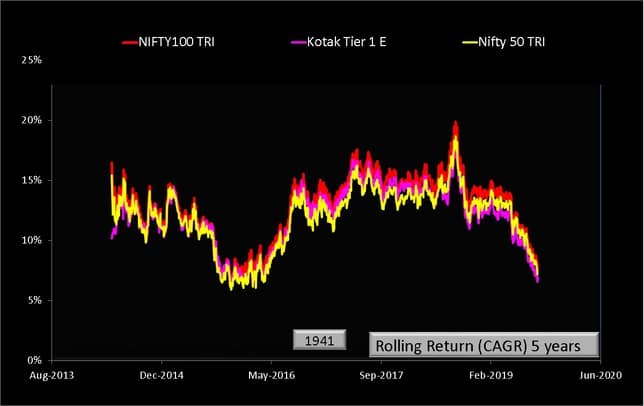
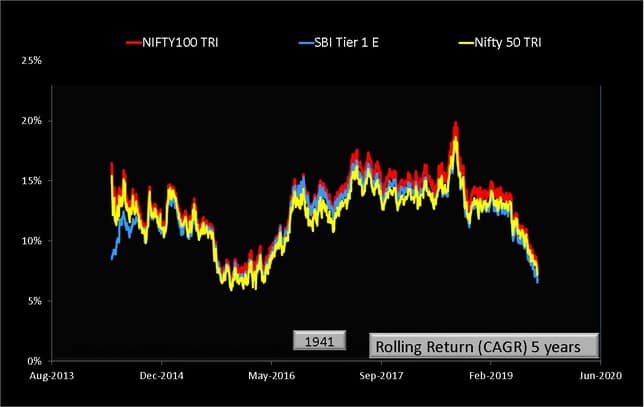
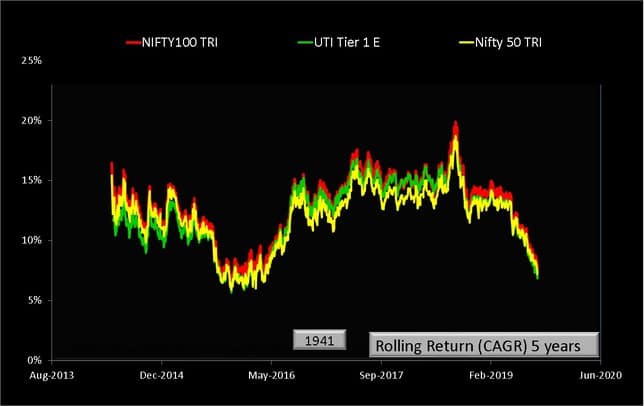
Five year rolling return performance of NPS Tier 1 E Schemes
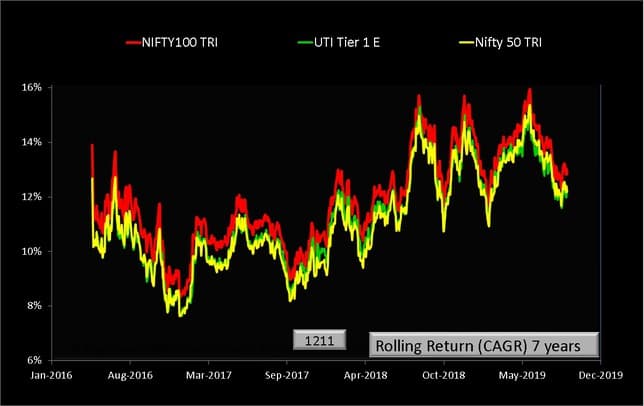
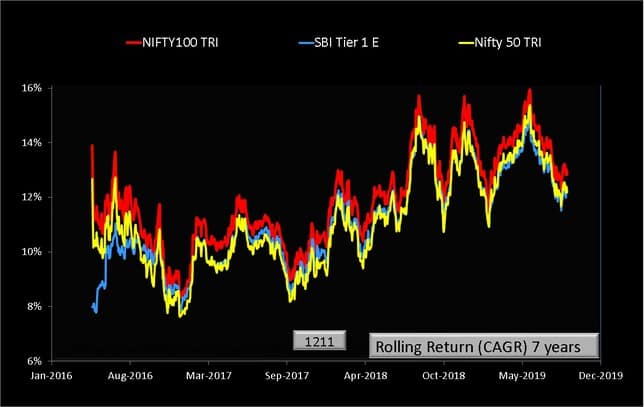
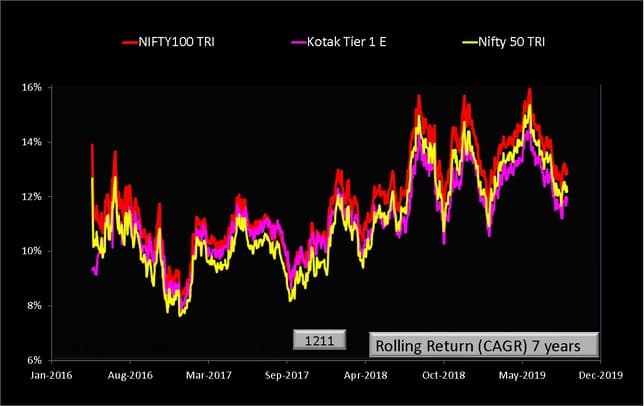
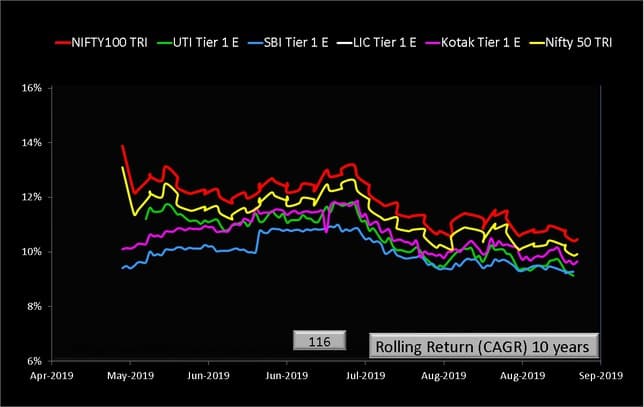
Let us now compare every possible five, seven and ten-year returns of these schemes with both Nifty 50 TRI and Nifty 100 TRI.
LIC Pension Fund Tier 1 Scheme E (5Y)
Kotak Pension Fund Tier 1 Scheme E (5Y)
SBI Pension Fund Tier 1 Scheme E (5Y)
UTI Pension Fund Tier 1 Scheme E (5Y)
Seven year rolling return performance of NPS Tier 1 E Schemes
UTI Pension Fund Tier 1 Scheme E (7Y)
SBI Pension Fund Tier 1 Scheme E (7Y)
Kotak Pension Fund Tier 1 Scheme E (7Y)
Ten year rolling return performance of NPS Tier 1 E Schemes
Summary
You have seen the 5,7 and 10-year performance of NPS Tier 1 E schemes. Would you invest in such normal mutual funds? Would you lock in your money into such mutual funds just because the pension plan has an equity option and just because you get some extra tax benefit? Even if you want tax benefits, even if you have no choice regarding NPS at the very least choose a mix of G (govt bonds) and C (corporate bonds) and invest in equity elsewhere.
This is the reason, I will never change my NPS Central Government asset allocation of primary gilts with 15% equity. I am more than happy with my 9.69% annualized return since 8th March 2010. Yesterday, I have discussed creating the “ideal” retirement plan with income flooring! My aim is to ensure income flooring with the mandatory 40% annuity that I have to buy.
If the NPS E schemes were plain index funds tracking Nifty 50, there is cause to complain. They clearly are not such index funds. If PFRDA wants them to be active funds then they better use total return benchmarks, monitor performance and pull out fund managers who underperform. It would be better for everyone’s peace of mind if they were simple index funds.