Last Updated on January 31, 2025 at 9:16 pm
Use this free calculator to find out if you can stay invested in the National Pension Scheme or must consider a switch to the Unified Pension Scheme (for Central government subscribers only at the time of writing).
We have already covered the salient features of the Unified Pension Scheme and other considerations in our coverage:
- Is the Unified Pension Scheme sustainable?
- Unified Pension Scheme vs National Pension Scheme: How to compare
- Should I switch from National Pension Scheme to the Unified Pension Scheme?
The underlying logic behind the Unified Pension Scheme vs National Pension Scheme Calculator
Can your future NPS corpus provide the same pension expected from UPS (with inflation indexation)? The NPS annuity provides part of this pension. Inflation indexation is provided via systematic withdrawals from the balance NPS corpus (if any!).
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
If the answer is yes, then stay in NPS. If the answer is no, find out how much the shortfall is. For example, you expect to live 30 years after retirement, and NPS can provide an inflation-indexed pension for 29 years. The shortfall (1Y) is small. NPS and UPS are still comparable. If the shortfall is large (several years), UPS is better than NPS.
Important: The corpus from other investments is crucial here. If this is significant, one can afford to stay with the NPS even if UPS is more beneficial. So, we must go beyond the calculator and look at personal circumstances.
Additional thumb rules for holistically deciding between UPS and NPS will be published tomorrow. Stay tuned.
Caution and Disclaimer: This calculator is based on the initial UPS press release and involves several projections. There may be significant deviations between these numbers and real-life values. This must be treated as a guesstimate. Use with discretion. This calculator may have bugs and errors in understanding. Please check all formulae to see if they make sense.
Note: The expected UPS lump sum at retirement is relatively small and is not used to decide between the NPS and UPS.
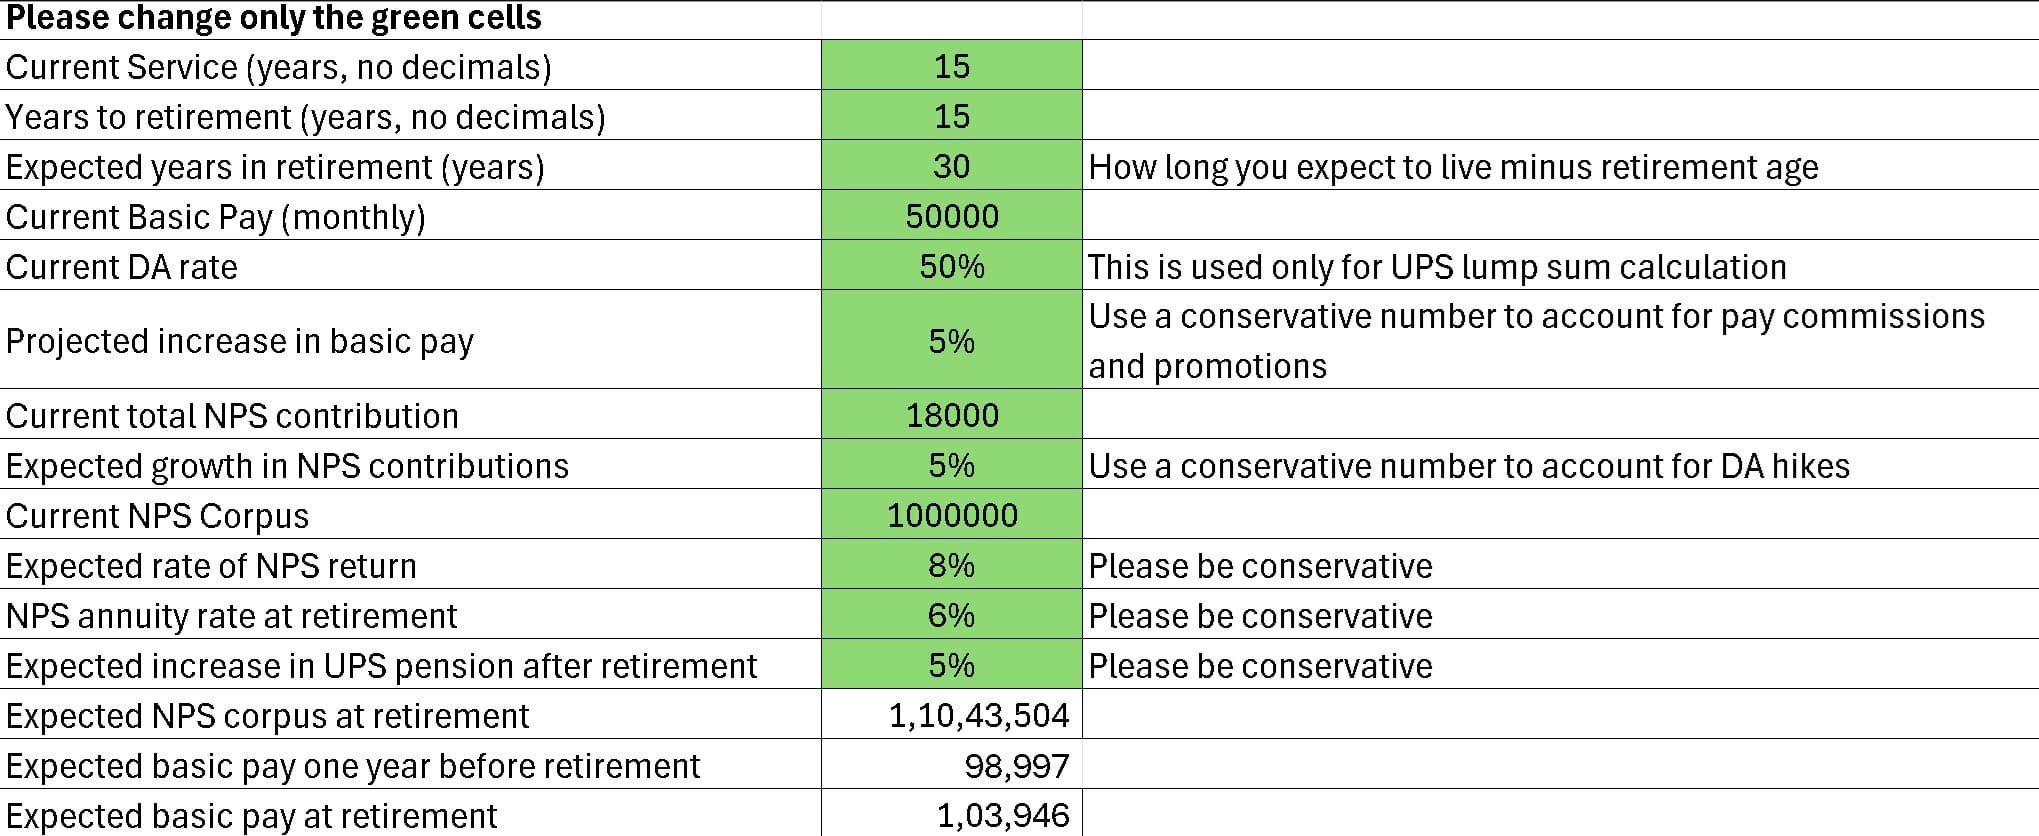
Inputs:
- Current Service (years, no decimals)
- Years to retirement (years, no decimals)
- Expected years in retirement (years)
- Current Basic Pay (monthly)
- Current DA rate
- Projected increase in basic pay
- Current total NPS contribution
- Expected growth in NPS contributions
- Current NPS Corpus
- Expected rate of NPS return
- NPS annuity rate at retirement
- Expected increase in UPS pension after retirement
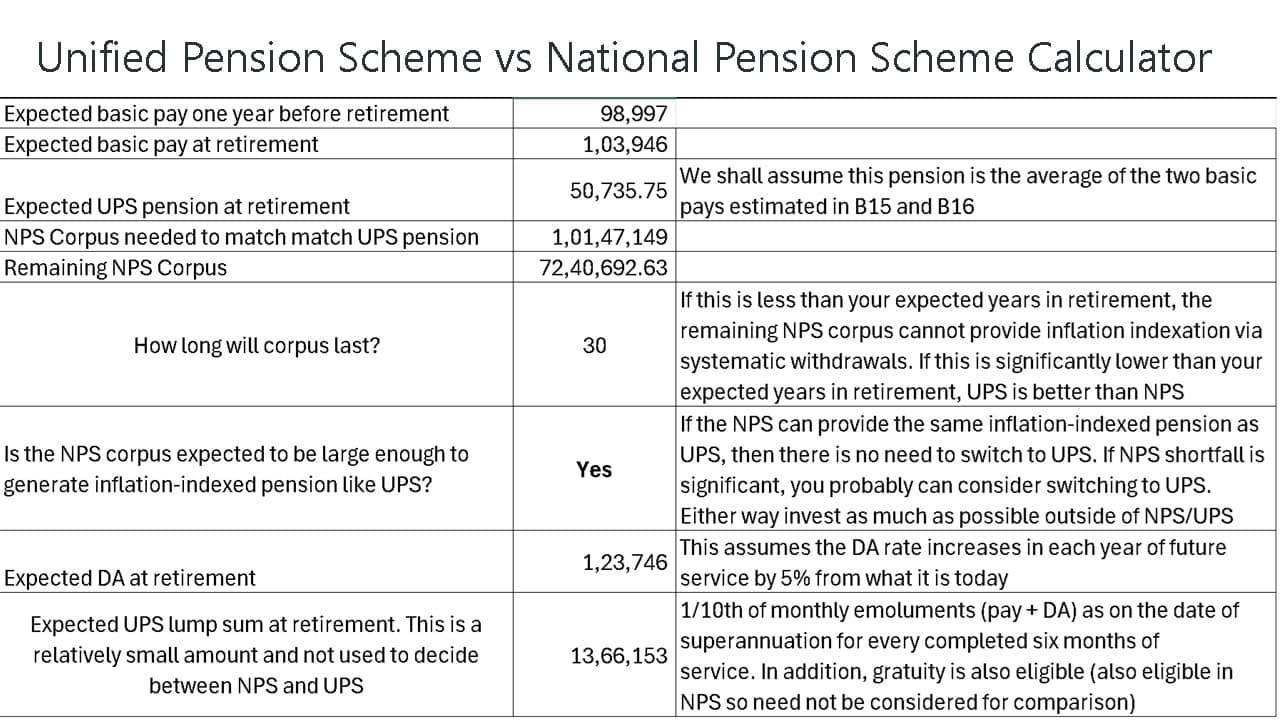
Outputs
- Expected NPS corpus at retirement
- Expected basic pay one year before retirement
- Expected basic pay at retirement
- Expected UPS pension at retirement
- NPS Corpus needed to match the UPS pension
- Remaining NPS Corpus
- How long will the corpus last? <– Key output
- Is the NPS corpus expected to be large enough to generate an inflation-indexed pension like UPS? <– Key output
- Expected DA at retirement
- Expected UPS lump sum at retirement. This relatively small amount is not used to decide between NPS and UPS.
Screenshots
Please check back for version updates. For feedback and bug reports, email freefincal [AT ] gmail [DOT ]com