Last Updated on December 29, 2021 at 12:57 pm
Are you worried if you can afford that new phone or bike or car? Feeling guilty and tempted at the same time? Here is a simple way to find out affordability & organises finances so that you can responsibly buy stuff you love! Every time I got to a corporate money management session, I always hear stories of how young earners buy stuff that they can barely afford and are neck deep in debt. With a little planning, it is more than possible to enjoy a good chunk of our income for our wants.
Of course, not everyone can get everything in life! The biggest problem I see today is, many people (not just young ones) trying to live a life that they cannot afford: Have We Forgot That Aspirations Must Match Our Income?! So since is limited, so should what we desire too! If we want more, then the only way out is a second income: Why a second income is important! Why you have to start now!.
With that caveat let us begin. For the following, I am assuming that the reader is just about to start earning or just started in the recent past. It is so much easier to start on a clean slate. For older readers, the same logic discussed below would apply but they will have to factor in their other responsibilities.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Defining the take-home pay
Just to ensure we are all on the same page, let us define take-home pay as
Take-home pay = Monthly Salary (gross) – taxes – provident fund contribution – miscellaneous deductions
Please do this first the first six months after you start earning
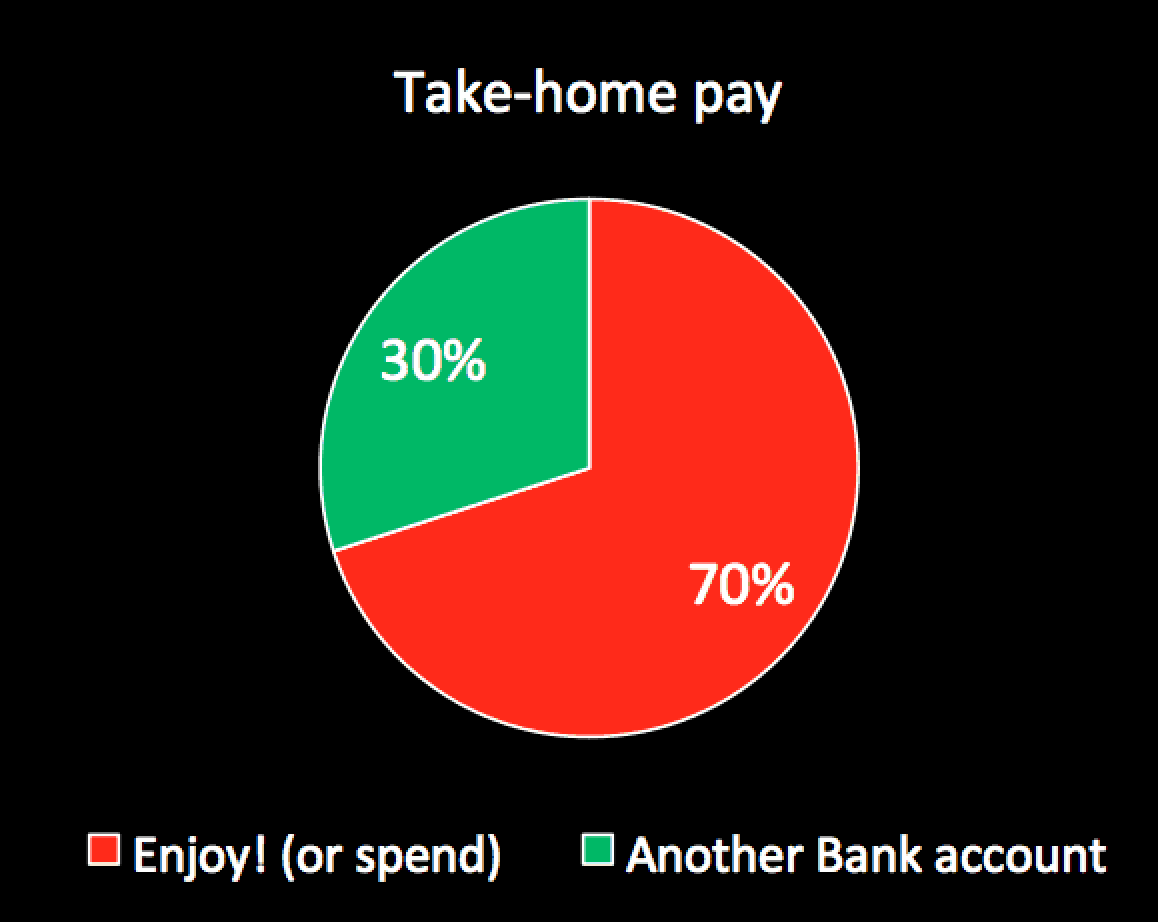
If you have not, do it now!! Take 30% of your take-home pay and put it in another bank account or a liquid fund. This will be your emergency fund. In case your bike breaks down, or TV breaks down. Enjoy the rest if you are living with parents! If you are living alone and/or if you have an education loan, obviously you will have to enjoy less! Just don’t touch that 30% though.
Six months later
- Reduce the 30% emergency fund contribution to 10% (in case you use the fund, it needs to replenished)
- Suppose X is the total pension fund contribution (employer + employee EPF contribution). Then invest 2X in equity (via mutual funds or stocks). See: what should be my first mutual fund? and Select your first stock without breaking your head! Here is how. I have shown this to be 20% for say a one lakh take-home pay (please change as per your real number)
- If you have any short-term need, say a holiday in Bali or an expensive watch or smartphone or camera, save say about 30% for it. Put it in a liquid fund or a recurring deposit
- Rest 40% is for your spend/enjoy.
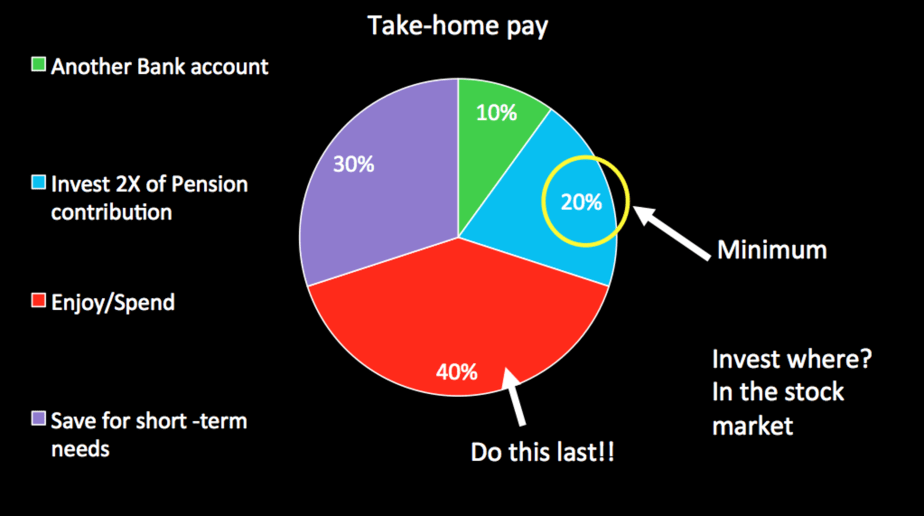
Remember: Invest that 20% first, spend/save later
Can I afford that new phone/bike/car? How do I know?
Let us not complicate this.
- Can you buy the item by saving from salary for a few months without disturbing the 20% investment? Then buy without EMI (loan). Else go to the next step.
- Can you buy the item with a loan without disturbing the 20% investment? Then buy with a loan. Else, wait until you can manage the EMI + 20% investment and other expenses.
That is it! Money is to be spent! Remember that 20% investment is for you to spend it later! So it all about a healthy balance without feeling deprived.
Do not spend money like there is no tomorrow! Then there will be none!
Video Version
The latest from freefincal on YouTube