Last Updated on December 25, 2021 at 10:58 pm
Suppose my current annualised return from an equity mutual fund is 25% and my expectation is only 12%, can I book the excess return (13%) as profit into a safe investment? What if I do this from time to time? Reader Prakash Bala wanted me to create a tool for this and in this post, I discuss if this approach makes sense in the first place.
The notion of an annualized return in equity or any market-linked security is an amusing one. Most people assume the XIRR (for multiple investments) or the CAGR (for a single investment) refers to the rate at which the investment grows year upon year. This is completely wrong. The XIRR is merely an estimate of growth. A high value is obviously good but it does not actually mean much. Read this for a simple explanation of What is XIRR
The second aspect is the nature of equity returns. It varies so much that we cannot imagine its impact year after year.
What is the motivation behind such “profit booking”? It is rebalancing.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Rebalancing is done using portfolio weights. For example, if I start with a portfolio that 60% equity exposure and 40% fixed income and after one year, it becomes 70% equity and 30% fixed income. I can protect some gains by shifting 10% of equity to fixed income and resetting the portfolio.
Now instead of portfolio weights, Prakash (and many others like him) would like to rebalance using excess returns with a specific return expectation.
The first issue in this approach is the estimation of profits. Suppose my expectation is 12% and the fund return is 20%, the “excess profit” is not 8%!!
These 12% and 20% numbers are annualized returns and not absolute returns (which refers to gain or loss). So such a simple subtraction is not possible.
Suppose I invest Rs. 1000 a month for 12 months and on the date of the 12th instalment, my investment value is Rs. 13,068, the XIRR function would result in 20% as an estimate of the annualised return.
Now I need to use Excels Goal Seek function to change the investment value such the XIRR = 12%. This is Rs. 12,651. Therefore, I must book a profit of 13068-12651 = Rs. 417 to reduce gains to 12%. This is only notional. The actual XIRR will not reduce if such a redemption is made. Thus the redemption amount is 3.2% of the actual investment value.
This calculation is not a big deal. Suppose I do this exercise each year from Dec 2003 for Franklin Prima Fund.

Each blue dot represents the ratio of profit-booked to actual investment value for 1Y SIPs. Profits were booked only when XIRR was above 12%. The amount removed was such that the XIRR will reduce to 12%. So the zero blue dots above represent periods when XIRR was less than 12%.
The XIRR before and after such profit booking (after is purely imaginary) is shown below.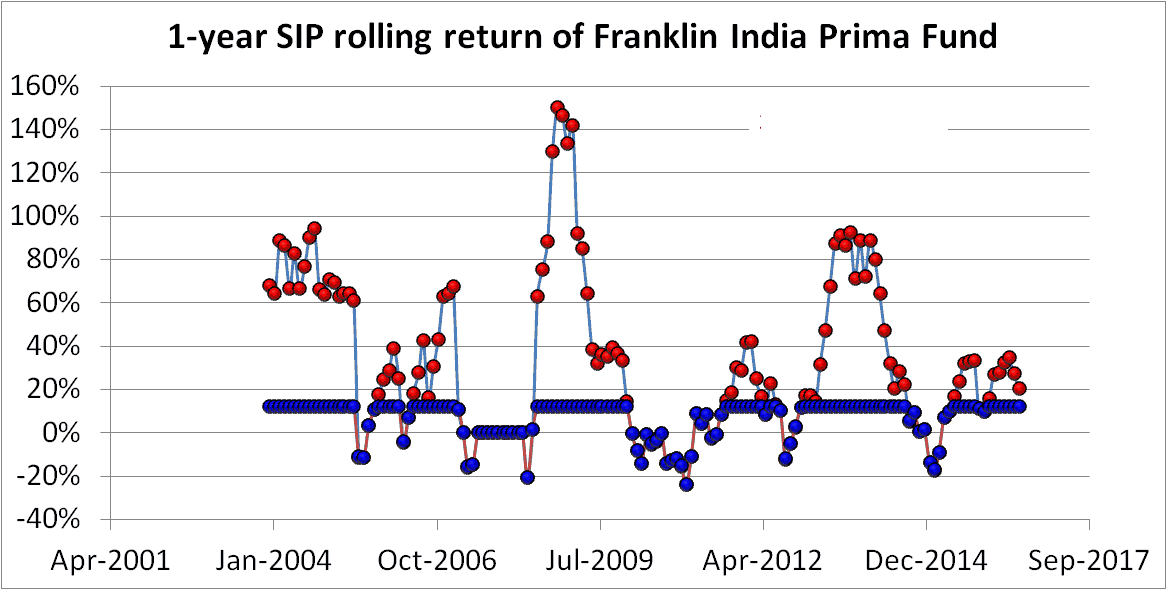
The blue dots represent profit booked values.
When you look at this, it sounds like a promising way to book excess gains. Not so fast. What you see above is for independent 1Y periods.
Now consider an ongoing SIP in Franklin Prima from Dec. 2003. Every year, you calculate XIRR. If it is above 12%, you calculate the amount that has to be removed to reduce XIRR to 12% and remove it.
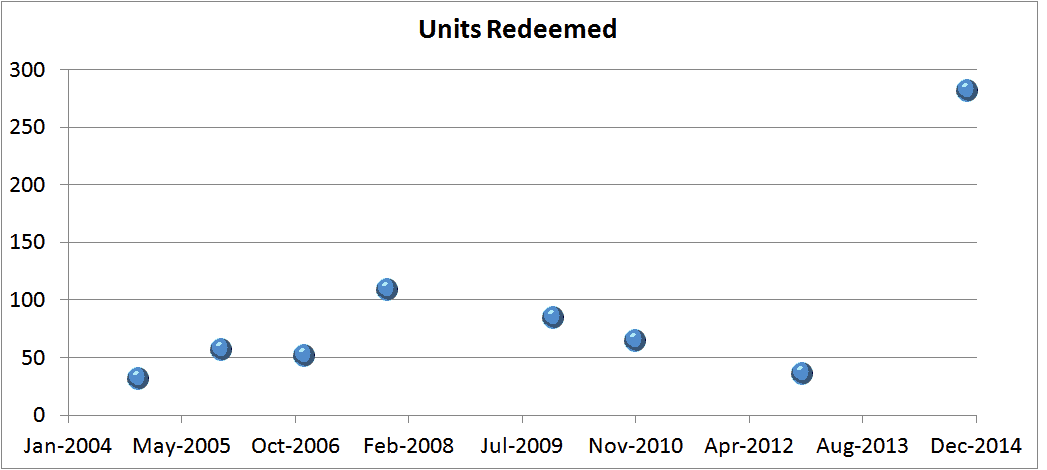
Once the amount to be removed is determined, using current NAV, the units to be redeemed can be calculated. The total units for an unrebalanced SIP and a return-rebalanced SIP is shown below. There are 156 data points in each line.

The actual no of units redeemed is shown below.
The purpose of rebalancing is to preserve gains, but overdo it then the net return would suffer. Apply rebalancing excess returns algorithmically seems to be an overkill.
After 156 SIP instalments, you don’t want to be left with only 35 units of the equity fund just because you want to “book profits” when your fund return is above target return.
Therefore, I would stick to the traditional rebalancing approach based on portfolio weights. One could argue that such return balancing can be done manually on a case by case basis and not periodically. Yes, that makes sense although I have no idea about the impact of this on a portfolio. If you wish to do this, you can consider learning the Excel Goal Seek Function.