Last Updated on July 18, 2022 at 1:17 pm
Amar is 27 and salaried and hopes to retire by 58. Here is how he can plan for financial freedom in retirement. We shall consider how Amar can derive an inflation-protected income and be financially free after retirement.
What is inflation-protected income? A retirement income that increases each year as per the needs of the family. It takes into account inflation in expenses as well as due to lifestyle modifications. Young earners today should not be thinking and be talking about constant income or pension in retirement. They should consider how to consistently beat inflation with an inflation-protected income (also known as inflation-indexed income). Read more: Generating an inflation-protected income with a lump sum.
What is financial freedom? The ability to generate inflation-protected income for a given number of years, preferably until the death of the youngest dependent.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
Before we begin, a video lecture series on Goal-Based Portfolio Management: Techniques to reduce fear, uncertainty, & doubt will be launched on Jan 9th 2010. This will discuss strategies to use and manage the right asset allocation no matter what the market condition is. The ideas mentioned below will also be tested. You can register via this Googe Forms link for a notification upon launch. Note: the course is not about mutual funds or stocks. It is about goal-based investing and asset allocation for DIY investors ready to take it to the next level.
Creating the retirement income plan
We shall use the freefincal robo advisory template to create a retirement income plan for 27-year old Amar who is married to a 25-year old homemaker. Earlier, we had considered a case study for unmarried young earners less than 25: How to create an investment plan.
As mentioned above, Amar is 27 and salaried and hopes to retire by 58. Recommendation: This is okay for a start, but suggest pushing to lower and lower gradually. Less than 30-year olds today must focus on retirement by 50 (20 years of “bound” labour).
Therefore we shall plan for retirement income from the time Amar reaches 58 to the time his wife (younger spouse in general) reaches 90. Therefore, Amar has 31 years to invest (the most precious asset) and needs to plan for inflation-protected retirement income for 34 years.
We shall consider 8% inflation before and after retirement. If this seems high to you, it is because you have bothered to calculate your personal inflation rate and/or have not handled unexpected recurring expenses (my prayers that you don’t have to). Do not take the inflation numbers published by the government seriously, they mean nothing.
Some people talk about “real returns” as if it is some profound concept. It is not. All you need to be clear about is (1) practical inflation in expenses and (2) a practical tax-free rate of return for your entire portfolio. You need to be ready to handle at least 8% inflation. This way, if your actual inflation is less, you would have built yourself a nice corpus to handle medical emergencies.
Why should Amar worry about generating retirement income?
At 8% inflation, in 9 years, his current expenses will double (repeat, just his current expenses. He will have to re-do the retirement calculation once a year). In 18 years, it will 4 times the current expenses.
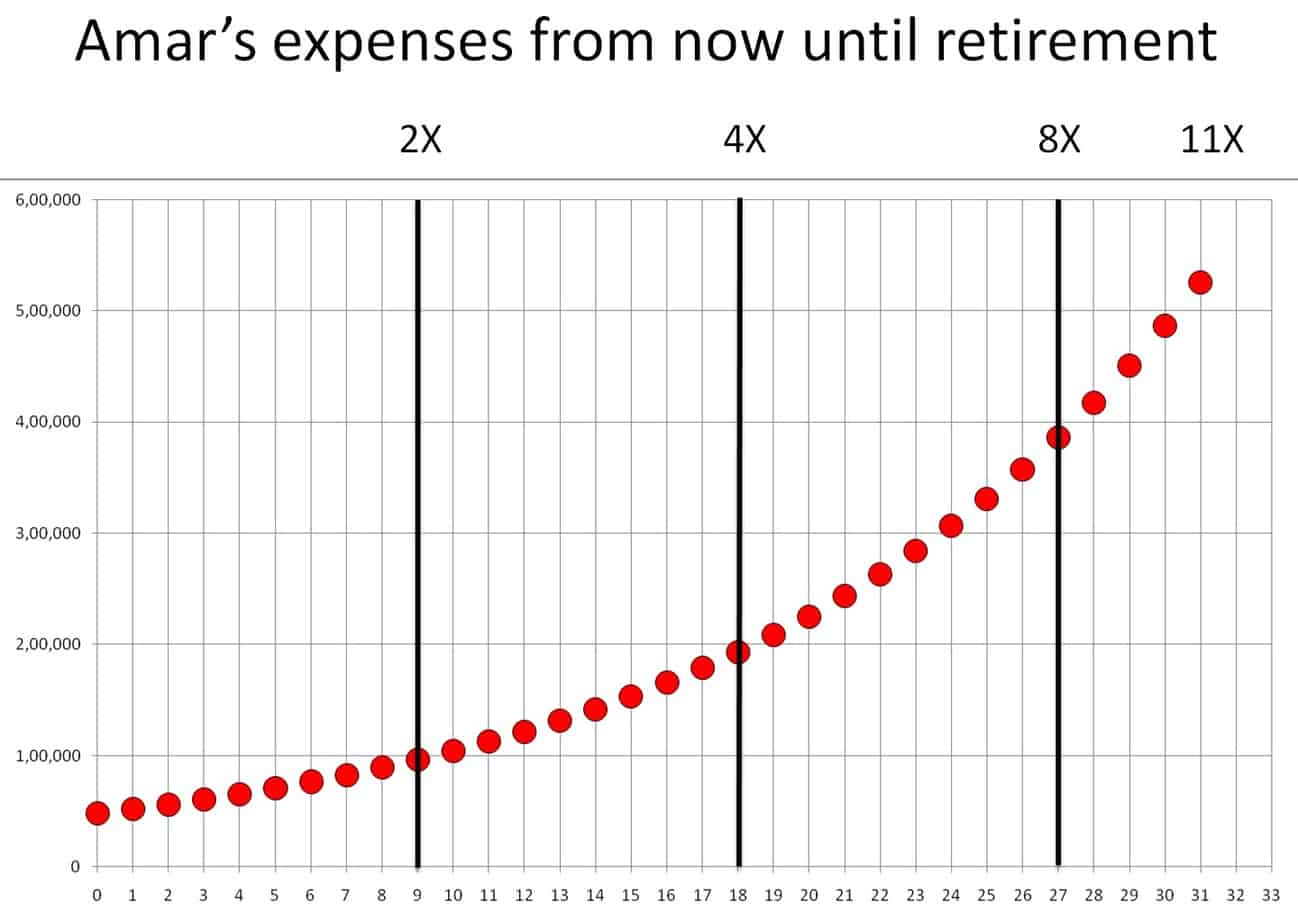
Why is the corpus needed for inflation-protected retirement income so big?
Hold on to your chairs and take a deep breath. Amar will have to have about 21 Crores, 27 lakhs ready by age 58. He will have to begin investing about 57, 500 immediately increasing at 7% a year, in a portfolio of 60% equity and 40% fixed income. Amar, however, need not worry even if he is not able to invest that much. He has time on his side. We assume 8% inflation, only 10% returns from equity – remember we are projecting 31 years into the future.
So expect the corpus to be high. It is better to aim for the 1st floor even when there is more than ample chance to be able to the 5th. Expect less and you won’t be disappointed! Am I being pessimistic? Not really. I have quite optimistically assumed 6-7% returns from fixed income. This is unrealistic over the next 3 decades and it is better to expect less, but let us not be realistic to the point of discouragement.
Variable asset allocation for building the retirement corpus
Starting with 60% equity exposure, Amar can gradually taper down to about 25% at retirement and maintain that.
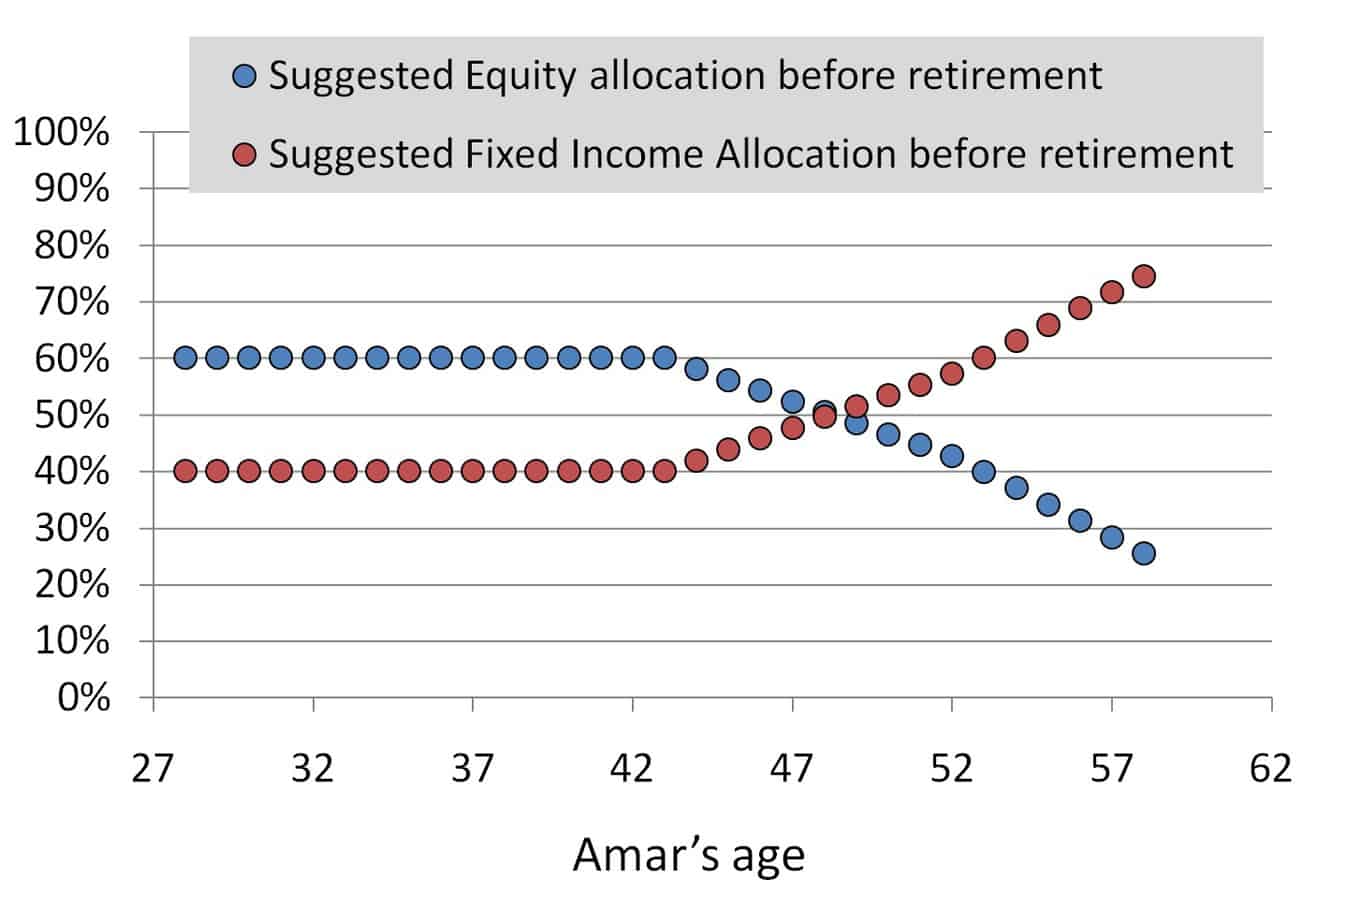
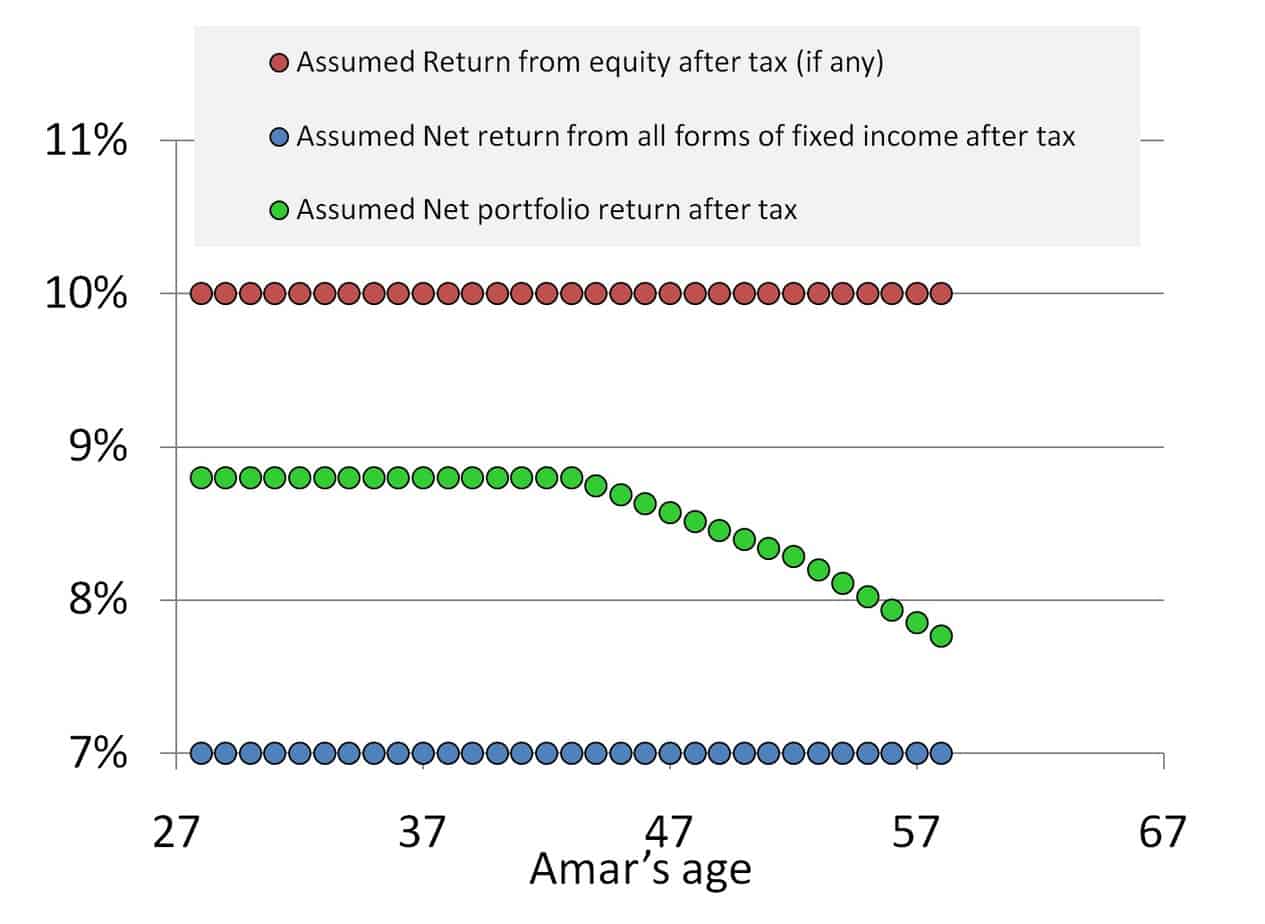
Variable portfolio return due to variable asset allocation
As the portfolios equity exposure decreases, so too do the expected net return from the portfolio. The retirement corpus is so big because this is factored in from day one. Most retirement planning tools (including my early ones) do not consider this crucial aspect. Welcome to the real world!
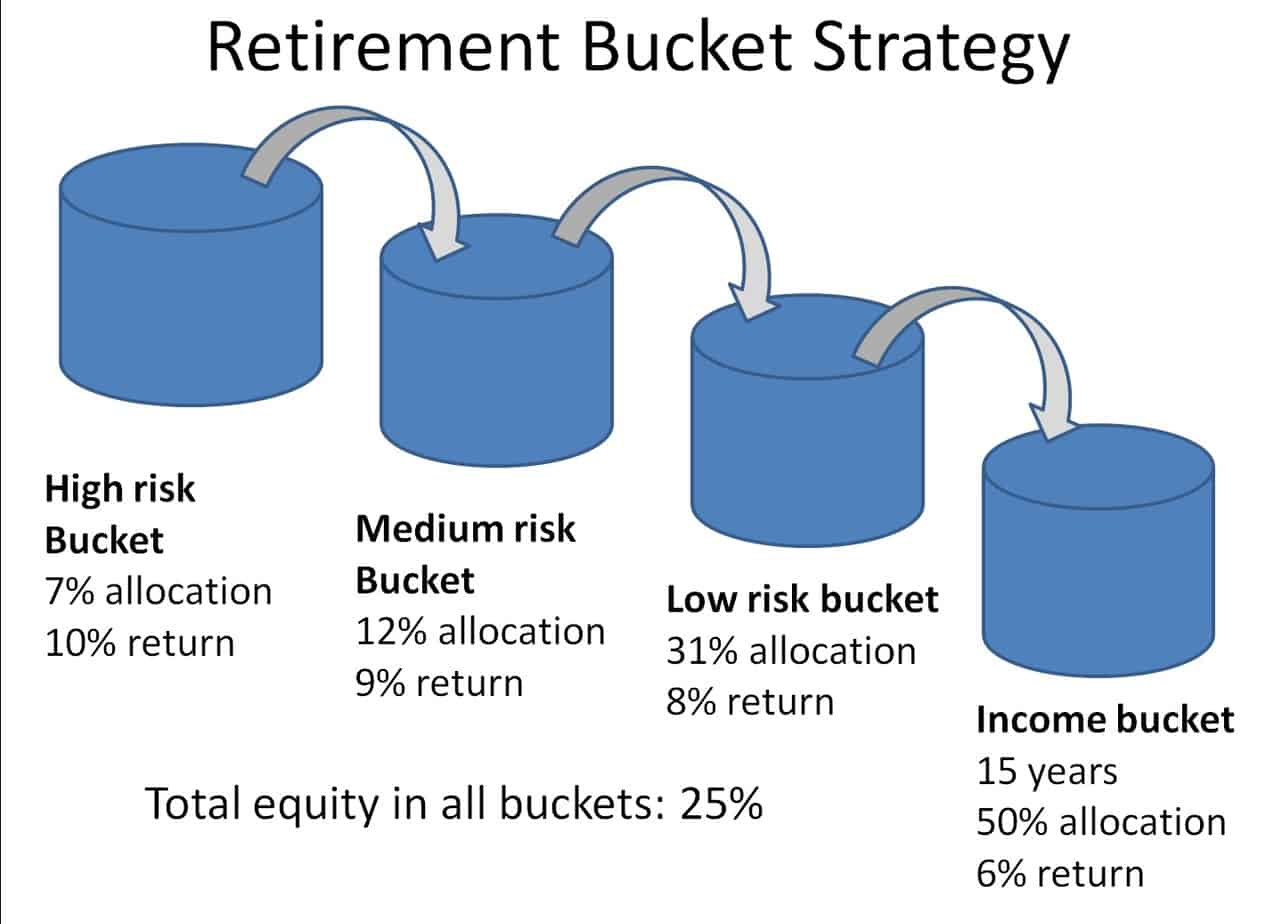
Creating retirement income with buckets
We will assume that the corpus will be distributed among the four buckets shown below. The income bucket will be used to generate inflation-protected income for the first 15 years in retirement. During the period, as per market conditions, money can flow from one bucket to another.
Another possibility:
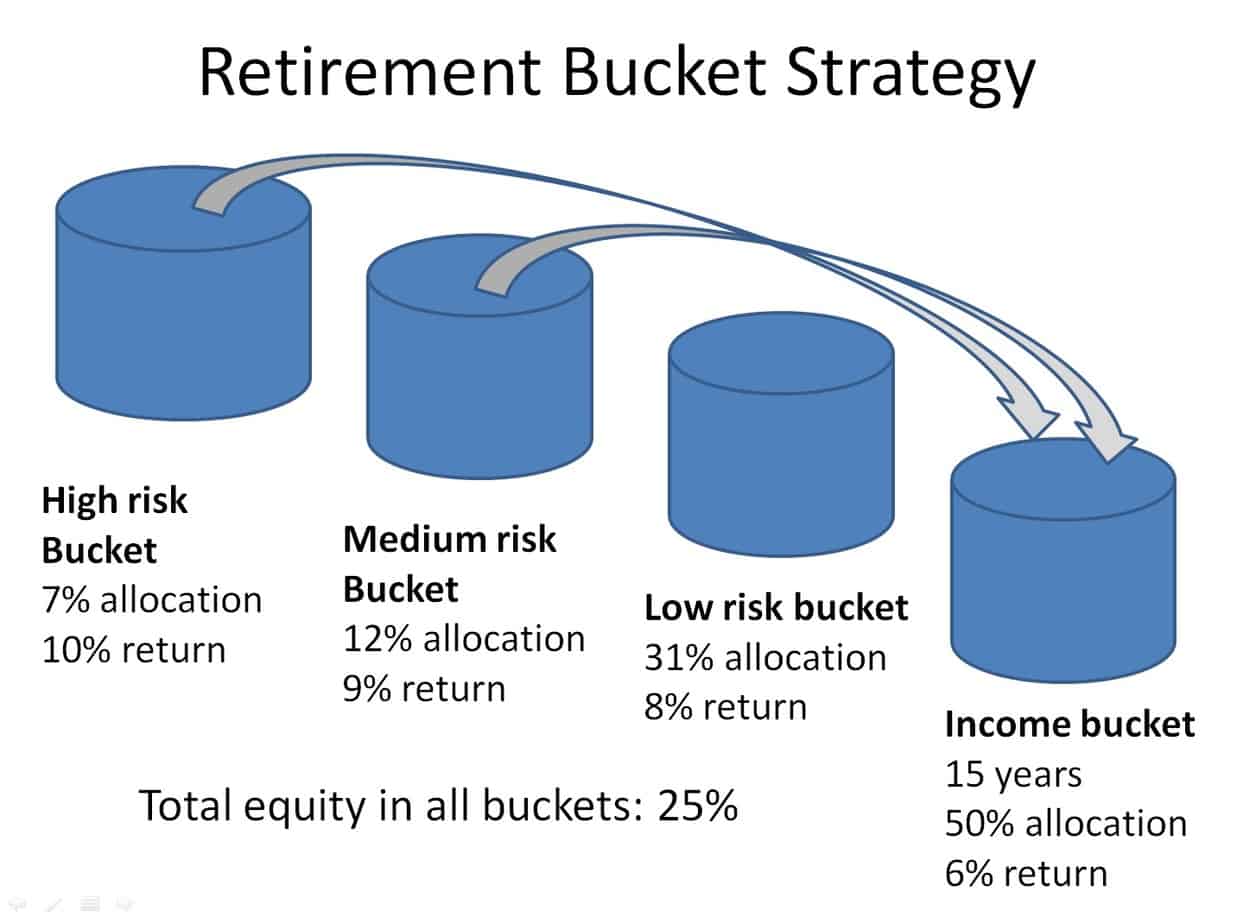
Please note that such switches cannot be calculated now. Rebalancing the buckets is a fantastic game and you can try the switching with random market returns to see how well you are doing. Play The Retirement Bucket Strategy Simulator.
This is the video version.
Will Amar be able to retire with financial freedom?
Mr and Mrs Amar have time on their side. So I am more than confident that with disciplined investing and disciplined risk management, they will be able to retire comfortably and fight inflation.
Re-assemble, is a series on the basics of money management aimed at beginners and young earners. This retirement plan is part of this series. Download the full re-assemble e-book