Last Updated on December 28, 2021 at 6:42 pm
Freefincal was started on May end 2012. So this is its 6th birthday and to mark the occasion I have compiled the post in the Re-assemble series into a pdf e-book. Re-assemble is a series of basic money management steps for beginners and young earners that was started in Nov 2017. Do share it with others if you find it useful.
The journey from 2012 to 2018 has been nothing short of extraordinary – personally and professionally. Freefincal via its readers has exposed me to how diverse human behaviour can be. I continue to learn about finance, web usage trends, SEO, social media, managing a website and online visibility.
Let me begin by first thanking you, the reader. Without your support, I would have stopped writing years ago. Not only did you regularly read the nonsense I churned out, you used the calculators, told me how to make them better, made it better yourself and constantly gave me new ideas to write about.
Perhaps it is hard for you to believe but every time I feel worthless, I would receive an email from one of you stating that freefincal has a made a difference in your life, the same day. That would instantly deflect me off that dark corner. As mentioned in the movie, Julie & Julia – blogging is like a regimen they teach at alcoholics anonymous. That is exactly how I see – a productive way to pass the time …. in between meals. Freefincal has nothing to do with financial literacy or financial awareness. God, I find those terms repulsive. Runaway from anyone who wants to spread those – yuck!
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
For those interested, (reasonably) detailed website analytics (via Google) is available at similarweb. Here is a snapshot. In 2017, a little more than one million people had visited the site (including repeat visitors) and viewed the content a bit more than 2 million times. In 2014 , it was 2 lakh visitors and half a million views. That is decent growth and reasonably good, steady traffic, and this is how they usually come:
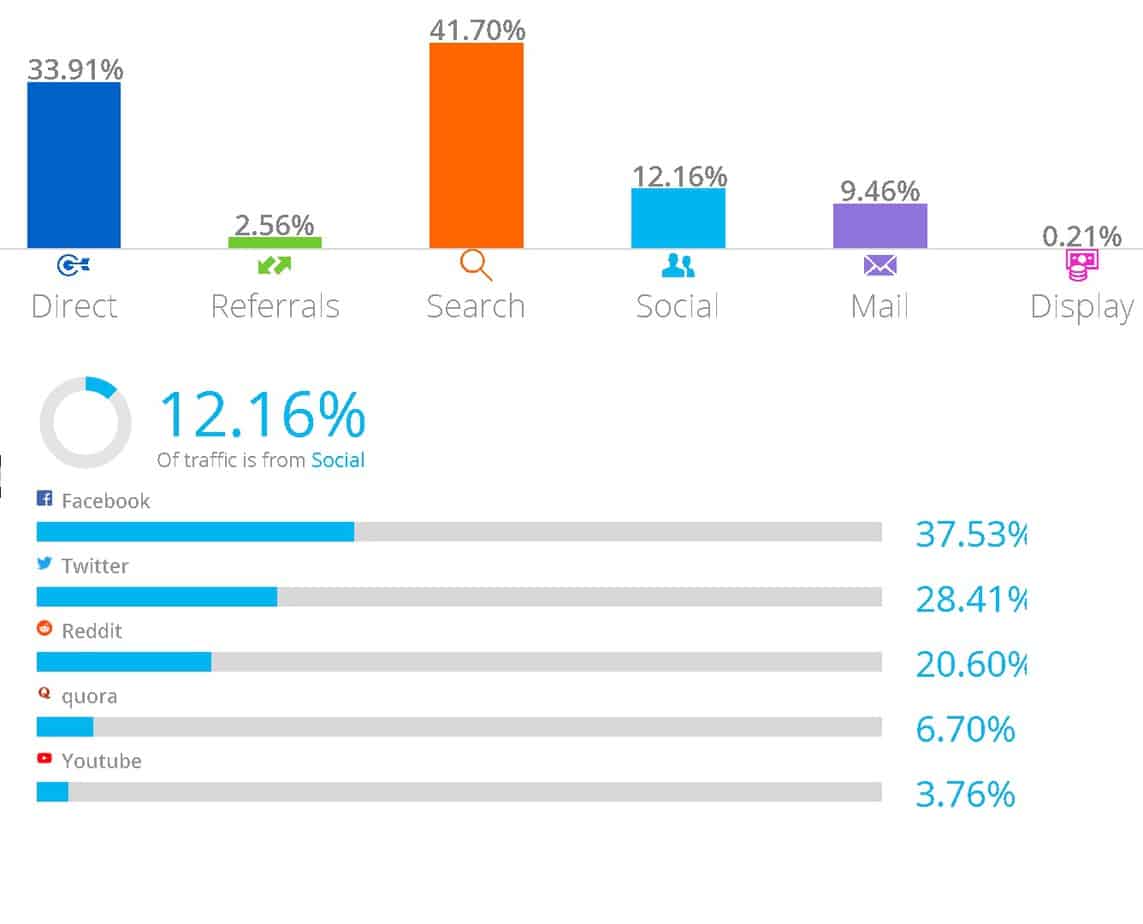
It is a matter of great pride that freefincal has very good “direct” viewership share. Traffic from Google is important but that is all it is -mere traffic. Direct visits imply reasonable brand identity. Focussing on SEO is important but it only means you are advertising your shop well. Direct traffic implies folks like the product and are repeat customers. As a site owner that is what is most valuable.
There is a difference between writing content that people are searching for and writing content that people should be reading. Pompous as this may sound, this is what sets freefincal apart and is possible only because you have supported it. If no one cared, it would have died long ago.
I am happy 10% of views come from email. In this age of social media, email is considered a private mode of online communication and I am honoured people do not mind emails from me. Push notifications are also rapidly catching on. If you are blogger and member of FB group Asan Ideas for Wealth, notice that only 5% traffic comes from FB (including my timeline and site page). So don’t take that group seriously. In the whole wide scheme of things, it means nothing. I spend time there because I am stupid and because it helps me learn real-life problems, not for the traffic.
For the same article, I have received feedback that “I have made things extremely easy to understand” and “I don’t understand what you are trying to say”. It takes all kinds to make the world. I cannot change my style. I can only write like I can write. I am thankful to those who get it. Those who don’t get it should probably look elsewhere.
Only about 20%-25% of people who read an article actually read up to the end. Even here, I know many who skip the math and go to the conclusions. I would wager that only 10% of that 25% would understand what I am trying to say. So don’t get any ideas about “my popularity”. Conclusion: it does not take much to motivate me!
Plans for the future
- I need to make more videos.
- Write more about post-retirement market risks
- Write more about health, parenting and lifestyle
- Tactical asset allocation
- Conduct more employee/reader seminars
- Write more on stock selection strategies. Is it possible to come up with a plumbline for stocks is something that I am actively considering (I don’t know the answer)
I look to your feedback with regard to real problems that many people face. Always a good topic to write about.
Download Re-assemble e-book
Contents:
Step 1: Listing your goals dreams and nightmares
Step 2: Lay the Foundations to Get Rich creating an emergency fund
Step 3: How to buy Term Life Insurance
Step 4: How to choose a suitable health insurance policy
* Apollo Munich Optima Restore Benefit vs Max Bupa Re-fill Benefit
* Star Health Comprehensive Insurance vs Religare Care Comprehensive Insurance
* Building a health insurance comparison chart + Cigna TTK vs Royal Sundaram Health Policies
* How to buy a Super Top-up Health Insurance policy
* How I selected a health insurance policy
* Why we all need a corpus for medical expenses and how to build it
Step 5: How to select a credit card for maximum benefit
Step 6: How to track monthly expenses and manage them efficiently
Step 7: How to close your loans and live debt-free
Step 8: How to buy a personal accident insurance policy
Step 9: Are you ready to let go and let your money grow?
Step 10: Investment planning case study 1: How to create an investment plan
Step 11: Case study 2: Retirement planning for 27-year old Amar
Step 12: Three Key Factors that decide how we achieve our financial goals
Step 13: How to start investing in equity?
Step 14: What should be my first mutual fund?
Step 15 (not part of this e-book) *:
(old) How to select an equity mutual fund in 30 minutes!
(New) How to select mutual funds after the SEBI categorization rules
Step 16: How to buy a house with a home loan: Tips to maximize benefits
Step 17: How to reduce risk in an investment portfolio
Note: * Mutual fund selection has become bit difficult after a reshuffle of fund categories by SEBI. Hence, I have decided to leave out step 15 from this compilation. Young Earners and beginners may instead choose from my hand-picked mutual fund list: PlumbLine
Download Re-assemble (and don’t forget to share this post with your friends!)