Last Updated on December 29, 2021 at 5:49 pm
Following the Supreme Court’s direction, the government came up with a scheme to waive off interest on interest during the 6 month moratorium period for eligible loans. As per the scheme, the lending institutions shall credit the difference between compound interest and simple interest to his account whether the borrower has availed the moratorium fully, partially or not availed at all. Here are some examples.
About the author: Manmohan Sethumadhavan is a Freelancer, investor, and personal finance enthusiast, “in search of the absolute truth” You can follow Manu on Twitter @ManuTsr.
Let us understand this scheme with an example. Ajay and Vijay – two borrowers who had an outstanding loan of 50 Lakhs @8.5% rate of interest. Ajay has availed moratorium. Vijay has not availed and paid back EMIs normally. Both loans are taken for 20 years. The compound interest for 6 months would be Rs.2,16,299 and simple interest would be Rs.2,12,500, a difference of Rs.3,799.
The scheme mentions that while making the calculation, the repayments in the loan account during the period will be ignored to make the approach uniform. So, Vijay too will get the benefit as if he has not paid. This will be credited back to his loan account. But in both cases, the important point is, it is credited to the loan account. EMIs are to be paid from the next month normally. So, the only effect is that the number of EMIs will change.
🔥Secure your future with our Robo-advisory tool trusted by over 3,500 investors and advisors. From effortless retirement planning to funding your children’s biggest dreams, turn your financial goals into reality. 🔥
Subscribe for money management solutions via email! (Link takes you to our email sign-up form) Join 32,000+ readers in our community.
👉 New Tool Alert! NaviPlan: A Privacy-Focused Multi-asset Tracker and Goal Planner 👈
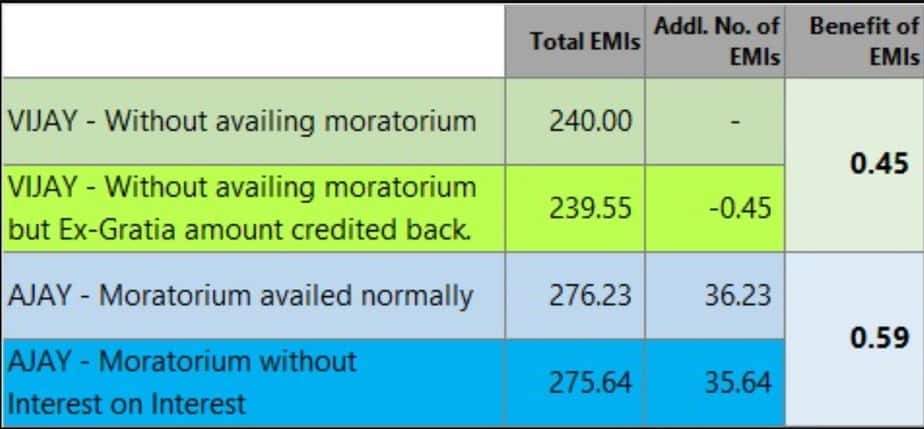
Both Ajay and Vijay had to pay 240 EMIs normally. Ajay availed moratorium and would have had to pay 276.23 EMIs. (36.23 EMIs extra). But due to the waiver of interest on interest, he needs to pay only 275.64 EMIs (35.64 EMIs extra; thus a benefit of 0.59 EMIs).
Now, Vijay who did not avail moratorium had to pay 240 EMIs, but he too got the benefit credited as Ex-Gratia payment. Hence, he needs to pay only 239.55 EMIs (a benefit of 0.45 EMIs).
But keep in mind that Ajay who availed moratorium is anyway going to pay around 36 EMIs extra for skipping just 6 EMIs. Also, in any case, the benefit will be reflected only towards the end of the loan period, i.e, after 23 years. The full calculation can be downloaded as a pdf file.